ICWIM Praxisprüfung - ICWIM PDF Testsoftware
2026 Die neuesten ZertSoft ICWIM PDF-Versionen Prüfungsfragen und ICWIM Fragen und Antworten sind kostenlos verfügbar: https://drive.google.com/open?id=1k4iDcXVw8PTKh3HasGFBPssnswx7_M3e
Die CISI Zertifizierungsprüfung ist jetzt eine sehr populäre Prüfung. Haben Sie diese CISI ICWIM Zertifizierung abgelegt? Wenn nein, sollen Sie bitte schneller etwas machen. Es ist sehr wichtig für Sie, diese wichtige Zertifizierung zu besitzen. Wie CISI ICWIM Zertifizierungsprüfung hocheffektiv vorzubereiten und nur einmal die CISI ICWIM Prüfung zu bestehen spielt heute eine sehr übergreifende Rolle.
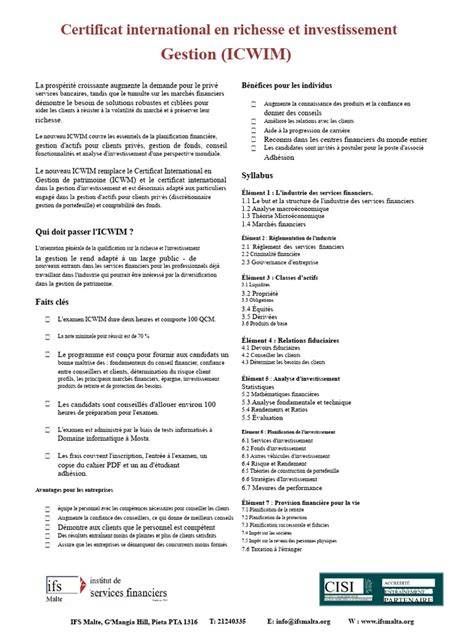
CISI ICWIM Exam Syllabus Topics:
| Section | Weight | Objectives |
|---|
| Topic 1: Client Advisory | 25% | - Client needs analysis
- 1. Time horizons
- 2. Risk profiling and suitability
- 3. Investment objectives
- Portfolio construction
- 1. Portfolio review and rebalancing
- 2. Performance measurement
- 3. Asset allocation strategies
|
| Topic 2: Financial Products | 20% | - Equities and shares
- 1. Types of equity
- 2. Dividends and total return
- 3. Valuation methods
- Collective investments
- 1. ETFs and index trackers
- 2. Funds and structured products
- 3. Fund selection criteria
- Bonds and fixed income
- 1. Credit risk
- 2. Bond types and characteristics
- 3. Yield and price relationships
|
| Topic 3: Market Environment | 20% | - Economic environment
- 1. Macroeconomic factors affecting investments
- 2. Interest rates and inflation
- 3. Business cycles
- Role and function of financial markets
- 1. Market indices and benchmarks
- 2. Types of financial markets and their roles
- 3. Market participants and intermediaries
|
| Topic 4: Risk and Return | 20% | - Portfolio theory
- 1. Risk-return profiling
- 2. Modern portfolio theory
- 3. Asset allocation principles
- Risk concepts
- 1. Types of investment risk
- 2. Risk measurement
- 3. Risk diversification
|
| Topic 5: Regulation and Ethics | 15% | - Regulatory framework
- 1. Investor protection
- 2. Financial regulation principles
- 3. Compliance requirements
- Ethical conduct
- 1. Conflict of interest
- 2. Professional responsibilities
- 3. CISI Code of Ethics
|
>> ICWIM Praxisprüfung <<
ICWIM International Certificate in Wealth & Investment Management neueste Studie Torrent & ICWIM tatsächliche prep Prüfung
Die Schulungsunterlagen zur CISI ICWIM Zertifizierungsprüfung von unserem ZertSoft sind führend unter allen Vorbereitern für CISI ICWIM. Unsere Prüfungsfragen und Antworten zur CISI ICWIM Zertifizierung sind das Ergebnis der langjährigen ständigen Untersuchung und Erforschung von den erfahrenen IT-Experten aus ZertSoft. Sie verfügen über hohe Genauigkeiten und große Reichweite. Wenn Sie unsere Produkte kaufen, werden Sie eihjährige Aktualisierung genießen.
CISI International Certificate in Wealth & Investment Management ICWIM Prüfungsfragen mit Lösungen (Q165-Q170):
165. Frage
An economy with two consecutive quarters of negative growth is considered to be in what phase of the economic cycle?
- A. Inflationary
- B. Depression
- C. Slump
- D. Recession
Antwort: D
Begründung:
A recession is defined as two consecutive quarters of negative GDP growth. It represents an economic downturn where output, income, and employment decline.
* Key Characteristics of a Recession:
* Falling GDP - Two successive quarters of contraction.
* Rising Unemployment - Businesses cut jobs due to weak demand.
* Declining Consumer Spending - Households reduce purchases.
* Lower Business Investment - Firms delay expansion plans.
* Difference Between Recession and Depression:
* A depression is a severe and prolonged recession (e.g., the Great Depression of 1929).
# Reference: UK Office for National Statistics (ONS) GDP Reports, CISI Wealth & Investment Management (Economic Cycles).
166. Frage
Shareholder value models seek to establish whether a company has the ability to add value for its ordinary shareholders. They do this by:
- A. Comparing current dividends to expected future dividends
- B. Assuming dividends will grow at a constant rate
- C. Measuring the change in net asset value NAV
- D. Comparing returns on assets to the cost of asset financing
Antwort: D
Begründung:
Shareholder value models focus on whether management is creating value beyond the cost of the capital employed. The central idea is that a company adds value only if the return generated on its assets or capital exceeds the cost of financing those assets, meaning the required return demanded by providers of debt and equity. This is why these models compare operating performance to the cost of capital. If returns exceed the cost of capital, value is created for shareholders; if returns fall short, value is destroyed even if accounting profits are positive. This logic underpins measures such as economic value added and related value-based management approaches, which adjust for the cost of funds tied up in the business. Measuring changes in net asset value is an asset-based approach and does not directly test value creation relative to funding costs.
Dividend growth assumptions and dividend comparisons relate more to dividend discount style valuation, not value-based performance models. The examinable distinction is that shareholder value models are about economic profit and value creation after charging capital costs, not simply accounting profit, dividends, or balance sheet movements.
167. Frage
When calculating business taxes on profits, what figure is used in addition to the profits made from a company's trading activities?
- A. Net current assets
- B. Declared dividends
- C. Chargeable gains
- D. Long term debt
Antwort: C
Begründung:
Business taxation on profits typically considers more than just the profit generated from normal trading operations. A company may also realise gains when it disposes of capital assets, such as property, subsidiaries, or investment holdings. These gains are treated separately from trading income and are commonly referred to as chargeable gains. They are included in the computation of taxable profits because they represent an increase in company value that has been crystallised through a sale or disposal event.
Declared dividends are distributions of post tax profits to shareholders and do not form part of taxable profits in the same way. Net current assets and long term debt are balance sheet figures that describe financial position and capital structure, but they are not additional categories of profit. The examinable distinction is between revenue profits from trading and capital profits from disposals. Therefore, when calculating taxes on profits, chargeable gains are added to trading profits to arrive at the total profits chargeable to tax, subject to the relevant rules and any allowable reliefs.
168. Frage
A firm has an existing client who is the head of a foreign state. What type of due diligence should the firm undertake if the client's spouse applies to become a client?
- A. Additional
- B. Simplified
- C. Standard
- D. Enhanced
Antwort: D
Begründung:
A client who is the spouse of the head of a foreign state is classified as aPolitically Exposed Person (PEP).
Firms are required to undertakeenhanced due diligence (EDD)for PEPs and their immediate family members due to the increased risk of corruption, money laundering, or misuse of public funds.
* Simplified (A): This applies to low-risk clients, not PEPs.
* Standard (B): Standard due diligence is insufficient for PEPs or their relatives.
* Additional (D): This term is not a formal category under anti-money laundering (AML) regulations.
References:
* International Certificate in Wealth & Investment Management: AML procedures and the treatment of PEPs.
* FATF (Financial Action Task Force) guidelines on enhanced due diligence for politically exposed persons.
169. Frage
The Financial Action Task Force (FATF) was created to:
- A. Combat international money laundering and international terrorism
- B. Improve financial regulation in G7 member states
- C. Support countries in developing their financial regulation
- D. Support international efforts to end safe havens for corrupt funds
Antwort: A
Begründung:
* Purpose of the FATF:
* Established in 1989, the FATF develops global policies to combat money laundering and terrorist financing.
* It promotes international standards to ensure financial systems are not misused for criminal purposes.
* Elimination of Other Options:
* A: The FATF's mandate is broader than G7 financial regulation.
* B: It provides guidance but does not solely focus on developing financial regulation.
* C: Ending safe havens for corrupt funds is part of its mission but secondary to its primary goal of combating money laundering and terrorism.
References:
* ICWIM Module 5: Focus on global financial regulation and anti-money laundering efforts.
* FATF Mandate (Official Publications): "Standards for combating money laundering, terrorist financing, and proliferation financing."
170. Frage
......
Die echten und originalen Prüfungsfragen und Antworten zu ICWIM Zertifizierung (International Certificate in Wealth & Investment Management) bei ZertSoft wurden verfasst von unseren IT-Experten mit den Informationen von ICWIM Prüfungen (International Certificate in Wealth & Investment Management) aus dem Testcenter wie PROMETRIC oder VUE.
ICWIM PDF Testsoftware: https://www.zertsoft.com/ICWIM-pruefungsfragen.html
- ICWIM Unterlage ➡️ ICWIM Musterprüfungsfragen 🤗 ICWIM Prüfungsfrage 📩 Suchen Sie jetzt auf ➡ www.deutschpruefung.com ️⬅️ nach [ ICWIM ] und laden Sie es kostenlos herunter 🐀ICWIM Ausbildungsressourcen
- ICWIM Originale Fragen 😊 ICWIM Dumps ♥ ICWIM Examengine ⛷ Erhalten Sie den kostenlosen Download von ⮆ ICWIM ⮄ mühelos über ☀ www.itzert.com ️☀️ 🔨ICWIM Praxisprüfung
- ICWIM Musterprüfungsfragen 🃏 ICWIM Unterlage 🚪 ICWIM PDF 🔡 Öffnen Sie die Webseite ➥ www.deutschpruefung.com 🡄 und suchen Sie nach kostenloser Download von ✔ ICWIM ️✔️ 🤲ICWIM Zertifikatsfragen
- ICWIM Examengine 🥱 ICWIM Tests 🤪 ICWIM Praxisprüfung 🏴 URL kopieren ☀ www.itzert.com ️☀️ Öffnen und suchen Sie ( ICWIM ) Kostenloser Download ⚽ICWIM PDF
- ICWIM Studienmaterialien: International Certificate in Wealth & Investment Management - ICWIM Zertifizierungstraining 🥉 Öffnen Sie die Webseite ✔ www.pass4test.de ️✔️ und suchen Sie nach kostenloser Download von ➥ ICWIM 🡄 🍹ICWIM Examengine
- ICWIM Zertifikatsfragen 🎐 ICWIM Ausbildungsressourcen 👲 ICWIM Examengine 🕤 Öffnen Sie ▶ www.itzert.com ◀ geben Sie ▶ ICWIM ◀ ein und erhalten Sie den kostenlosen Download 🙈ICWIM Praxisprüfung
- Die seit kurzem aktuellsten CISI ICWIM Prüfungsunterlagen, 100% Garantie für Ihen Erfolg in der Prüfungen! 🥢 Erhalten Sie den kostenlosen Download von { ICWIM } mühelos über “ www.itzert.com ” 🌛ICWIM Praxisprüfung
- ICWIM Dumps 🆖 ICWIM Prüfungsfrage 🛌 ICWIM Originale Fragen 🕖 Sie müssen nur zu ( www.itzert.com ) gehen um nach kostenloser Download von [ ICWIM ] zu suchen 🍣ICWIM Tests
- ICWIM Prüfungen 👨 ICWIM Praxisprüfung 🦳 ICWIM Musterprüfungsfragen 🚒 Suchen Sie jetzt auf ▶ de.fast2test.com ◀ nach ▛ ICWIM ▟ und laden Sie es kostenlos herunter 🖼ICWIM Zertifikatsfragen
- ICWIM Schulungsangebot, ICWIM Testing Engine, International Certificate in Wealth & Investment Management Trainingsunterlagen ⚒ Öffnen Sie die Webseite “ www.itzert.com ” und suchen Sie nach kostenloser Download von ⏩ ICWIM ⏪ 😧ICWIM Testantworten
- Die seit kurzem aktuellsten CISI ICWIM Prüfungsunterlagen, 100% Garantie für Ihen Erfolg in der Prüfungen! 🧫 Erhalten Sie den kostenlosen Download von 《 ICWIM 》 mühelos über ➽ www.zertfragen.com 🢪 🐖ICWIM Prüfungsfrage
- myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, tooter.in, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, rare-books.library.sites.carleton.edu, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, Disposable vapes
Laden Sie die neuesten ZertSoft ICWIM PDF-Versionen von Prüfungsfragen kostenlos von Google Drive herunter: https://drive.google.com/open?id=1k4iDcXVw8PTKh3HasGFBPssnswx7_M3e