BONUS!!! Download part of PDFBraindumps C11 dumps for free: https://drive.google.com/open?id=11E8kyxUgcJT6pY-CVdpUNad5HZYFO2xH
According to our investigation, the test syllabus of the C11 exam is changing every year. Some new knowledge will be added into the annual real exam. Some old knowledge will be deleted. So you must have a clear understanding of the test syllabus of the C11 study materials. Now, you can directly refer to our study materials. Our experts have carefully researched each part of the test syllabus of the C11 Study Materials. Then they compile new questions and answers of the study materials according to the new knowledge parts.
| Section | Weight | Objectives |
|---|---|---|
| Insurance Industry Overview | 10-15% | - Claims Handling - Insurance Market Structure - Regulation and Legislation |
| Liability Insurance | 15-20% | - Professional Liability - Commercial General Liability (CGL) - General Liability Concepts |
| Automobile Insurance | 15-20% | - Personal Automobile Coverage - Mandatory Coverage Requirements - Commercial Automobile Coverage |
| Insurance Operations and Contracts | 20-25% | - Insurance Contract Basics - Fundamental Principles of Insurance - Policy Structure and Interpretation - Underwriting Process |
| Property Insurance | 15-20% | - Property Coverage Forms - Valuation and Coinsurance - Policy Conditions and Exclusions |
| Risk and Insurance | 15-20% | - Risk Management Process - Risk Identification and Measurement - Insurable Risk - Nature of Risk |
>> Sample C11 Questions Pdf <<
C11 test guide is not only the passbooks for students passing all kinds of professional examinations, but also the professional tools for students to review examinations. In the past few years, C11 question torrent has received the trust of a large number of students and also helped a large number of students passed the exam smoothly. That is to say, there is absolutely no mistake in choosing our C11 Test Guide to prepare your exam, you will pass your exam in first try and achieve your dream soon.
NEW QUESTION # 68
What best describes a direct loss?
Answer: A
Explanation:
Adirect lossis damage that resultsimmediately and directlyfrom the action of an insured peril. For example, fire burning a building, wind damaging a roof, or theft taking merchandise. The loss must be theproximate (dominant) causeand must flow directly from the peril named or covered in the policy.
Option A is incorrect because direct loss refers to a peril's action, not to who caused it.
Option C describes extensions of coverage, not direct losses.
Option D describes anindirect (consequential) loss, such as business interruption resulting from a fire-not the physical damage itself.
Therefore, the correct definition of a direct loss isB: Damage to property by the direct action of an insured peril.
NEW QUESTION # 69
What is the name of the pooling agreement where all high-risk drivers are underwritten in a common pool?
Answer: B
Explanation:
The Facility Association is the Canadian automobile insurance mechanism designed to ensure that high-risk drivers, who cannot obtain insurance in the voluntary market, are still able to secure the legally required automobile insurance coverage. All auto insurers in participating provinces must be members, and losses and premiums in the pool are shared among them according to market share.
Option B, "Substandard Group," is not an official Canadian mechanism. Option C does not refer to any recognized underwriting pool for high-risk auto insurance. Option D is not an actual insurance entity.
Only the Facility Association accurately represents the mandatory pooling arrangement for high-risk drivers.
NEW QUESTION # 70
Patrice works as a broker meeting a new client. He is building rapport by performing similar actions to those of his client. Which form of in-person communication is he engaging in?
Answer: A
Explanation:
Mirroringis a communication technique used to build rapport by subtly matching another person's body language, tone, gestures, or pace of speech. It is widely used in sales, client consultations, and negotiations.
When done professionally and subtly, mirroring helps clients feel understood and creates psychological comfort, making it easier to discuss needs and gather accurate underwriting information.
Option B, copycatting, implies obvious or exaggerated imitation and is not a recognized professional communication method. Option C, transparency, refers to openness and honesty, not physical or behavioural alignment. Option D, open listening, is active listening-important, but unrelated to mirroring physical actions.
Since Patrice is deliberatelyperforming similar actionsto his client, he is engaging inmirroring, makingAthe correct answer.
NEW QUESTION # 71
Whose signatures wouldusuallyappear on therisk's policy?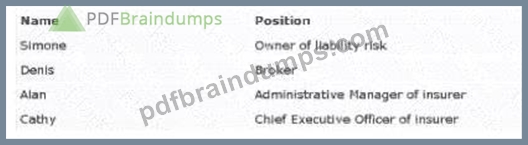
Answer: B
Explanation:
Apolicyis a legal contract issued by theinsurer, not the broker and not the policyholder. Therefore, the individuals who sign the policy are usually the insurer's authorized signing officers.
These are typically:
The CEO or President, and
Another authorized senior officer, such as the Administrative Manager or Underwriting Officer.
In the table:
Cathy(CEO) is an authorized signer.
Alan(Administrative Manager) is also an authorized insurer representative.
The insured (Simone) doesnotsign the actual policy document; their signature is not required for the policy to be valid. The broker (Denis) also doesnotsign policies; he facilitates placement but is not a party to the contract.
Thus, the correct pair isAlan and Cathy.
NEW QUESTION # 72
Ace Brokerage Inc., a liability insurer, has been in business for three years. It is suffering financial difficulties despite writing a significant amount of new business. What is the most likely reason?
Answer: C
Explanation:
For a new insurer, cash flow and premium collection are critical. Liability claims often take years to develop, but expenses such as commissions, reinsurance, administration, and claim reserves must be funded immediately. If premiums are not collected promptly due to poor management of accounts receivable, the insurer may not have sufficient liquidity to meet obligations-even if it has written a large volume of business on paper.
Option B is irrelevant because insurers (unlike brokers) do not receive profit-sharing commissions.
Option C is not typically a cause of financial distress since endorsements generateadditionalpremium.
Option D-discounting premiums-could affect income but would not normally create severe financial difficulty unless combined with other poor practices.
The most likely reason for early-stage financial trouble is failure to collect premiums efficiently, making A correct.
NEW QUESTION # 73
......
Our company is a professional certificate test materials provider, and we have rich experiences in providing exam materials. C11 exam materials are reliable, and we can help you pass the exam just one time. C11 exam dumps are also known as high pass rate, and the pas rate reaches 98.95%. We are pass guaranteed and money back guaranteed in case you fail to pass the exam. Moreover, we have free demo for C11 Exam Materials for you to have a general understanding of the product.
C11 Valid Exam Bootcamp: https://www.pdfbraindumps.com/C11_valid-braindumps.html
P.S. Free & New C11 dumps are available on Google Drive shared by PDFBraindumps: https://drive.google.com/open?id=11E8kyxUgcJT6pY-CVdpUNad5HZYFO2xH