P.S. Free & New F3 dumps are available on Google Drive shared by FreeDumps: https://drive.google.com/open?id=1vCDkCWp3LoUilF2lyTMg3JCdPryLfIl7
The exam time is coming, while you are not prepared well for F3 real test. Please do not be tense and worried, you can pass your F3 actual exam very simply and easily with FreeDumps F3 free pdf dumps. With the help of CIMA F3 free pdf practice, you can not only get high score in your actual test, but also can get more technology knowledge and be more professional.
| Certification Vendor: | CIMA |
|---|---|
| Exam Name: | Financial Strategy |
| Exam Number: | F3 |
| Real Exam Qty: | 60 |
| Related Certifications: | CIMA Management Level CGMA Designation CIMA Operational Level |
| Exam Duration: | 90 minutes |
| Passing Score: | 100/150 (≈50%) |
| Certificate Validity Period: | Indefinite (once qualification requirements are completed) |
| Exam Format: | Multiple Choice Questions, Computer-based Objective Test |
| Available Languages: | English |
| Recommended Training: | Kaplan CIMA Training CIMA Official Learning |
| Exam Registration: | CIMA Official Exam Registration Pearson VUE CIMA Exams Booking |
| Sample Questions: | CIMA F3 Sample Questions |
| Exam Way: | Computer-based exam delivered via test centers or approved online proctoring platforms. |
| Pre Condition: | Completion of CIMA Management Level (E2, P2, F2) is required before attempting F3. |
| Official Syllabus URL: | https://www.aicpa-cima.com |
We can't forget the advantages and the conveniences that reliable F3 study materials complied by our companies bring to us. First, by telling our customers what the key points of learning, and which learning F3 method is available, they may save our customers money and time. They guide our customers in finding suitable jobs and other information as well. Secondly, a wide range of practice types and different version of our F3 Study Materials receive technological support through our expert team.
To prepare for the CIMA CIMAPRA19-F03-1 exam, candidates must have a strong foundation in financial strategy. Candidates should have a good understanding of financial analysis and planning, as well as risk management and investment appraisal. Candidates should also have a good understanding of financial reporting and analysis.
NEW QUESTION # 423
Company A is planning to acquire Company B by means of a cash offer. The directors of Company B are prepared to recommend acceptance if a bid price can be agreed. Estimates of the net present value (NPV) of future cash flows for the two companies and the combined group post acquisition have been prepared by Company A's accountant. There are as follows: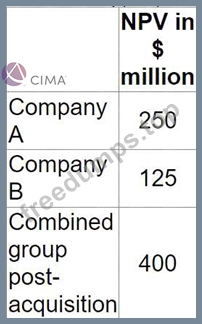
What is the maximum price that Company A should offer for the shares in Company B?
Give your answer to the nearest $ million
Answer:
Explanation:
150
Company A (stand-alone): 250m
Company B (stand-alone): 125m
Combined group: 400mIncrease in value available to A's shareholders from doing the deal:Gain=400#250=150 million\text{Gain} = 400 - 250 = 150
\text{ million}Gain=400#250=150 million If A pays price PPP for B, A's net gain = 150#P150 - P150#P.To ensure A's shareholders are no worse off, 150#P#0#P#150150 - P \ge 0 \Rightarrow P \le 150150#P#0#P#150.
So the maximum price A should offer is:Answer Q33: $150 million-Exhibit (54cae22f-961a-427a-8ad1-5d95bad9c7cf)-
NEW QUESTION # 424
Which TWO of the following statements about debt instruments are correct?
Answer: A,D
Explanation:
CIMA F3 links the cost of debt to the tax shield created by the tax deductibility of interest. The effective cost of servicing debt to a company is therefore the post-tax cost of debt, commonly expressed as kd(1#T)k_d(1-T) kd(1#T). This makes statement C correct: when evaluating financing decisions and WACC, the company benefits from interest tax relief, so the relevant servicing cost is after tax. Statement A is also treated as correct in the standard F3 exam context: zero-coupon debt pays no periodic coupon interest, so there are no regular interest payments generating the conventional annual tax-deductible interest expense and therefore the familiar tax-shield effect on "interest payments" is not obtained in the same way (i.e., the typical coupon- based shield is eliminated). Statement B is incorrect because the size of the tax shield depends on the tax rate; if corporation tax changes, the value of the tax relief changes. Statement D is incorrect because if corporation tax rates rise, the tax shield from deductible interest would increase, not reduce (a higher tax rate increases the tax saving per dollar of interest). Hence the two correct statements are A and C.
NEW QUESTION # 425
ADC is planning to acquire DEF in order to benefit from the expertise of DEF's owner 'managers Both are Listed companies. ADC is trying to decide whether to offer cash or shares in consideration for DEF's shares.
Which THREE of the following are advantages to ABC of offering shares to acquire CEF?
Answer: C,E,F
Explanation:
The question asks for advantages to the acquiring company (ADC/ABC) of using shares rather than cash to pay for DEF.
C). It incentivises DEF to continue creating value for the combined group If DEF's shareholders (and possibly managers) receive shares in ADC, they now own part of the combined business. That aligns their interests with ADC's existing shareholders and encourages them to help grow the value of the group.
E). The risk of poor future performance of the acquisition is shared with the DEF company shareholder.
If ADC pays with shares, DEF's shareholders share in both the upside and downside. If the acquisition underperforms, the fall in value is shared instead of all the risk resting on ADC's original shareholders. That's an advantage for ADC.
F). It preserves liquidity
Paying with shares means ADC does not need to use up cash or raise new debt. This preserves cash balances and borrowing capacity, which is a clear advantage.
Why not the others?
A (sharing benefits of future growth with DEF shareholders) is actually a cost from ADC's existing shareholders' viewpoint - they give away more of the upside.
B dilution of ownership is also a disadvantage, not an advantage.
D a tax saving for ABC - the tax impact is usually more relevant for sellers or when using debt, not typically a direct advantage of share consideration to the acquirer.
NEW QUESTION # 426
RR has agreed to sell goods to XX for S20.000 XX will pay when the goods are delivered in 6 months time.
RR's home currency is the £- The current exchange rate is 4.3 £/S. The projected inflation rate for the S is
2.8%, and for the E 4 6%.
When RR receives payment for its goods, what will the value be to the nearest pound?
Answer: A
NEW QUESTION # 427
A company is considering taking out $10.000,000 of floating rate bank borrowings to finance a new project.
The current rate available to the company on floating rate barrowings is 8%. The borrowings contain a covenant based on an interested cover of 5 times.
The project is expected to generate the following results: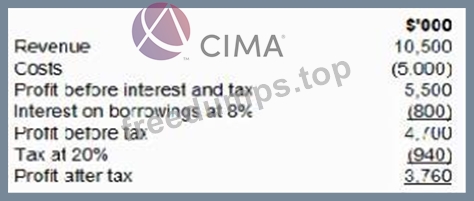
At what interest rate on the floating rate borrowings is the bank covenant first breached?
Answer: C
NEW QUESTION # 428
......
F3 Valid Test Discount: https://www.freedumps.top/F3-real-exam.html
BONUS!!! Download part of FreeDumps F3 dumps for free: https://drive.google.com/open?id=1vCDkCWp3LoUilF2lyTMg3JCdPryLfIl7