P.S. Free 2026 CSI AFP-Exam-1 dumps are available on Google Drive shared by LatestCram: https://drive.google.com/open?id=1OBR7lxYFuWHrg81ru4pbRwBsG1AnWN4Y
You may now download the AFP-Exam-1 PDF documents in your smart devices and lug it along with you. You can effortlessly yield the printouts of AFP-Exam-1 exam study material as well, PDF files make it extremely simple for you to switch to any topics with a click. While the Practice Software creates is an actual test environment for your AFP-Exam-1 Certification Exam. All the preparation material reflects latest updates in AFP-Exam-1 certification exam pattern.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Tax Planning | 14% | - Income Tax Fundamentals - Tax-Efficient Strategies - Tax Deductions and Credits - Registered Plans |
| Topic 2: Retirement Planning | 17% | - Retirement Needs Analysis - Registered Retirement Savings Plans - Pension Plans - Retirement Income Strategies |
| Topic 3: Investment Planning | 17% | - Asset Allocation - Investment Theory - Investment Products - Portfolio Construction |
| Topic 4: Estate Planning | 13% | - Estate Transfer Strategies - Wills - Trust and Beneficiary Planning - Powers of Attorney |
| Topic 5: Client Relationship and Practice Management | 6% | - Communication and Advisory Process - Client Discovery - Practice Management |
| Topic 6: Risk Management and Insurance | 12% | - Disability and Health Insurance - Life Insurance - Risk Transfer Strategies - Risk Assessment |
| Topic 7: Professional Conduct and Regulatory Compliance | 10% | - Compliance Responsibilities - Ethics and Professional Standards - Regulatory Requirements |
| Topic 8: Asset and Liability Management | 11% | - Cash Flow Management - Personal Balance Sheet Analysis - Debt Management - Budgeting |
>> AFP-Exam-1 Sample Questions Pdf <<
Now, do you want to enjoy all these CSI AFP-Exam-1 Exam benefits? Looking for a simple and quick way to pass the Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) exam? If your answer is yes then you do not need to worry about it. Just visit the "LatestCram" exam questions and download "LatestCram" exam questions and start preparation right now.
NEW QUESTION # 51
Kendrick, age 55, owns a successful small business, ZXC Inc., valued at $800,000. Kendrick has extensive savings outside of the business and would like to pass the company onto his son at some point in the future.
Kendrick expects the business to increase in value $25,000 per year. If Kendrick decides to use an estate freeze to reduce the amount of taxes he will be required to pay, his financial planner should recommend that he implement the estate freeze at which point in relation to gifting the business to his son?
Answer: C
NEW QUESTION # 52
Rob, age 42, is married with three children in elementary school. He works as an operations supervisor at a small manufacturing company, earning $70,000 annually. Rob asks his financial planner, Wendy, to liquidate his GIC investments worth $55,000 in order to use the sale proceeds to purchase a gold stock referred to him by his friend who expects the stock to appreciate significantly. Rob has not purchased stock before. What should be Wendy's reaction to Rob's query?
Answer: A
Explanation:
Wendy cannot treat Rob's request as routine order taking. He wants to liquidate $55,000 of GICs and buy a single gold stock based on a friend's expectation of appreciation, while he has a spouse, three young children, and no prior stock-purchasing experience. That is a major change in risk, concentration, liquidity, and suitability. The correct professional response is to review his risk tolerance, risk capacity, time horizon, objectives, investment knowledge, and financial circumstances before implementing or recommending the trade. Refusing the order outright may be unnecessary before analysis, while placing it without inquiry would ignore suitability obligations. Delaying and telling him to think about it is incomplete unless the planner completes the required review and documents the conversation. AFP conduct standards require the planner to slow the process when a proposed transaction conflicts with the known client profile. Study Guide focus:
KYC, suitability, concentration risk, unsolicited instructions, and professional duty of care.
NEW QUESTION # 53
Evan meets with his financial planner to review his concerns around inflation and its impact on his TFSA investment portfolio. His financial planner researches the current holdings and recommends that he sells one of the portfolio's equity funds. Which replacement option should the financial planner recommend to Evan?
Answer: D
Explanation:
The inflation concern directs the planner toward assets that may respond positively to rising prices. Real estate investment trusts hold income-producing property, and rents or property values may adjust over time as inflation affects replacement cost and lease rates. That does not make REITs risk-free, but they are more directly inflation-sensitive than nominal guaranteed products. GICs and treasury bills preserve nominal capital but may lose purchasing power after inflation and tax. Gold bullion may be used as a speculative inflation hedge, but it produces no income and can be volatile; it is not the best replacement for an equity fund within a diversified TFSA portfolio unless the mandate specifically permits that exposure. The planner should recommend an inflation-aware asset that remains investment-oriented and diversified. AFP investment planning treats inflation as purchasing-power risk, not simply price volatility. Study Guide focus: inflation risk, real assets, REITs, TFSA investment selection, and portfolio construction.
NEW QUESTION # 54
Demario, age 29, has started his own professional practice. He is single, has a mortgage, and his future earning power is his largest asset. Which insurance should receive priority?
Answer: A
Explanation:
For a young self-employed professional, the dominant exposure is interruption of earned income. Disability insurance protects human capital by replacing income if illness or injury prevents the client from working.
Because Demario is self-employed, he may not have employer long-term disability benefits, paid sick leave, or group coverage. Option B is irrelevant because joint last-to-die coverage is built for two lives and estate liquidity after the second death. Option C is narrow and does not protect ongoing income. Option D may be useful in some estate plans, but estate equalization is not the priority for a single client whose key asset is earning ability. The planner should review own-occupation wording, elimination period, benefit period, inflation indexing, residual disability benefits, integration with emergency savings, and business overhead coverage if practice expenses must continue. The correct planning lens is income protection before estate accumulation. References/topics: disability insurance, human capital, self-employed clients, income replacement.
NEW QUESTION # 55
Consider the following information for a client's portfolio: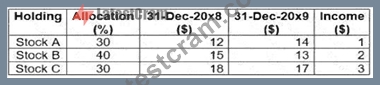
What is the annual rate of return for this portfolio?
Answer: C
Explanation:
The portfolio return must combine price change and income for each holding, then weight each holding by its allocation. Stock A rises from $12 to $14 and pays $1 of income, producing a return of ($14 + $1 - $12) / $12
= 25%. Stock B falls from $15 to $13 but pays $2, producing a 0% total return. Stock C falls from $18 to $17 and pays $3, producing ($17 + $3 - $18) / $18 = 11.11%. Applying the allocation weights gives 30% × 25%, plus 40% × 0%, plus 30% × 11.11%, which is approximately 10.8%. The answer is not based only on market value movement and not on a simple average of the three returns. AFP investment calculations require total return and allocation weighting. Study Guide focus: portfolio return, income return, capital return, weighted averages, and performance measurement. This is why the answer is a weighted total-return figure, not a yield figure or a price-only performance measure.
NEW QUESTION # 56
......
We have always been made rapid progress on our AFP-Exam-1 training materials because of the merits of high-efficiency and perfect after-sales services online for 24 hours. Studying with our AFP-Exam-1 actual exam, you can get the most professional information and achieve your dreaming scores by your first go. We can claim that as long as you study with our AFP-Exam-1 Exam Guide for 20 to 30 hours, you will pass your AFP-Exam-1 exam confidently.
AFP-Exam-1 Relevant Answers: https://www.latestcram.com/AFP-Exam-1-exam-cram-questions.html
2026 Latest LatestCram AFP-Exam-1 PDF Dumps and AFP-Exam-1 Exam Engine Free Share: https://drive.google.com/open?id=1OBR7lxYFuWHrg81ru4pbRwBsG1AnWN4Y