P.S. Fast2testがGoogle Driveで共有している無料かつ新しいPF1ダンプ:https://drive.google.com/open?id=1-ohIAXU2lnDcBQfCSC7TmrEEm0bD6Pa7
有名なブランドFast2testとして、非常に成功しているにもかかわらず、National Payroll Institute現状に満足することはなく、常にPF1試験トレントの内容を更新する用意があります。 最も重要なことは、PF1ガイドトレントの新しいバージョンをコンパイルしている限り、購入後1年間無料で最新バージョンのPF1トレーニング資料をお客様に送信します。 PF1試験に合格するのに役立つ、絶え間なく更新される試験の要求に合わせて、Payroll Fundamentals 1Examガイド急流を引き続きお届けします。
| Section | Objectives |
|---|---|
| Topic 1: Non-Statutory Deductions | - Voluntary deductions
|
| Topic 2: Termination of Employment | - Termination processing
|
| Topic 3: Record of Employment | - ROE processing
|
| Topic 4: Payroll Accounting | - Payroll accounting practices
|
| Topic 5: Commission Payments | - Commission payroll processing
|
| Topic 6: Non-Regular Payments | - Special payroll payments
|
| Topic 7: Year-End Processing | - Federal and provincial year-end reporting
|
| Topic 8: Workers’ Compensation | - Workers compensation administration
|
| Topic 9: Provincial Remittances | - Provincial payroll requirements
|
| Topic 10: New Employee Information | - Employee setup and documentation
|
| Topic 11: Employment Income – Regular Earnings | - Regular payroll calculations
|
| Topic 12: Federal Remittances | - Government remittance obligations
|
| Topic 13: Employment Income – Allowances, Expenses and Benefits | - Taxable and non-taxable benefits
|
>> National Payroll Institute PF1資格受験料 <<
弊社Fast2testの資料を使用すると、最短でPayroll Fundamentals 1Examの最高の質問トレントを習得し、他のことを完了するための時間とエネルギーを節約できます。 最も重要なのは、National Payroll InstituteのPayroll Fundamentals 1Exam学習資料を安全にPF1ダウンロード、PF1インストール、使用できることです。 製品にウイルスがないことを保証できます。 それだけでなく、最高のサービスと最高のNational Payroll InstituteのPayroll Fundamentals 1Exam試験トレントを提供し、製品の品質が良好であることを保証できます。 そのため、購入後はお気軽にご利用ください。お金を無駄にさせません。
質問 # 38
Ursula is 17 years old, works in Quebec and earns $750.00 weekly. Ursula pays weekly union dues of $18.00 along with a special weekly union assessment of $10.00 for construction of a new union hall for its members.
Ursula also has registered pension plan (RPP) contributions of $20.00 deducted from each pay. Calculate Ursula's net federal taxable income.
正解:
解説:
$712.00
Explanation:
For payroll income tax purposes, net taxable income starts with the employee's gross taxable income and then subtracts only those deductions that are deductible for income tax and can be recognized at source. CRA payroll guidance shows this approach by subtracting items such as RPP contributions and union dues when determining net taxable income for calculating income tax deductions.
Gross taxable income (weekly): $750.00.
RPP contributions are deductible (the amounts reported from box 20 of the T4 are generally deductible).
Regular union dues are deductible; however, the CRA states that deductible annual union/professional dues do not include special assessments or charges for anything other than ordinary operating costs. A levy specifically for constructing a new union hall is a special assessment, so it is not deductible as union dues.
So the deductions that reduce federal taxable income here are: $18.00 (union dues) + $20.00 (RPP) = $38.00.
Net federal taxable income = $750.00 # $38.00 = $712.00.
質問 # 39
Which of the following company-compulsory deductions would reduce the employee's gross taxable income for purposes of withholding income taxes?
正解:C
解説:
For payroll withholding, income tax is calculated on taxable income for the pay period, so only deductions that are income-tax deductible (or otherwise reduce taxable income at source) will reduce the employee's taxable base for withholding. Employee contributions to an RRSP are generally deductible for the employee, which is why payroll-deducted RRSP contributions (such as contributions to a group RRSP taken off the paycheque) reduce the amount of income tax withheld when the payroll system is set up to treat them as deductible contributions. The CRA confirms that deductible RRSP contributions can be used to reduce your tax.
By contrast, paying provincial health care premiums (where applicable) and paying an employee share of group benefit plan premiums are not automatic "reduce taxable income at source" deductions in the same way for payroll withholding; they may be personal expenses and, depending on the plan/premium type, may only affect the employee's personal tax situation through credits/deductions when filing, not the standard payroll withholding base. Therefore, the only correct choice is A.
質問 # 40
Helen is reimbursed for the cost of the protective clothing that is legally required for her job. The clothing she bought isnot supported by receiptsand is a reasonable reimbursement amount. This is considered:
正解:A
解説:
Even though the question uses the word "reimbursed," the key fact isno receipts. In CRA terms, when an employee is paid a set amount or is not required to substantiate the expense, the payment functions like an allowance, not an accountable reimbursement. CRA's guidance on uniforms/special or protective clothing states these amounts aregenerally taxable, and only in specific circumstances under CRA administrative policy would they be non-taxable.
CRA interpretations also reinforce that where employeesdo not have to provide receipts, a clothing allowance is generally ataxable employment benefit; non-taxable treatment is linked to substantiation and meeting strict conditions (for example, safety footwear with receipts).
So, because Helen's payment isnot supported by receipts, it is best classified as ataxable allowance(option A). Payroll should include the amount in taxable income, apply required withholdings as applicable, and ensure policy/records support whatever treatment is used.
質問 # 41
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)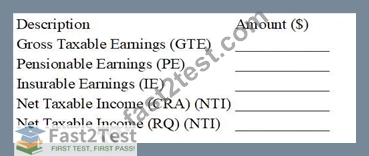
STATUTORY DEDUCTIONS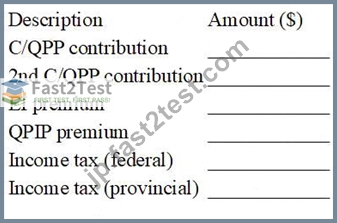
OTHER DEDUCTIONS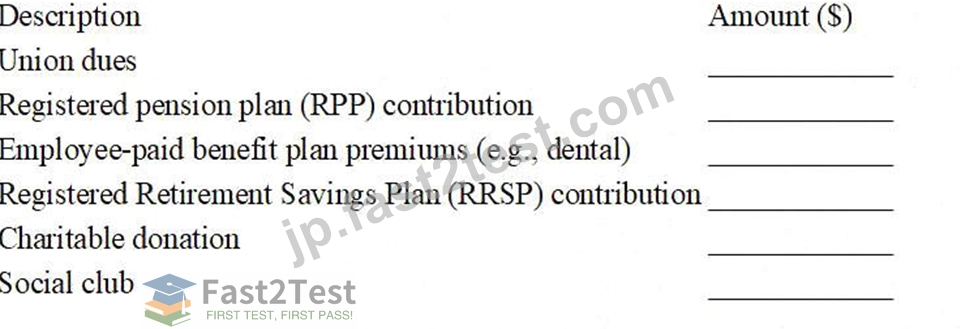
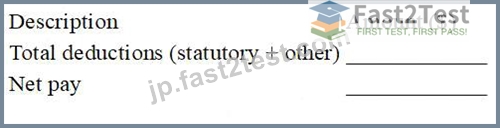
Given Data (Reference)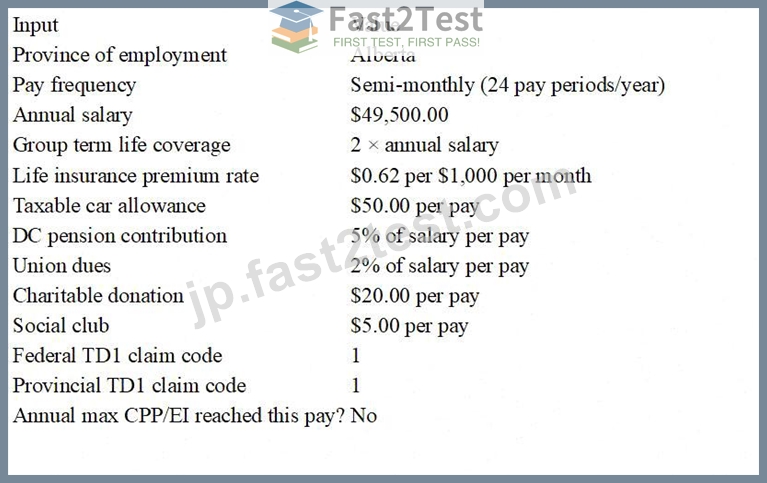
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
正解:
解説:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
質問 # 42
Charlene receives $50.00 each pay for her meals. This is an example of:
正解:C
解説:
A fixed amount paid to an employee for meals each pay period is typically a meal allowance. CRA guidance distinguishes an allowance from a reimbursement: an allowance is usually a set amount paid without the employee having to submit receipts for actual costs, while a reimbursement repays specific expenses and is generally supported by receipts or an expense claim.
Because Charlene "receives $50.00 each pay for her meals," it is a flat amount, which aligns with an allowance rather than a reimbursement. Whether the allowance is taxable or non-taxable depends on the facts (for example, whether it is reasonable and paid under conditions CRA recognizes as non-taxable for certain travel situations). If it's not a reasonable travel allowance under CRA's exceptions, it is generally a taxable allowance and must be included in income with appropriate deductions.
So the correct classification is A (an allowance).
質問 # 43
......
お客様に自分に一番ふさわしいNational Payroll InstituteのPF1試験の復習方式を提供するために、我々はNational Payroll InstituteのPF1の資料の3つのバーションを提供します。PDF、オンライン版とソフト版です。あなたの試験準備にヘルプを提供するのは常にあります。すべてのバーションは無料のデモを提供します。そのほかに、どのバーションでも全面的で最新版のNational Payroll InstituteのPF1の資料を提供します。
PF1問題サンプル: https://jp.fast2test.com/PF1-premium-file.html
P.S. Fast2testがGoogle Driveで共有している無料かつ新しいPF1ダンプ:https://drive.google.com/open?id=1-ohIAXU2lnDcBQfCSC7TmrEEm0bD6Pa7