P.S. Free & New PF1 dumps are available on Google Drive shared by DumpsTorrent: https://drive.google.com/open?id=1KIMD6Tu0TXg2p4ytt0oJvOU0vyjMBRz7
For years our company is always devoted to provide the best PF1 study materials to the clients and help them pass the test PF1 certification smoothly. Our company tried its best to recruit the famous industry experts domestically and dedicated excellent personnel to compile the PF1 Study Materials and serve for our clients wholeheartedly. Our company sets up the service tenet that customers are our gods and the strict standards for the quality of our PF1 study materials and the employee’s working abilities and attitudes toward work.
| Section | Objectives |
|---|---|
| Topic 1: Payroll Fundamentals and Compliance Framework | - Payroll system overview in Canada
|
| Topic 2: Earnings, Deductions, and Taxation | - Types of earnings
|
| Topic 3: Payroll Records and Compliance Reporting | - Government reporting
|
>> Question PF1 Explanations <<
In today's society, our pressure grows as the industry recovers and competition for the best talents increases. By this way the PF1 exam is playing an increasingly important role to assess candidates. Considered many of our customers are too busy to study, the PF1 real study dumps designed by our company were according to the real exam content, which would help you cope with the PF1 Exam with great ease. With about ten years’ research and development we still keep updating our PF1 prep guide, in order to grasp knowledge points in accordance with the exam, thus your study process would targeted and efficient.
NEW QUESTION # 22
Dollar values attributed to something the employer has either provided to an employee or paid for on an employee's behalf are:
Answer: B
Explanation:
The CRA defines a benefit as something the employee receives when the employer pays for or gives something that is personal in nature (a good or service), either directly to the employee or through a third party. CRA's T4130 guide describes a benefit as a good or service you give (or arrange for) such as free use of employer property, and it is the value of that benefit that may need to be included in the employee's income if taxable.
This matches the wording in the question: "dollar values attributed to something the employer has either provided...or paid for...on an employee's behalf." By contrast, earnings are pay for work performed (salary, wages, commissions). Allowances are fixed amounts paid to help cover anticipated expenses without receipts (often taxable unless an exception applies). Expense reimbursements repay actual business expenses (typically supported by receipts) and are generally not treated as earnings.
So the correct classification is Benefits.
NEW QUESTION # 23
Expense reimbursements are:
Answer: A
Explanation:
An expense reimbursement is paid to repay an employee for actual business expenses the employee incurred while performing their job (for example, meals while travelling on business, supplies purchased for work, etc.). CRA's taxable benefits guidance distinguishes reimbursements from allowances: an allowance is usually a predetermined amount paid without the employee having to support the expense with receipts, while a reimbursement is tied to actual costs.
That distinction matters because reimbursements are generally not compensation for work performed (so they are not "earnings"), and they are not "benefits" in the sense of a good or service provided by the employer (though CRA notes that benefits can include reimbursements of personal expenses-so payroll must still ensure the reimbursement is for business use and properly supported).
Option A correctly describes reimbursements. Option B is typically an allowance (for example, a vehicle allowance for using personal property). Option C describes earnings (wages/salary). Option D describes benefits (value of something provided or paid for on the employee's behalf).
NEW QUESTION # 24
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)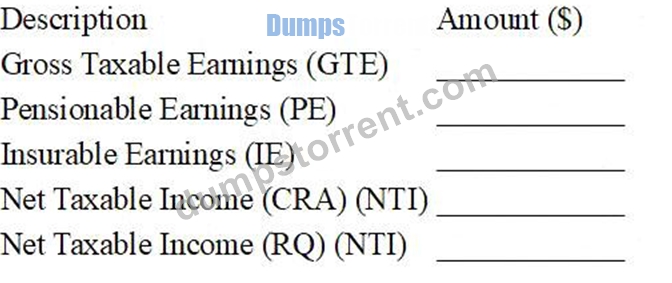
STATUTORY DEDUCTIONS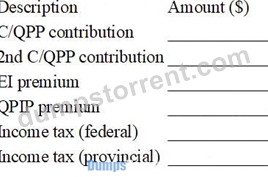
OTHER DEDUCTIONS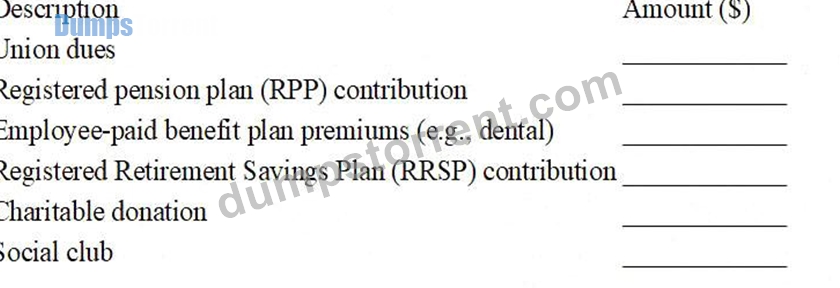
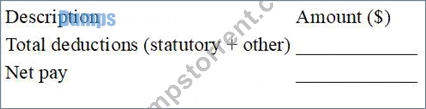
Given Data (Reference)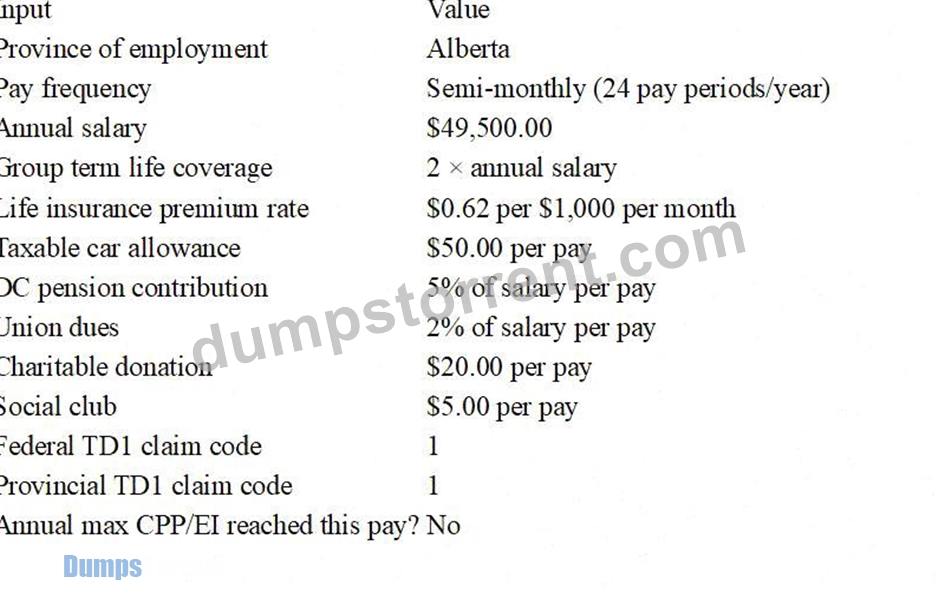
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
NEW QUESTION # 25
Phillip is being paid a severance payment with his final pay. Which block should this payment be reported on the Record of Employment?
Answer: B
Explanation:
On the ROE, separation payments are reported in Block 17. Service Canada explains that Block 17C - Other monies is used to record "any other payments or benefits...paid...because of the separation," whether or not they are insurable.
The ROE Guide specifically lists "Severance pay" as a type of separation money to enter in Block 17C ("Enter 'Severance pay' and the amount").
Crucially, Block 15B and Block 15C are for insurable earnings totals/by pay period. The ROE Guide notes that some amounts reported in Block 17 (like vacation pay) are insurable and must be added into Blocks 15B
/15C; however, retirement leave credits/retiring allowances (a form of severance-type payment) are not insurable and are not added to Blocks 15B/15C even though they are recorded in Block 17C.
So, severance is reported in Block 17C only.
NEW QUESTION # 26
Which of the following types of payments made by a private organization would not be subject to all statutory deductions?
Answer: C
Explanation:
The payment type most clearly not subject to all statutory deductions is directors' fees. CRA guidance on directors' fees shows they are treated as a special payment with distinct deduction rules, and (depending on the situation) they may not have CPP, EI, and income tax all apply in the same way as normal employment earnings.
By contrast, retroactive adjustments and performance bonuses are treated as taxable remuneration where CRA' s tools (like PDOC) calculate CPP contributions, EI premiums, and income tax on those payments (up to annual maximums).
"Vacation pay when no time was taken" is also treated as a non-periodic payment and is included in CRA payroll deduction formulas as a type of amount on which statutory deductions are calculated (again, subject to annual maximums for CPP/EI).
So, among the options listed, directors' fees are the one that would not necessarily be subject to all statutory deductions in the standard way.
NEW QUESTION # 27
......
With the increasing marketization, the PF1 study guide experience marketing has been praised by the consumer market. Attract users interested in product marketing to know just the first step, the most important is to be designed to allow the user to try before buying the PF1 study training materials, so we provide free pre-sale experience to help users to better understand our PF1 Exam Questions. The user only needs to submit his E-mail address and apply for free trial online, and our system will soon send free demonstration research materials of PF1 latest questions to download.
Valid Dumps PF1 Sheet: https://www.dumpstorrent.com/PF1-exam-dumps-torrent.html
2026 Latest DumpsTorrent PF1 PDF Dumps and PF1 Exam Engine Free Share: https://drive.google.com/open?id=1KIMD6Tu0TXg2p4ytt0oJvOU0vyjMBRz7