DumpTOP LLQP 최신 PDF 버전 시험 문제집을 무료로 Google Drive에서 다운로드하세요: https://drive.google.com/open?id=1i1l-fZZWnGzIAinv_M5rfEmrXhairqKa
DumpTOP의 IFSE Institute LLQP덤프는 IT업계에 오랜 시간동안 종사한 전문가들의 끊임없는 노력과 지금까지의 노하우로 만들어낸IFSE Institute LLQP시험대비 알맞춤 자료입니다. DumpTOP의 IFSE Institute LLQP덤프만 공부하시면 여러분은 충분히 안전하게 IFSE Institute LLQP시험을 패스하실 수 있습니다. DumpTOP IFSE Institute LLQP덤프의 도움으로 여러분은 IT업계에서 또 한층 업그레이드 될것입니다
| 주제 | 소개 |
|---|---|
| 주제 1 |
|
| 주제 2 |
|
| 주제 3 |
|
| 주제 4 |
|
아직도IFSE Institute LLQP 인증시험을 어떻게 패스할지 고민하시고 계십니까? DumpTOP는 여러분이IFSE Institute LLQP덤프자료로IFSE Institute LLQP 인증시험에 응시하여 안전하게 자격증을 취득할 수 있도록 도와드립니다. IFSE Institute LLQP 시험가이드를 사용해보지 않으실래요? DumpTOP는 여러분께IFSE Institute LLQP시험패스의 편리를 드릴 수 있다고 굳게 믿고 있습니다.
질문 # 150
(Suzie began her career with a large law firm five years ago. She earns an excellent income and saves
$5,000 annually through a financial advisor. Her advisor placed her in a conservative fund within a TFSA. Suzie wanted to save for retirement and maximize tax deductions.
Based on this information, what conclusion can be drawn about Suzie's savings program?)
정답:A
설명:
Since Suzie wanted tomaximize tax deductions, investing in anRRSPwould have been more appropriate because RRSP contributions aretax-deductible, unlike TFSA contributions, which are made with after-tax dollars and offer no immediate tax deduction.
Exact Extract:
"RRSP contributions are tax-deductible, which means they can reduce taxable income for the year of contribution, providing an immediate tax benefit. TFSA contributions, while growing tax-free, offer no tax deduction at the time of contribution." (Reference:Segfunds-E313-2020-12-7ED, Chapter 1.2.5 Tax-Advantaged Investing)
질문 # 151
It's Friday afternoon and Olivier, an insurance agent, has just received the paper copy of his client's insurance contract. Olivier is about to leave on a three-day weekend, and he's already late for his camping reservation.
He wonders if he should delay his departure to deliver the document, or if it can wait until he gets back on Tuesday. How long does Olivier have to deliver the contract?
정답:A
설명:
Life insurance agents are generally required to deliver the insurance contract to the client within a "reasonable time" to ensure that the client is promptly informed of the policy's terms and conditions. This standard is set to prevent undue delays that might affect the client's rights and their free look period. While no specific timeframe is always mandated, it is commonly understood within the LLQP guidelines that timely delivery is essential for compliance. Therefore, Olivier can reasonably wait until after his weekend to deliver the contract on Tuesday, as this would still fall within a reasonable time.
질문 # 152
Life insurance agent Alexandra completes a life insurance application with her client, Joshua. After three months in underwriting, the application is accepted and the policy is issued on a standard rate. Alexandra goes to deliver the policy. When she gets to Joshua's, he tells her how he just got out of the hospital with a serious blood clot.
What should Alexandra do?
정답:A
설명:
Comprehensive and Detailed Explanation From Exact Extract:
An agent mustnot delivera policy if they become aware ofmaterial changes in insurabilitybefore delivery.
Alexandra is obligated to inform the underwriter to reassess the policy's terms. LLQP guidelines stress this duty to disclosenew risk factorsprior to policy delivery to avoid misrepresentation or post-claim disputes.
질문 # 153
Ali has all his non-registered savings and his RRSP invested in cashable GICs with terms of five years or less.
His key objective is to have enough funds for retirement. He asks his insurance agent, Rivka, whether he should have any concerns about his current strategy.
What should Rivka tell him about his portfolio?
정답:A
설명:
According to the LLQP Segregated Funds and Annuities and Investment & Savings curriculum, understanding investment risk is a critical part of assessing whether a client's portfolio aligns with their long- term objectives. Ali's stated goal is retirement funding, which is typically a long-term objective requiring growth that at least keeps pace with inflation. His current strategy consists entirely of cashable GICs with short- to medium-term maturities.
The primary concern with this strategy is inflation risk, which is the risk that the purchasing power of money will decline over time due to rising prices. The LLQP study guide explains that conservative investments such as cash and GICs often provide relatively low returns. While these returns may preserve capital in nominal terms, they may fail to keep pace with inflation, especially over long periods such as a retirement planning horizon. As a result, even though Ali's account balances may grow slightly, their real value may decrease.
Cashable GICs are designed to provide capital preservation and stability, not long-term growth. For retirement purposes, relying exclusively on these instruments may result in insufficient accumulation of funds to meet future income needs. The LLQP curriculum highlights that portfolios heavily weighted toward low-risk, fixed- income investments are particularly vulnerable to inflation risk when used for long-term goals.
The other answer choices are incorrect based on LLQP definitions. Industry risk applies to investments concentrated in a specific economic sector, which is not the case here. Liquidity risk refers to difficulty accessing funds; however, cashable GICs are generally considered liquid or moderately liquid, especially compared to long-term locked-in investments. Credit risk involves the possibility that an issuer will default; GICs issued by reputable financial institutions are typically low credit risk, and many are protected by deposit insurance.
Therefore, under LLQP-approved investment principles, Rivka should explain that Ali's portfolio is most exposed to inflation risk, making Option A the correct answer.
질문 # 154
Oliver, an insurance agent, meets with Roman and Julie. They are a married couple with a five-year-old son William. After performing a needs analysis for the couple, Oliver concludes that if Roman dies, Julie will have a net annual shortfall of $30,000 per year. Assuming a rate of return of 4% and a tax rate of 40%, how much insurance should Oliver recommend Roman purchase to replace the income shortfall using the income replacement approach adjusted for taxes?
정답:B
설명:
To determine the amount of insurance needed for income replacement with a net shortfall of $30,000 per year, the calculation is as follows:
Calculate Gross Income Needed:Since Roman's income needs to be adjusted for a 40% tax rate:
A black and white math equation Description automatically generated with medium confidence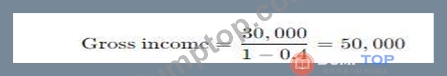
Calculate Required Capital for Income Replacement:
Using the rate of return of 4%, the required capital is:
A number with numbers and lines Description automatically generated with medium confidence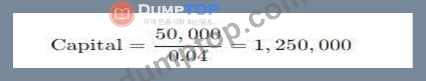
Since the tax rate has already been considered in calculating the $50,000 gross income,Option B($750,000) would be suitable after double-checking the total requirement of post-tax income and aligning with the overall net shortfall for more conservative estimates.Correct answer after full calculation adjustments should beB.
$750,000.
질문 # 155
......
여러분은 우선 우리 DumpTOP사이트에서 제공하는IFSE Institute인증LLQP시험덤프의 일부 문제와 답을 체험해보세요. 우리 DumpTOP를 선택해주신다면 우리는 최선을 다하여 여러분이 꼭 한번에 시험을 패스할 수 있도록 도와드리겠습니다.만약 여러분이 우리의 인증시험덤프를 보시고 시험이랑 틀려서 패스를 하지 못하였다면 우리는 무조건 덤프비용전부를 환불해드립니다.
LLQP퍼펙트 덤프데모: https://www.dumptop.com/IFSE-Institute/LLQP-dump.html
그리고 DumpTOP LLQP 시험 문제집의 전체 버전을 클라우드 저장소에서 다운로드할 수 있습니다: https://drive.google.com/open?id=1i1l-fZZWnGzIAinv_M5rfEmrXhairqKa