What's more, part of that Exam4Labs PF1 dumps now are free: https://drive.google.com/open?id=1foYB0LhGFgdIqE0CLH0MK7BGcqT1Ub--
We respect private information of our customers, and if you purchase PF1 exam dumps from us, your personal information such as name and email address will be protected well. Once the order finishes, your information will be concealed. We won’t send junk email to you. Besides, PF1 exam braindumps of us offer you free update for you, and we recommend you to have a try before buying, therefore you can have a better understanding of what you are going to buy. We have online service stuff, and if you have any questions about PF1 Exam Dumps, just contact us.
| Section | Objectives |
|---|---|
| Payroll Fundamentals and Compliance Framework | - Payroll legislation and regulatory bodies
|
| Payroll Records and Compliance Reporting | - Government reporting
|
| Earnings, Deductions, and Taxation | - Deductions and remittances
|
Inlike other teaching platform, the Payroll Fundamentals 1Exam study question is outlined the main content of the calendar year examination questions didn't show in front of the user in the form of a long time, but as far as possible with extremely concise prominent text of PF1 test guide is accurate incisive expression of the proposition of this year's forecast trend, and through the simulation of topic design meticulously. With a minimum number of questions and answers of PF1 Test Guide to the most important message, to make every user can easily efficient learning, not to increase their extra burden, finally to let the PF1 exam questions help users quickly to pass the exam.
NEW QUESTION # 16
Jasmine works for a Saskatchewan employer and earns $500.00 weekly. Calculate her Employment Insurance (EI) premium.
Answer:
Explanation:
$8.15 (employee EI premium for the week)
Explanation:
For employees whose province of employment is outside Quebec (including Saskatchewan), EI premiums are calculated by multiplying the employee's insurable earnings by the employee EI premium rate for the year, up to the annual maximum insurable earnings. For 2026, the employee EI premium rate outside Quebec is $1.63 per $100 of insurable earnings (which is 1.63%).
Jasmine earns $500.00 weekly and (based on the question) we assume all earnings are insurable and she has not reached the annual maximum. Her EI premium is:
$500.00 × 1.63% = $500.00 × 0.0163 = $8.15.
This amount is deducted from the employee's pay and later remitted to the CRA as part of the employer's regular payroll remittance. The maximum insurable earnings for 2026 is $68,900, but at $500 per week she would only hit the maximum later in the year (if at all), so the weekly premium calculation above applies.
NEW QUESTION # 17
What is the portion of a retiring allowance eligible to be transferred into a Registered Retirement Savings Plan (RRSP) or a registered pension plan (RPP) tax free based on?
Answer: D
Explanation:
The CRA sets out that the "eligible" portion of a retiring allowance that may be transferred directly to an RRSP/RPP under special rules is based on years of service before 1996 (and potentially an additional amount for certain pre-1989 years if specific pension/DPSP conditions are met). The CRA explains the eligible part is
$2,000 for each year (or part-year) of service before 1996, plus you may be able to transfer an additional
$1,500 for each year (or part-year) of service before 1989 where no employer pension/DPSP benefit was vested (or previously paid) for those years.
This is why the correct basis in the answer choices is the employee's years of service prior to 1996, not wages, age, or average earnings. Payroll needs this service history (including related employers where applicable) to correctly identify the eligible/non-eligible split and apply the right withholding and transfer reporting.
NEW QUESTION # 18
Dollar amounts that are paid to an employee to cover expenses that they incurred while performing their job, but are not considered in the calculation of an employee's earnings are:
Answer: A
Explanation:
An expense reimbursement is a repayment to an employee for business costs they already paid personally (for example, meals, mileage, supplies), typically supported by receipts or an expense report. CRA's guidance explains that a reimbursement is a payment made to repay amounts the employee spent while conducting the employer's business, and that a reasonable reimbursement is generally not included in the employee's income.
That's why reimbursements are generally not part of "earnings" for payroll calculations-they are not compensation for work performed; they are repayment of a business expense. This differs from an allowance, which is usually a fixed amount paid without requiring receipts; allowances are often taxable unless a specific CRA exception applies.
So the correct term for "dollar amounts paid to cover job expenses incurred, but not considered earnings" is expense reimbursements (option D). Payroll best practice is to ensure reimbursements are properly documented and reasonable to support non-taxable treatment.
NEW QUESTION # 19
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)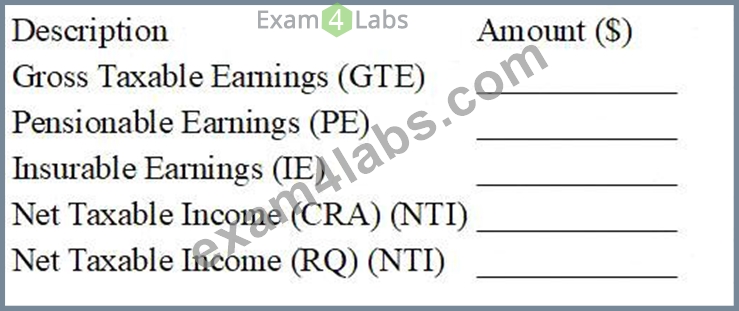
STATUTORY DEDUCTIONS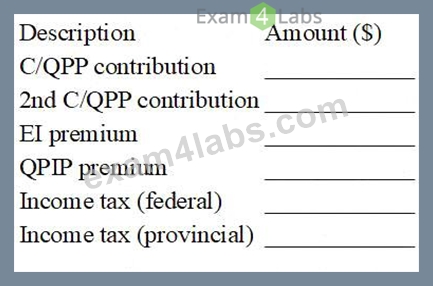
OTHER DEDUCTIONS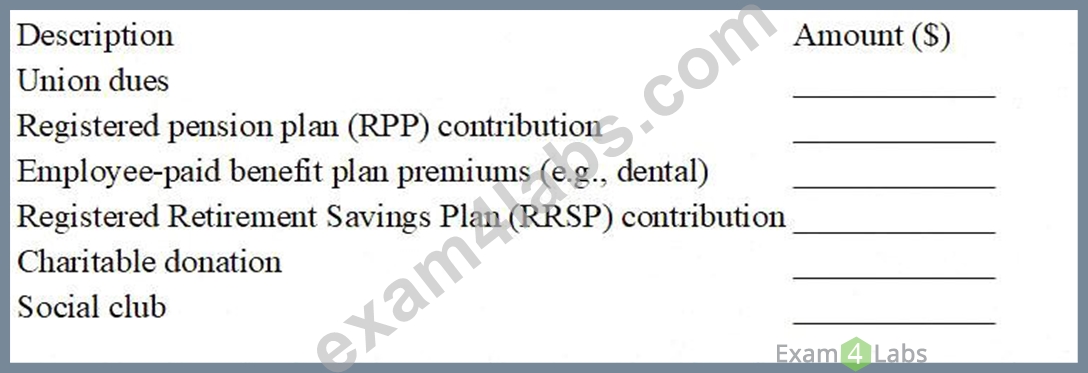
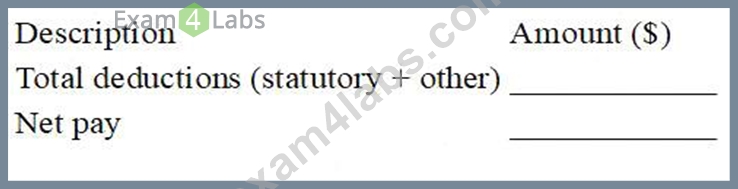
Given Data (Reference)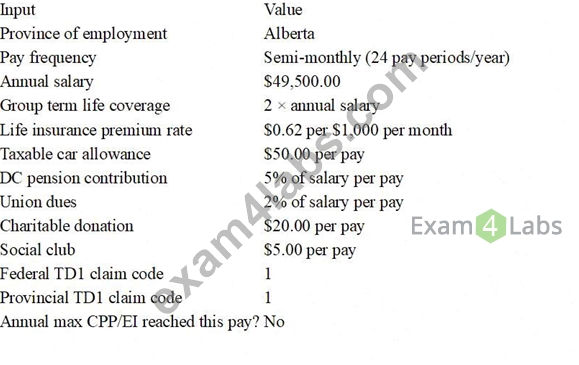
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
NEW QUESTION # 20
Rosa joined Avion Electronics in April 1983. Her employment was terminated on November 30, 2015 and she was paid a $62,500.00 retiring allowance. Rosa joined her company's pension plan in 1986 and was fully vested on termination of employment. Calculate the non-eligible portion of the retiring allowance.
Answer:
Explanation:
$32,000.00 non-eligible portion
Explanation:
CRA requires separating a retiring allowance into an eligible and non-eligible portion. The eligible portion is the maximum that can be transferred to an RRSP/RPP under the special rules (without using regular RRSP room). The formula is: $2,000 for each year (or part-year) of service before 1996, plus an additional $1,500 for each year (or part-year) before 1989 in which the employee had no employer pension/DPSP benefit vested at the time of payment (or previously paid).
Rosa worked from 1983 to 1995 (inclusive) for pre-1996 service: 13 years × $2,000 = $26,000.
For the extra pre-1989 amount: she joined the pension plan in 1986 and was fully vested when paid the retiring allowance in 2015, so 1986-1988 do not qualify for the extra $1,500. However, 1983-1985 were years before 1989 when she had no vested employer pension benefit, so 3 years × $1,500 = $4,500.
Eligible portion = $26,000 + $4,500 = $30,500.
Non-eligible portion = $62,500 # $30,500 = $32,000.
NEW QUESTION # 21
......
In order to meet the needs of each candidate, the team of IT experts in Exam4Labs are using their experience and knowledge to improve the quality of exam training materials constantly. We can guarantee that you can pass the National Payroll Institute PF1 Exam the first time. If you buy the goods of Exam4Labs, then you always be able to get newer and more accurate test information. The coverage of the products of Exam4Labs is very broad. It can be provide convenient for a lot of candidates who participate in IT certification exam. Its accuracy rate is 100% and let you take the exam with peace of mind, and pass the exam easily.
PF1 Latest Test Format: https://www.exam4labs.com/PF1-practice-torrent.html
BONUS!!! Download part of Exam4Labs PF1 dumps for free: https://drive.google.com/open?id=1foYB0LhGFgdIqE0CLH0MK7BGcqT1Ub--