弊社の理想はお客様の皆様の利益を保証してお客様のあなたに最高のサービスを提供して、我々の商品を利用してお客様は全員でGuidewireのClaimCenter-Business-Analysts試験に合格できることです。今まで、弊社はこの目的にずっと努力しています。弊社の頼もしい商品を利用してお客様のほとんどはClaimCenter-Business-Analysts試験に合格しました。弊社の専門家たちの努力とお客様のレビューがありますからこそ、我々はこのように自信があります。
| トピック | 出題範囲 |
|---|---|
| トピック 1 |
|
| トピック 2 |
|
| トピック 3 |
|
| トピック 4 |
|
| トピック 5 |
|
>> ClaimCenter-Business-Analysts認定資格 <<
GuidewireのClaimCenter-Business-Analysts試験を準備するのは残念ですが、合格してからあなたはITに関する仕事から美しい未来を持っています。だから、我々のすべきのことはあなたの努力を無駄にしないということです。弊社のIt-Passportsの提供するGuidewireのClaimCenter-Business-Analysts試験ソフトのメリットがみんなに認められています。我々のデモから感じられます。我々は力の限りにあなたにGuidewireのClaimCenter-Business-Analysts試験に合格します。
質問 # 15
Succeed Insurance had an embarrassing event last month that had potential legal ramifications. One of their Customer Service Representatives (CSR) shared details of a celebrity's personal auto claim on social media.
Fortunately for Succeed, the celebrity decided not to pursue legal actions as long as Succeed agreed to resolve the potential for future occurrences within the next 30 days.
Succeed executives immediately reacted to the situation by establishing new guidelines regarding claim security. The Business Analyst (BA) assigned to the project researched ClaimCenter base product capabilities and held several requirements gathering sessions designed to document their strategy. The new requirements indicate that only authorized users should be looking at celebrity claims.
Which two features should be used to meet the new requirements? (Choose two.)
正解:C、E
解説:
To restrict access to sensitive claims (such as those involving celebrities) so that "only authorized users" can view them, a Business Analyst must utilize the Claim Security features in Guidewire.
* Specify Claim Security Types (Option A):The first step is to define the classification of the claim.
The system uses the ClaimSecurityType typelist. The BA would add a new typekey (e.g., "Celebrity" or
"High Profile") or use an existing one (e.g., "Sensitive") to flag these specific claims.
* Create/Assign Access Profiles (Option E):Access control in Guidewire is managed throughAccess Profiles(sometimes referred to within Role configurations). An Access Profile maps specificSecurity Levels(like the "Celebrity" type defined above) to permissions. To meet the requirement, the BA defines an Access Profile that grants "View" permission for the "Celebrity" security type and assigns this profileonlyto the authorized users (or roles). Users without this specific Access Profile will be unable to search for or view the claim.
Why other options are incorrect:
* Authority Profiles (B):In Guidewire terminology, "Authority" refers strictly toFinancial Authority (limits on reserves and payments), not data access visibility.
* Hide secure fields (C):This refers toField Level Security(masking specific data like a Tax ID). The requirement is to restrict access to theentire claim, not just specific fields.
* Tracking rules (D):While "Claim Access Auditing" (tracking history) is often enabled for sensitive claims, it is a detective control, not a preventive one. The requirement specifies that unauthorized users should not be looking at the claim at all, which requires the Access Profiles (preventive control).
質問 # 16
Whenever the Total Loss Calculator determines that a vehicle is a total loss, Succeed Insurance wants to create a custom history event with the exposure name and total loss score.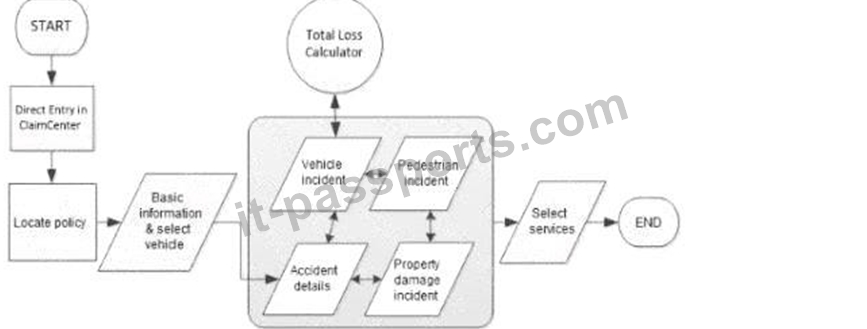
Which step in the claim setup process flow must be completed before the history event can be created?
正解:A
解説:
250 to 350 words From Exact Extract of Guidewire ClaimCenter Business Analyst documentation:
In Guidewire ClaimCenter workflow analysis and configuration, defining the correct sequence of operations is critically dependent on Data Availability and Data Dependency.
The specific requirement here dictates that the custom history event must capture theTotal Loss Score. In the context of the ClaimCenter object model and process flow, the Total Loss Score is anoutputvalue generated specifically by theTotal Loss Calculatorengine. Before this calculator runs, the score attribute is effectively null or non-existent.
Therefore, to satisfy the business requirement, the step that writes the history event must be placedafterthe step that generates the data it needs to record.
* Process Logic:If the Business Analyst were to place the history event creation stepbeforethe Total Loss Calculator (Option B) orbeforethe Vehicle Incident (Option D), the system would attempt to write a record containing a score that has not yet been calculated. This would result in either a system error or a history event with a blank/zero value, failing to meet the business requirement.
* Dependency Chain:The workflow dependency is: Vehicle Data Entry -> Total Loss Calculation -> Score Generation -> History Event Creation.
* Implementation Note:In a typical Guidewire implementation, this logic is often handled via "Event Fired" rules or specific "Exit Points" in the workflow. The system waits for the confirmation that the Total Loss calculation service has successfully returned a result. Once that transaction is committed and the score is persisted on the Vehicle or Exposure entity, the subsequent rule to generate the History Event can trigger successfully.
Consequently,Option Cis the only viable placement in the process flow. It ensures that the prerequisite action (calculation) is complete and the required data payload (the score) is available for the subsequent action (logging the history event).
質問 # 17
A Business Analyst (BA) noticed that one of the User Story Card files for the project indicated that it had recently been modified. The BA wanted to see who changed it, what was changed, and why it was changed.
Where on the Story Card can the BA go to determine the changes recently made to it?
正解:A
解説:
In the standard Guidewire User Story Card template (an Excel-based tool used for requirements gathering), version control is manually tracked to ensure auditability and clarity among the project team.
* Document Control Tab (Option C):This is typically the first tab in the Story Card workbook. It contains a section specifically forAmendment History(or Revision History).
* Content:This section is designed to capture:
* Who:The author of the change.
* When:The date of the change.
* What/Why: A description of the modification (e.g., "Updated Acceptance Criteria based on Workshop feedback").
This provides the specific "Who, What, and Why" requested in the scenario.
Why other options are incorrect:
* File > Properties (A):This is standard Excel metadata. It shows the "Last Modified By" user and date, but it cannot explainwhatspecific cells were changed orwhy(the business context).
* Action Items (B):This tab tracks open questions or tasks, not the revision history of the document requirements.
* UI Fields (D):This tab tracks the requirements for screen fields, but does not serve as a changelog for the entire document.
質問 # 18
An auto claim is owned by Adjuster1. The Customer Service Representative (CSR) that created the claim owns one follow-up activity on the claim. An Injury Specialist owns an injury exposure on the claim. All these persons are members of Auto Team 1.
The Team Lead determines that Adjuster1 is overworked and reassigns the claim to Adjuster2, a member of Auto Team 2.
Which three people now have access to the claim? (Choose three.)
正解:D、E、F
解説:
250 to 350 words From Exact Extract of Guidewire ClaimCenter Business Analyst documentation:
In Guidewire ClaimCenter, access to a claim file is determined by Access Control Lists (ACLs), which are dynamically updated based on user roles and ownership. A user is granted access to a claim if they own the claim itself, or if they own a sub-object within that claim, such as an Activity or an Exposure.
* Adjuster2 (Option E):Upon reassignment, Adjuster2 becomes the newClaim Owner. The owner of the claim record always has full view and edit access to the claim.
* CSR (Option C):The CSR retains ownership of a specificActivity(the follow-up task). In the ClaimCenter security model, owning an open activity on a claim grants the user "view" access to the parent claim so they can perform the necessary work to complete their task. Reassigning the claim header does not automatically reassign the activities owned by other users.
* Injury Specialist (Option D):This user owns anExposure(a distinct financial sub-record for a specific coverage feature). Similar to activities, owning an exposure grants access to the parent claim. The reassignment of the main claim file from Adjuster1 to Adjuster2 does not strip the Injury Specialist of their ownership of the specific injury exposure.
Why Adjuster1 loses access:Adjuster1 was the previous owner. Once ownership is transferred to Adjuster2 (who is in a different group, "Auto Team 2"), Adjuster1 no longer meets the criteria for ownership access.
Unless Adjuster1 is explicitly added to the ACL manually or has "Super User" privileges (not stated), they lose the automatic access rights associated with being the owner.
質問 # 19
An auto accident in Chicago, Illinois has been reported to Succeed Insurance. The customer service representative uses the ClaimCenter standard Claim Wizard to set up the new claim. The policy is verified in effect and based on the reported exposures the total loss points calculated is 38. There is also a note to have an expert inspection via approved vendor.
What is the most likely claim setup with regards to this reported auto accident?
正解:B
解説:
ClaimCenter uses a logic-based process called Segmentation to categorize claims and Assignment to route them.
* Complexity (Points):The "Total Loss Points" score of38is significantly high. In standard configuration, high scores (typically indicating severe damage or total loss potential) trigger aHigh Complexitysegmentation.
* Assignment (Geography):The accident occurred inChicago (Midwest). The assignment rules will match the geography (Midwest) with the complexity (High/Complex). Therefore, it routes to the Midwest Complex Auto Adjusters Group.
* Workplan (Activity):The specific note regarding an "expert inspection" translates into a generated Activity(likely "Assign Vehicle Inspection" or similar) added to the claim's workplan.
Why other options are incorrect:
* A & D (Low/Mid Complexity):A score of 38 is too high for "Low Complexity" (which is usually for simple fender benders). Assigning a complex claim to a "Low Complexity" group would violate standard routing logic.
* C (Supervisor):Modern ClaimCenter configurations prefer Straight-Through Processing (STP) to a working group. Routing to a Supervisor is generally a fallback for exceptions, whereas this is a standard high-severity scenario that should go directly to the specialized adjusters.
質問 # 20
......
多くの人々は試験前のあらゆる種類の困難のためあきらめ、最終的に自己価値を高める機会を失いました。繁栄する多国籍企業として、私たちは常にこの問題の解決に取り組んでいます。たとえば、当社が開発したClaimCenter-Business-Analysts学習エンジンはClaimCenter-Business-Analysts試験を簡単かつ簡単にすることができ、自信を持ってこれを行ったと言えます。多くの人々は試験前のあらゆる種類の困難のためあきらめ、最終的に自己価値を高める機会を失いました。繁栄する多国籍企業として、私たちは常にこの問題の解決に取り組んでいます。たとえば、当社が開発したClaimCenter-Business-Analysts学習エンジンはClaimCenter-Business-Analysts試験を簡単かつ簡単にすることができ、自信を持ってこれを行ったと言えます。
ClaimCenter-Business-Analysts無料問題: https://www.it-passports.com/ClaimCenter-Business-Analysts.html