ちなみに、Jpexam L4M2の一部をクラウドストレージからダウンロードできます:https://drive.google.com/open?id=1FHo5uzBcUoYAgOJtoI8Qo9KPvb_EUHBC
試験のL4M2テスト問題を学習して準備するのに必要な時間は20〜30時間だけで、時間とエネルギーを節約できます。あなたが学生であっても、学校での学習、仕事、その他の重要なことで忙しく、Defining Business Needs学習に時間を割くことができないインサービススタッフであっても。ただし、L4M2試験の教材を購入すると、時間と労力を節約し、主に最も重要なことに集中できます。そして、最も重要なL4M2試験トレントを最短時間で習得し、最後に優れたL4M2学習準備でL4M2試験に合格することができます。
| Section | Objectives |
|---|---|
| Topic 1: Understand how to develop a business case for requirements to be sourced from external suppliers | - Analyse how market factors affect procurement |
| Topic 2: Understand market management in procurement and supply | - Contrast direct costs and indirect costs
|
| Topic 3: Understand the use of specifications in procurement and supply |
L4M2学習教材の練習試験や模擬試験はみんなにとって重要です。今のリビジョン条件はL4M2試験に参加する良い機会です。したがって、レビュープランを調整するために、L4M2の各練習問題を要約することが不可欠です。今、私たちはL4M2実際試験を模擬するためにオンラインテストエンジンとWindowsソフトウェアを追加しました。
質問 # 116
Which of the following can cause overhead variance? Select TWO that apply:
正解:A、B
解説:
Overhead variances arise when the actual overhead costs incurred differ from the expected amounts.
Managers want to understand the reasons for these differences, and so should consider computing one or more of the overhead variances described below. Each of these variances applies to a different aspect of overhead expenditures. It is not necessary to calculate these variances when a manager cannot influence their outcome.
Fixed Overhead Spending Variance
The fixed overhead spending variance is the difference between the actual fixed overhead expense incurred and the budgeted fixed overhead expense. An unfavorable variance means that actual fixed overhead expenses were greater than anticipated. The formula for this variance is:
Actual fixed overhead - Budgeted fixed overhead = Fixed overhead spending variance The amount of expense related to fixed overhead should (as the name implies) be relatively fixed, and so the fixed overhead spending variance should not theoretically vary much from the budget.
Fixed Overhead Volume Variance
The fixed overhead volume variance is the difference between the amount of fixed overhead actually applied to produced goods based on production volume, and the amount that was budgeted to be applied to produced goods. For example, a company budgets for the allocation of $25,000 of fixed overhead costs to produced goods at the rate of $50 per unit produced, with the expectation that 500 units will be produced. However, the actual number of units produced is 600, so a total of $30,000 of fixed overhead costs are allocated. This creates a fixed overhead volume variance of $5,000.
Variable Overhead Efficiency Variance
The variable overhead efficiency variance is the difference between the actual and budgeted hours worked, which are then applied to the standard variable overhead rate per hour. The formula is:
Standard overhead rate x (Actual hours - Standard hours)
= Variable overhead efficiency variance
A favorable variance means that the actual hours worked were less than the budgeted hours, resulting in the application of the standard overhead rate across fewer hours, resulting in less expense being incurred.
However, a favorable variance does not necessarily mean that a company has incurred less actual overhead, it simply means that there was an improvement in the allocation base what was used to apply overhead.
Variable Overhead Spending Variance
The variable overhead spending variance is the difference between the actual and budgeted rates of spending on variable overhead. The variance is used to focus attention on those overhead costs that vary from expectations. The formula is:
Actual hours worked x (Actual overhead rate - standard overhead rate)
= Variable overhead spending variance
A favorable variance means that the actual variable overhead expenses incurred per labor hour were less than expected.
In the study guide, CIPS splits overhead variance into volume and expenditure variance. They can be understood as variable and fixed overhead variance respectively.
質問 # 117
Which of the following activities are considered as primary activities of an organization according to Porter's value chain? Select TWO that apply:
正解:C、D
解説:
Primary activities consist of inbound logistics, operations, outbound logistics, sales & marketing, service.
Second activities consist of firm infrastructure, human resource management, technology development and procurement The following graph illustrate the value chain (Source: Smartsheet) Graphical user interface, diagram Description automatically generated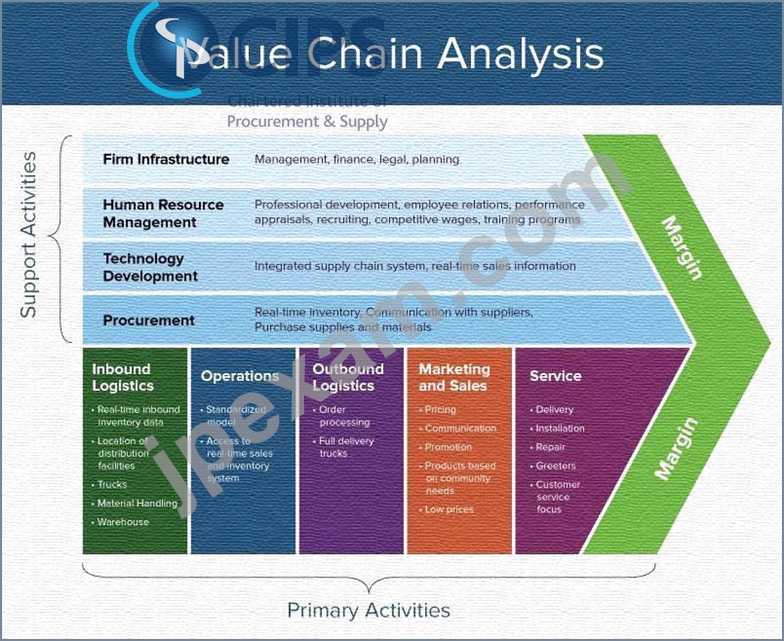
Picking and delivery components is inbound logistics.
Maintenance is an example of operations activity.
Sourcing transportation services is an activity of procurement
Assembly design is an activity in research and development (Technology) Recruiting is an activity of human resource management
質問 # 118
Which of the following are typical benefits of through-life asset management to buying organisa-tion? Select the TWO that apply.
正解:C、E
解説:
According to Andrew Graves, "Through-life Management involves the life-cycle management of the products, services and activities required to deliver a fully integrated capability to the customer, while reducing the cost of ownership for the customer." Benefits of through-life asset management can be:
- Lower total life-cycle costs
- Better match between the asset and end-user's needs
- Better supplier capabilities over time because it gains experience of buying organisation's needs.
Reference: CIPS study guide page 131
LO 3, AC 3.2
質問 # 119
XYZ Ltd is a large supermarket chain which operates mainly in the UK and Europe. Their custom-ers are increasingly concerned about sustainability. Therefore, procurement manager is required to source the products from suppliers who have good environmental performance. Which of the fol-lowing can be an assurance that the supplier has procedures and policies to enhance its environmental performance?
正解:A
解説:
ISO 9001:2015 specifies requirements for a quality management system.
ISO 14001:2015 specifies the requirements for an environmental management system that an or-ganization can use to enhance its environmental performance. ISO 14001:2015 is intended for use by an organization seeking to manage its environmental responsibilities in a systematic manner that contributes to the environmental pillar of sustainability.
ISO 22716:2007 gives guidelines for the production, control, storage and shipment of cosmetic products.
These guidelines cover the quality aspects of the product, but as a whole do not cover safety aspects for the personnel engaged in the plant, nor do they cover aspects of protection of the environment.
ISO 13485:2016 specifies requirements for a quality management system where an organization needs to demonstrate its ability to provide medical devices and related services that consistently meet customer and applicable regulatory requirements.
Reference: CIPS study guide page 125
LO 3, AC 3.1
質問 # 120
What is the document that defines the activities, deliverables and timelines a supplier must carry out during contract performance?
正解:D
解説:
Statement of Work (SoW) is the document that captures and defines all aspects of your project. You'll note the activities, deliverables and the timetable for the project. It's an extremely detailed document as it will lay the groundwork for the project plan.
Project Initial Document is an important document and should precede any specification writing project. It sets out the scope of the project and it is the team's mandate from senior management Work instructions are also called work guides, Standard Operating Procedures (SOPs), job aids or user manuals, depending on the situation. In any case, the purpose of work instructions is to clearly explain how a particular work task is performed.
Framework agreements are arrangements between one or more buyers and one or more suppliers that provide the terms governing contracts to be established for a certain period of time, in particular with regard to price and, where necessary, the quantity envisaged.
質問 # 121
......
Jpexamは、非常に信頼性の高いL4M2実際の質問の回答を提供しています。 主な利点は次のとおりです。1.直接情報を取得します。 2. 1年間の無料アップデートを提供します。 3. 1年間のカスタマーサービスを提供します。 4.パス保証; 5.返金保証など。 L4M2の実際の質問の回答を購入すると、安心してショッピングをお楽しみいただけます。 試験問題で試験に失敗した場合は、スキャンしたL4M2失敗スコアをメールアドレスに送信するだけで、他の疑いもなくすぐに全額返金されます。
L4M2問題サンプル: https://www.jpexam.com/L4M2_exam.html
BONUS!!! Jpexam L4M2ダンプの一部を無料でダウンロード:https://drive.google.com/open?id=1FHo5uzBcUoYAgOJtoI8Qo9KPvb_EUHBC