P.S. Free 2026 National Payroll Institute PF1 dumps are available on Google Drive shared by LatestCram: https://drive.google.com/open?id=1m-pJg9WxRSZlWJhKT1PIlmezFJIjp1ji
Our PF1 practice materials are classified as three versions up to now. All these versions are popular and priced cheap with high quality and accuracy rate. They achieved academic maturity so that their quality far beyond other practice materials in the market with high effectiveness and more than 98 percent of former candidates who chose our PF1 practice materials win the exam with their dream certificate. Our PF1 practice materials made them enlightened and motivated to pass the exam within one week, which is true that someone did it always. The number is real proving of our PF1 practice materials rather than spurious made-up lies.
| Section | Weight | Objectives |
|---|---|---|
| Termination and Special Payments | 30% | - Leaves and absences
|
| Record of Employment (ROE) | 20% | - ROE completion requirements
|
| Individual Pay Calculations | 40% | - Non-regular earnings
|
| Communication and Compliance | 10% | - Stakeholder communication
|
>> PF1 Pass4sure Pass Guide <<
Are you on the way to pass the PF1 exam? Our PF1 exam questions will be the best choice for you. And if you still feel uncertain about the content, wondering whether it is the exact PF1 exam material that you want, you can free download the demo to check it out. You will be quite surprised by the convenience to have an overview just by clicking into the link, and you can experience all kinds of PF1 versions.
NEW QUESTION # 32
Elodie is paid her commissions together with her bi-weekly salary of $1,000.00. This pay period her commissions are $4,300.00. Calculate her Quebec Pension Plan (QPP) contribution for this pay period.
Answer:
Explanation:
$325.42
Explanation:
Because Elodie is subject to QPP, her pensionable earnings for the pay period include both salary and commissions (both are pensionable employment earnings, assuming no exemptions apply). First, determine total pensionable earnings for the bi-weekly pay:
$1,000.00 + $4,300.00 = $5,300.00.
For 2026, Revenu Quebec shows the QPP basic exemption is $3,500 annually and the (employee) QPP contribution rate on earnings up to the maximum pensionable earnings is 6.30%.
Payroll applies the exemption per pay period. For bi-weekly pay (26 pay periods):
$3,500 ÷ 26 = $134.62 (rounded to cents).
Pensionable earnings subject to QPP this pay:
$5,300.00 # $134.62 = $5,165.38.
QPP contribution:
$5,165.38 × 6.30% = $5,165.38 × 0.063 = $325.41894, which rounds to $325.42.
NEW QUESTION # 33
An organization pays the premiums for a sickness or accident plan for their president only. This would be considered:
Answer: B
Explanation:
Because the plan is for the president only, it is a non-group insurance plan (a plan offered to an individual employee). The CRA states that when an employer pays premiums or makes contributions to a non-group insurance plan, the amounts paid are a taxable benefit. The CRA explicitly includes sickness or accident, disability, and income maintenance plans in this non-group category.
This benefit is generally treated as a non-cash taxable benefit because the employer is paying the premium directly to the insurer (the employee receives the coverage, not cash). CRA guidance distinguishes cash benefits (paid as money, reimbursements, or allowances) from benefits provided in a manner other than cash.
Payroll must therefore include the value of the employer-paid premium in the employee's taxable income and report it on the appropriate slip (commonly T4 code 40 for current employees, as noted in CRA instructions for insurance premiums).
NEW QUESTION # 34
Vacation pay on termination would be recorded in which Block(s) on the Record of Employment?
Answer: D
Explanation:
Service Canada's ROE Guide is clear that vacation pay paid because of separation (termination/layoff) must be reported in Block 17A - Vacation pay.
But it doesn't stop there. Vacation pay is generally insurable earnings, so when you enter insurable earnings in Block 17A, you must also add those amounts into Block 15B (Total insurable earnings) and into Block
15C, Pay Period 1 (P.P. 1) as applicable. The ROE Guide explicitly states: when you enter insurable earnings in Blocks 17A/17B/17C, you must also add them to the totals in Blocks 15B and 15C (P.P. 1 field)-and it gives the example that vacation pay paid on separation must be added to 15B and 15C because it is insurable.
Therefore, vacation pay on termination is recorded in Blocks 15B, 15C P.P. 1, and 17A (option C).
NEW QUESTION # 35
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
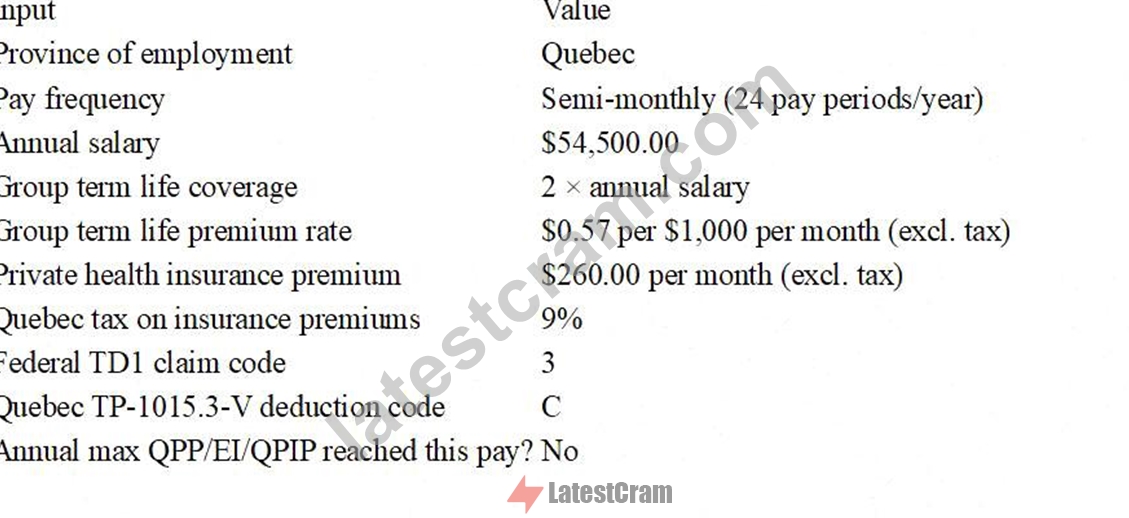
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases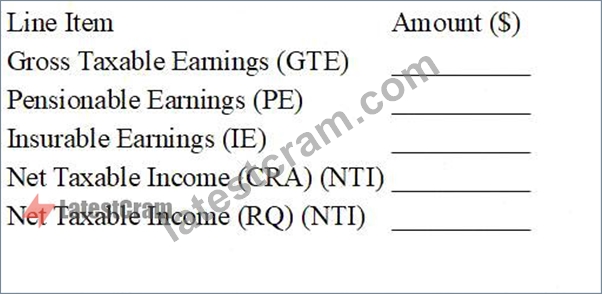
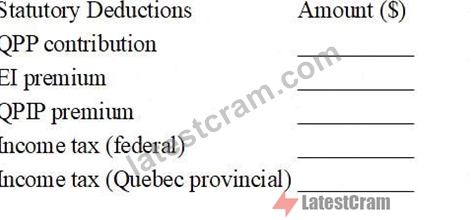
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
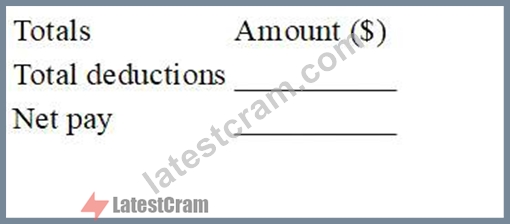
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
NEW QUESTION # 36
An interruption of earnings occurs when there is a period of how many days with no insurable earnings?
Answer: B
Explanation:
Service Canada's ROE Guide defines an interruption of earnings under the "7-day rule." It occurs when an employee has had, or is expected to have, 7 consecutive calendar days with no work and no insurable earnings from the employer.
This is specifically calendar days, not business days. That means weekends and holidays count in the seven- day sequence. The rule commonly applies when employees quit, are laid off, or are terminated, and it helps determine when an employer must issue an ROE (subject to certain listed exceptions and special situations, such as some employees with non-standard work patterns or employees mainly paid by commission).
From a payroll operations standpoint, correctly identifying the interruption of earnings is critical because it triggers ROE deadlines and affects the employee's ability to access EI benefits without delay. So the correct answer is Seven calendar days (option D).
NEW QUESTION # 37
......
The LatestCram offers three formats for applicants to practice and prepare for the Payroll Fundamentals 1Exam (PF1) exam as per their needs. The pdf format of LatestCram is portable and can be used on laptops, tablets, and smartphones. Print real Payroll Fundamentals 1Exam (PF1) exam questions in our PDF file. The pdf is user-friendly and accessible on any smart device, allowing applicants to study from anywhere at any time.
Latest PF1 Dumps Files: https://www.latestcram.com/PF1-exam-cram-questions.html
BONUS!!! Download part of LatestCram PF1 dumps for free: https://drive.google.com/open?id=1m-pJg9WxRSZlWJhKT1PIlmezFJIjp1ji