BONUS!!! Pass4Test PF1ダンプの一部を無料でダウンロード:https://drive.google.com/open?id=1IpwwINvJqgoe_ChHF9CrTvtJIWaDlOTk
従来の見解では、練習資料は、実際の試験に現れる有用な知識を蓄積するために、それらに多くの時間を割く必要があります。 Pass4Testただし、Payroll Fundamentals 1Examの学習に関する質問はNational Payroll Instituteその方法ではありません。 以前のPF1試験受験者のデータによると、合格率は最大98〜100%です。 最小限の時間と費用で試験に合格するのに役立つ十分なコンテンツがあります。Payroll Fundamentals 1Exam PF1準備資料の最新コンテンツで学習できるように、当社の専門家が毎日更新状況を確認し、彼らの勤勉な仕事と専門的な態度が練習資料に高品質をもたらします。 Payroll Fundamentals 1Examトレーニングエンジンの初心者である場合は、疑わしいかもしれませんが、参照用に無料のデモが提供されています。
| Section | Weight | Objectives |
|---|---|---|
| Communication and Compliance | 10% | - Accuracy and documentation
|
| Record of Employment (ROE) | 20% | - ROE completion requirements
|
| Individual Pay Calculations | 40% | - Non-regular earnings
|
| Termination and Special Payments | 30% | - Leaves and absences
|
PF1学習資料では、すべてのお客様が選択できる3つの異なるバージョンを設計しています。 3つの異なるバージョンには、PDFバージョン、ソフトウェアバージョン、オンラインバージョンが含まれ、お客様が質問を解決し、すべてのニーズを満たすのに役立ちます。 PF1学習資料の3つの異なるバージョンはすべてのお客様に同じデモを提供しますが、すべてのお客様の異なる固有のニーズを満たす特定の機能も備えています。 PF1学習教材のオンラインバージョンの最も重要な機能は実用性です。
質問 # 19
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)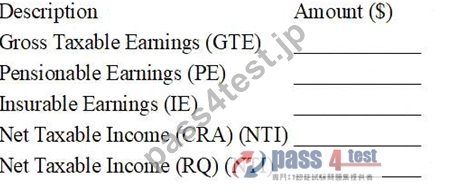
STATUTORY DEDUCTIONS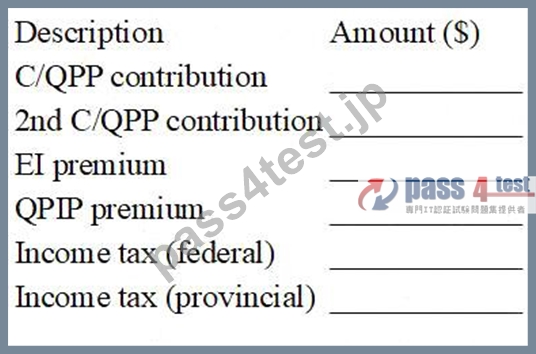
OTHER DEDUCTIONS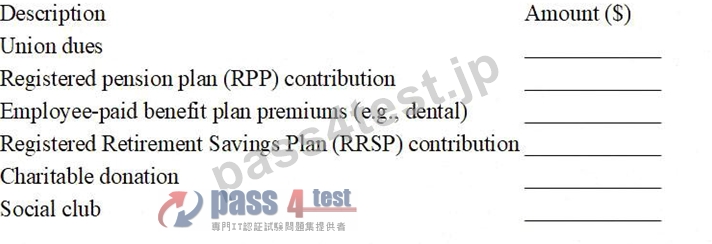
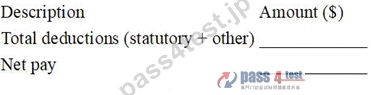
Given Data (Reference)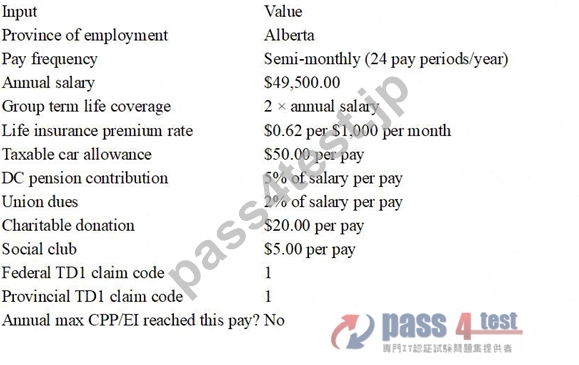
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
正解:
解説:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
質問 # 20
Paul Westin works for an Alberta organization and receives a regular salary of $1,800.00 semi-monthly. He will be receiving a payout of accrued vacation with no time taken of $1,400.00 on a separate cheque. He has federal and provincial TD1s on file with claim code 1. Calculate the income taxes to be withheld on his vacation pay.
正解:
解説:
341.50
Explanation:
CRA's method for bonus/irregular payments paid separately is to calculate income tax on the combined pay (regular pay + the irregular payment) using the regular tax tables, then subtract the tax that would apply to the regular pay alone. The difference is the income tax to withhold from the irregular payment.
Here, the semi-monthly taxable pay is:
Regular pay = $1,800.00
Regular + vacation payout = $3,200.00
Using the 2026 Alberta semi-monthly (24 pay periods) tax tables with claim code 1:
At $1,800, Federal tax = $130.45 and Alberta tax = $58.55 # Total = $189.00.
At $3,200, Federal tax = $356.50 and Alberta tax = $174.00 # Total = $530.50.
Income tax on the vacation payout = $530.50 # $189.00 = $341.50.
CPP (including the enhanced portion) is a separate statutory deduction that must also be calculated on the payout, but this question asked specifically for income tax withholding.
質問 # 21
Select the correct order of priority for withholding payroll deductions from an employee's earnings.
正解:B
解説:
Payroll deductions are typically applied in a priority order to ensure the employer meets mandatory legal obligations first and avoids creating liability. Standard Canadian payroll training materials commonly present five categories withheld in this order: (1) statutory deductions, (2) legal deductions, (3) union deductions, (4) company-compulsory deductions, and (5) voluntary deductions.
Statutory deductions (CPP/QPP, EI, income tax, and where applicable NWT/Nunavut payroll tax) have top priority because employers are legally required to deduct and remit them.
Legal deductions (such as CRA requirements to pay/garnishments) are next because they are enforced by law and can create employer liability if not followed.
Union deductions follow where required by a collective agreement.
Company-compulsory deductions (for example, required benefit premiums) come after those.
Voluntary deductions (charity, savings plans, etc.) are last and only taken if funds remain.
Therefore, option D is the correct order.
質問 # 22
By the authority of which Act can the Canada Revenue Agency garnish the wages of an employee who has failed to pay Employment Insurance premiums, Canada Pension Plan contributions, or income tax deductions?
正解:B
解説:
The CRA's wage garnishment tool is commonly issued as a Requirement to Pay (RTP) (and related instruments such as ERTP/DTP), which directs a third party (often the employer) to redirect amounts that would otherwise be paid to the employee, and send them to the government instead. CRA guidance explains that when an employee owes money, the CRA can send the employer a requirement to pay notice, and the employer must remit the amounts as instructed (or the employer can become liable).
The legal authority for the CRA to issue a Requirement to Pay is found in the Income Tax Act, including section 224, which sets out the mechanism and consequences for non-compliance.
In payroll operations, this is a communication-and-compliance issue: payroll must correctly interpret the notice, apply the withholding/remittance as directed, and communicate impacts to internal stakeholders (HR
/finance) and, where appropriate, the affected employee-while ensuring the remittance is made exactly as the CRA notice requires.
質問 # 23
Tanya submitted a letter of resignation to her employer on April 2 of the current year advising that she would be resigning her position effective April 27 for the pay period ending April 28. What date will appear in Block
11 of Tanya's Record of Employment?
正解:D
解説:
Block 11 on the ROE is "Last day for which paid." Service Canada instructs employers to enter the last day for which the employee received insurable earnings. This date usually coincides with the last day of work, unless the employee continues to receive insurable earnings after the last day worked (for example, paid leave like vacation/sick leave or salary continuance).
In Tanya's case, she gave notice on April 2, but her resignation is effective April 27. There's no information indicating paid leave after April 27 or salary continuance. So Block 11 should be April 27 (the last day she worked/received insurable earnings).
The question also mentions the pay period ending April 28-that date belongs in Block 12 (Final pay period ending date), which is the end date of the final pay period that includes the Block 11 date, and is often different from Block 11.
質問 # 24
......
社会でより良く生き残るためには、私たちの社会の要件を理解しなければなりません。理論的な知識に加えて、より実践的なスキルが必要です。 PF1実践ガイドを使用すると、認定資格を迅速に取得でき、競争力が大幅に向上します。もちろん、あなたの利益はPF1証明書だけではありません。 PF1学習教材は、あなたの働き方とライフスタイルを変えます。他の人よりも効率的に作業できます。 PF1トレーニング資料は、このような大きな役割を果たすことができます。
PF1入門知識: https://www.pass4test.jp/PF1.html
2026年Pass4Testの最新PF1 PDFダンプおよびPF1試験エンジンの無料共有:https://drive.google.com/open?id=1IpwwINvJqgoe_ChHF9CrTvtJIWaDlOTk