BONUS!!! Jpexam PF1ダンプの一部を無料でダウンロード:https://drive.google.com/open?id=1Mc_wg4-tbIs91McWco3t1vldYf_bEAPk
National Payroll Instituteガイドトレントは、98〜100%の合格率と高いヒット率を高めます。弊社のPF1テストトレントは認定エキスパートを使用し、質問と回答は実際の試験に基づいて入念に選択されます。私たちのPF1研究急流の言語は理解しやすく、内容は重要な情報を簡素化しました。当社の製品は、機能を強化してPF1試験、タイミング機能、自己学習および自己評価機能をシミュレートし、学習者がPF1ガイドトレントを簡単かつ便利な方法でPayroll Fundamentals 1Exam習得できるようにします。
| Section | Weight | Objectives |
|---|---|---|
| Termination and Special Payments | 30% | - Leaves and absences
|
| Communication and Compliance | 10% | - Accuracy and documentation
|
| Individual Pay Calculations | 40% | - Regular earnings
|
| Record of Employment (ROE) | 20% | - Submission and deadlines
|
業界のリーダーとなっているために、我々は確かに独自のリソースを拡大し続ける必要があります。我々Jpexamは常に試験問題集とソフトウェアの内容を更新します。だから、あなたの使用しているNational Payroll InstituteのPF1試験のソフトウェアは、最新かつ最も全面的な問題集を確認することができます。あなたのNational Payroll InstituteのPF1試験準備のどの段階にあっても、当社のソフトウェアは、あなたの最高のヘルパープロフォーマになることができます。我々はNational Payroll InstituteのPF1試験のデータを整理したり、分析したりするため、経験豊富なエリートチームにそれを完了させます。
質問 # 30
Which of the following deductions would be the last payroll withholding in order of priority?
正解:B
解説:
In payroll, deductions are applied in a priority order so employers satisfy mandatory legal obligations first.
CRA collection tools such as a Requirement to Pay (RTP) and a Demand on a Third Party (DTP) are legal
/garnishment-type deductions. CRA explains that a Requirement to Pay directs a third party (often the employer) to send amounts otherwise payable to the employee to the CRA, and the employer must comply.
Company pension contributions (where participation is required as a condition of employment or under a plan
/collective agreement) are generally company-compulsory deductions-important, but they come after statutory and legal deductions. Voluntary insurance coverage is a classic voluntary deduction (the employee chooses it; it is not legally required). Voluntary deductions are normally taken last because they must not interfere with statutory/legal withholding obligations.
So among the options, voluntary insurance coverage is the one that would be withheld last in the order of priority.
質問 # 31
Which of the following types of payments made by a private organization would not be subject to all statutory deductions?
正解:D
解説:
The payment type most clearly not subject to all statutory deductions is directors' fees. CRA guidance on directors' fees shows they are treated as a special payment with distinct deduction rules, and (depending on the situation) they may not have CPP, EI, and income tax all apply in the same way as normal employment earnings.
By contrast, retroactive adjustments and performance bonuses are treated as taxable remuneration where CRA' s tools (like PDOC) calculate CPP contributions, EI premiums, and income tax on those payments (up to annual maximums).
"Vacation pay when no time was taken" is also treated as a non-periodic payment and is included in CRA payroll deduction formulas as a type of amount on which statutory deductions are calculated (again, subject to annual maximums for CPP/EI).
So, among the options listed, directors' fees are the one that would not necessarily be subject to all statutory deductions in the standard way.
質問 # 32
Which of the following types of earnings are not considered income from employment?
正解:D
解説:
Regular salary, vacation pay, and commissions are generally treated as income from employment because they are amounts paid for services performed during employment. In contrast, what many people call
"severance pay" is often classified by the CRA as a retiring allowance-an amount paid when or after an employee retires or loses their job, in recognition of long service or for the loss of employment.
This distinction matters in payroll because a retiring allowance has its own rules for withholding and potential RRSP/RPP transfer eligibility, and it is not treated the same way as normal employment income earned while actively employed. CRA technical guidance also draws lines between amounts that are employment income versus retiring allowance depending on the nature/timing of the payment.
So, among the options listed, severance pay (when it is a retiring allowance) is the one that is not considered income from employment in the way salary/vacation pay/commissions are.
質問 # 33
Charmaine's employment was terminated by her employer on April 13 of the current year. Charmaine had worked for her employer for 3 years and was paid 3 weeks of legislated wages in lieu of notice and two weeks' vacation pay with her final pay. What date should be recorded in Block 11 on Charmaine's Record of Employment?
正解:A
解説:
Block 11 on the ROE is the "Last day for which paid," meaning the last day the employee received insurable earnings. In most terminations, this is the employee's last day of work. Service Canada notes Block 11 only moves beyond the last day worked when the employee continues to receive insurable earnings after the last day of work due to paid leave (such as vacation leave or sick leave) or salary continuance.
In this question, Charmaine's employment ended April 13, and she received a lump-sum final pay that included wages in lieu of notice and vacation pay. These amounts are typically reported as special payments (for example, pay in lieu of notice is reported as such), but they do not automatically change Block 11 unless they are paid as an actual paid-leave period or as salary continuance (where regular pay continues and the ROE is not issued until the continuance ends).
質問 # 34
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
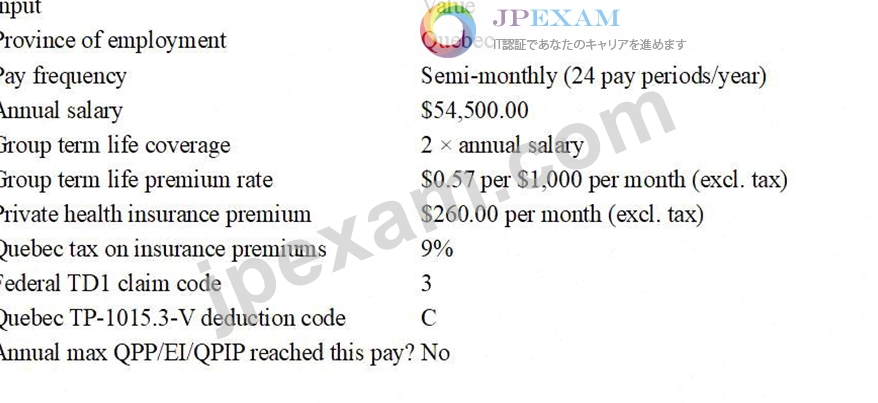
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases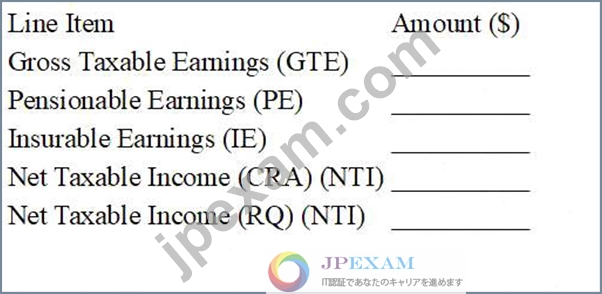
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
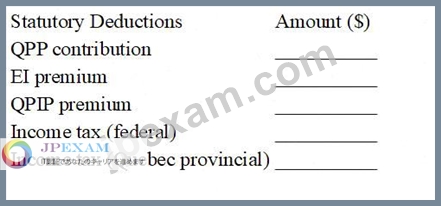
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
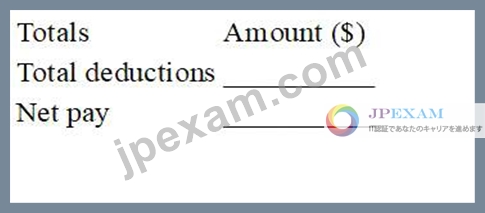
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
正解:
解説:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
質問 # 35
......
National Payroll Institute証明書を取得することは、あなたのキャリアにおける地位を高める素晴らしく迅速な方法です。 PF1試験に合格するというこの目標を達成するには、外部の支援が必要です。弊社が市場で最も人気のあるベンダーであるため、このリンクをクリックすると幸運です。私たちはこのキャリアに10年以上携わっており、PF1試験問題では、夢のNational Payroll Institute認定を得るための支援を受けるだけでなく、オンラインで一流のサービスを楽しむことができます。
PF1最新テスト: https://www.jpexam.com/PF1_exam.html
P.S. JpexamがGoogle Driveで共有している無料かつ新しいPF1ダンプ:https://drive.google.com/open?id=1Mc_wg4-tbIs91McWco3t1vldYf_bEAPk