Aufgrund der großen Übereinstimmung mit den echten Prüfungsfragen-und Antworten können wir Ihnen 100%-Pass-Garantie versprechen. Wir aktualisieren jeden Tag nach den Informationen von Prüfungsabsolventen oder Mitarbeitern von dem Testcenter unsere Prüfungsfragen und Antworten zu National Payroll Institute PF1 (Payroll Fundamentals 1Exam). Wir extrahieren jeden Tag die Informationen der tatsächlichen Prüfungen und integrieren in unsere Produkte.
| Section | Objectives |
|---|---|
| Topic 1: Earnings, Deductions, and Taxation | - Types of earnings
|
| Topic 2: Payroll Fundamentals and Compliance Framework | - Payroll system overview in Canada
|
| Topic 3: Payroll Records and Compliance Reporting | - Recordkeeping requirements
|
Sorgen Sie noch um die Vorbereitung der National Payroll Institute PF1 Prüfung? Aber solange Sie diesen Blog sehen, können Sie sich doch beruhigen, weil Sie der professionellste und der autoritativste Lieferant gefunden haben. Unsere Produkte haben viele Angestellten geholfen, die in IT-Firmen arbeiten, die National Payroll Institute PF1 Zertifizierungsprüfung zu bestehen. Die Gründe sind einfach. Da unsere Prüfungsunterlagen sind am neusten und am umfassendsten! Außerdem bieten wir einjährige kostenlose Aktualisierung nach Ihrem Kauf der Prüfungsunterlagen der National Payroll Institute PF1 . Keine Sorge bei der Vorbereitung!
22. Frage
An employee who lives in Ontario and reports to work at a permanent establishment of the employer in Quebec will have income tax deducted based on which province?
Antwort: A
Begründung:
For payroll deductions, the key concept is the employee's province of employment (POE)-not where they live. The CRA states that the POE is determined primarily by the employer's establishment where the employee "reports for work." If an employee reports for work at an employer's establishment located in Quebec, then the POE is Quebec, even if the employee's province of residence is Ontario.
This matters because Quebec has distinct payroll requirements. The CRA notes that when the POE is Quebec, employers must apply Quebec-based payroll rules, including deducting Quebec Pension Plan (QPP) contributions instead of CPP, and deducting Quebec parental insurance plan (QPIP) premiums, along with Quebec provincial income tax withholding.
In practice, payroll must set up the employee using Quebec as the POE and ensure stakeholders (HR, finance, the employee) understand why deductions may differ from Ontario residents working in Ontario. Any over
/under-withholding due to POE vs. residence is typically reconciled when the employee files their personal tax return.
23. Frage
Alyssa is a member of her employer's Defined Contribution Pension Plan. The plan defines the contribution as 3% of the employee's pensionable earnings, with the employer matching the employee's contribution.
Alyssa's pensionable earnings are $3,400.00 per month. Calculate the total payment to be remitted to Alyssa's Defined Contribution Pension Plan each month.
Antwort:
Begründung:
$204.00 per month
Explanation:
In a Defined Contribution (DC) pension plan, contributions are calculated as a set percentage of the employee' s pensionable earnings, and the total remittance is usually the sum of the employee deduction plus the employer's matching contribution, based on the plan text. Here, the plan states the employee contributes 3% of pensionable earnings, and the employer matches the employee contribution.
Step 1: Calculate the employee's pension contribution:
3% × $3,400.00 = 0.03 × 3,400.00 = $102.00.
Step 2: Calculate the employer match:
Because the employer matches the employee contribution, the employer contributes $102.00 as well.
Step 3: Total remittance to the plan:
$102.00 (employee) + $102.00 (employer) = $204.00 each month.
From a payroll processing perspective, the employee amount is withheld from gross pay as a payroll deduction according to plan rules, while the employer match is recorded as an employer expense. Payroll remits both amounts to the plan administrator following the plan's remittance schedule, and should reconcile pensionable earnings and contributions to ensure accuracy and compliance with plan terms.
24. Frage
The amount of notice the employer must give an employee depends on:
Antwort: C
Begründung:
Termination notice requirements come from the employment standards legislation that applies to the workplace, which is tied to the jurisdiction where the employee works (province/territory), unless the workplace is federally regulated. The Government of Canada explicitly directs employers and employees to consult the employment standards for the province or territory of work if they are not in a federally regulated industry.
Within a given jurisdiction, the minimum notice (or pay in lieu) is typically based on the employee's length of continuous employment/service. For example, under the Canada Labour Code (federally regulated workplaces), required notice increases with service (and can be replaced with wages in lieu), showing service length is a core driver of notice entitlements.
That's why "where they live" is not the deciding factor for notice rules: the governing employment standards are based on the jurisdiction of employment (where the work is performed / the employment is regulated), and the employee's length of service under that jurisdiction's rules.
25. Frage
National Hardware, an Ontario organization, will be terminating the employment of Emilie St. Germain on October 28, 2019, the last day of the pay period. Emilie started with National Hardware on September 19,
2007. Complete the paper Record of Employment (ROE) for Emilie based on the information provided in the following chart.
Note: Vacationable earnings already include the pay in lieu of notice.
All dates must be entered in the format DDMMYYYY.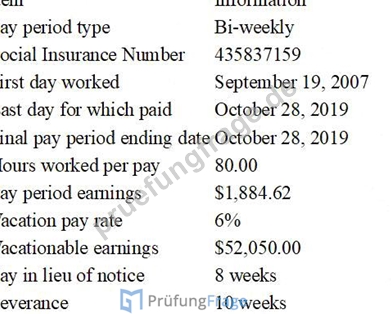
Paper ROE (Form Reference)
Complete the following paper ROE blocks for Emilie:
Block 6 - Pay period type
Block 8 - Social Insurance Number
Block 10 - First day worked
Block 11 - Last day for which paid
Block 12 - Final pay period ending date
Block 15A - Total insurable hours
Block 15B - Total insurable earnings
Block 17A - Vacation pay
Block 17C - Other monies (Pay in lieu of notice)
Block 17C - Other monies (Severance)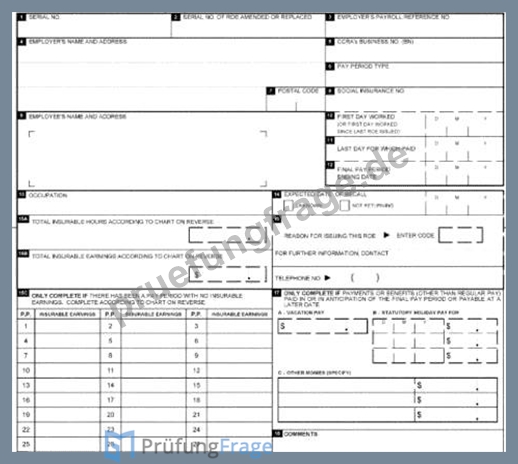
Step 1 - Complete Block 6
Enter the pay period type for Emilie.
Step 2 - Complete Block 8
Enter Emilie's Social Insurance Number.
Step 3 - Complete Block 10
Enter Emilie's first day worked in DDMMYYYY format.
Step 4 - Complete Block 11
Enter Emilie's last day for which paid in DDMMYYYY format.
Step 5 - Complete Block 12
Enter the final pay period ending date in DDMMYYYY format.
Step 6 - Complete Block 15A
Calculate and enter total insurable hours.
Given:
Hours worked per pay period = 80.00
Bi-weekly ROE pay period chart captures 27 pay periods
Step 7 - Complete Block 15B
Calculate and enter total insurable earnings.
Given:
Pay period earnings = $1,884.62
Bi-weekly ROE pay period chart captures 27 pay periods
Step 8 - Complete Block 17A
Calculate and enter vacation pay.
Given:
Vacation pay rate = 6%
Vacationable earnings = $52,050.00
(already includes pay in lieu of notice)
Step 9 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Pay in lieu of notice.
Given:
Pay in lieu of notice = 8 weeks
Use weekly earnings derived from the bi-weekly pay period earnings.
Step 10 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Severance.
Given:
Severance = 10 weeks
Use the same weekly earnings used in Step 9.
Antwort:
Begründung:
See the Below Explanation for complete Solution.
Explanation:
Step 1 - Block 6
Bi-weekly
Step 2 - Block 8
435837159
Step 3 - Block 10
September 19, 2007 # 19092007
Step 4 - Block 11
October 28, 2019 # 28102019
Step 5 - Block 12
October 28, 2019 # 28102019
Step 6 - Block 15A (Total insurable hours)
80.00 × 27 = 2160
Block 15A = 2160
Step 7 - Block 15B (Total insurable earnings)
$1,884.62 × 27 = $50,884.74
Block 15B = 50,884.74
Step 8 - Block 17A (Vacation pay)
$52,050.00 × 6% = $3,123.00
Block 17A = 3,123.00
Step 9 - Block 17C (Pay in lieu of notice)
Weekly earnings = $1,884.62 ÷ 2 = $942.31
Pay in lieu = $942.31 × 8 = $7,538.48
Block 17C (Pay in lieu of notice) = 7,538.48
Step 10 - Block 17C (Severance)
Severance = $942.31 × 10 = $9,423.10
Block 17C (Severance) = 9,423.10
26. Frage
The employee-employer relationship is deemed to be severed when:
Antwort: B
Begründung:
In ROE administration, the key concept is whether the employment relationship is still "active" (that is, whether there is an ongoing expectation the employee will work again). Service Canada's ROE guidance ties ROE issuance to an interruption of earnings and specifically identifies situations where an employee is no longer on the employer's active employment list (for example, no expectation of future work) as a trigger for issuing an ROE.
Options A and B describe circumstances that can still align with an ongoing employment relationship. For example, employees may remain eligible for certain benefits after a last day worked, and a right to recall means the employer may still consider the employee attached to the workplace (often still "active" depending on the arrangement). In contrast, when there is no expectation of work to be performed, the relationship is effectively ended for ROE purposes, and the employer generally proceeds with separation reporting and ROE completion based on the interruption of earnings rules.
27. Frage
......
Das Zertifikat für die National Payroll Institute PF1 Zertifizierungsprüfung ist notwendig für die IT-Branche. Sorgen Sie noch darum? PrüfungFrage wird dieses Problem für Sie lösen. PrüfungFrage ist eine historische Webseite für die National Payroll Institute PF1 Zertifizierungsprüfung, wo es eine große Menge von Fragenkataloge dafür gibt. Nach langjährigen Bemühungen haben unsere Erfolgsquote von der National Payroll Institute PF1 Zertifizierungsprüfung 100% erreicht.
PF1 Fragenkatalog: https://www.pruefungfrage.de/PF1-dumps-deutsch.html