P.S.ShikenPASSがGoogle Driveで共有している無料の2026 CIPS L4M7ダンプ:https://drive.google.com/open?id=1D3kST4WgxNAAo5K1Ik-2oFacX_t-WfcX
ShikenPASSがもっと早くCIPSのL4M7認証試験に合格させるサイトで、CIPSのL4M7「CIPS Whole Life Asset Management」認証試験についての問題集が市場にどんどん湧いてきます。ShikenPASSを選択したら、成功をとりましょう。
| Section | Objectives |
|---|---|
| Topic 1: Understanding Asset Management | - Principles of whole life asset management
|
| Topic 2: Operation and Maintenance | - Asset performance and reliability
|
| Topic 3: Risk and Value Management | - Managing asset-related risk
|
| Topic 4: Asset Acquisition and Procurement | - Sourcing and procurement of assets
|
| Topic 5: Disposal and End-of-Life Management | - Asset disposal strategies
|
CIPS L4M7試験参考書に疑問を持たれば、CIPS会社のウエブサイトから無料でL4M7試験のためのデモをダウンロードできます。L4M7試験参考書の高品質でL4M7試験の受験者は弊社と長期的な協力関係を築いています。L4M7試験参考書はお客様の試験のために最も役に立つ商品だとも言えます。
質問 # 216
U-shape flow layout can utilise handling equipment if the high demands items locate adjacent to shipping docks. Is this statement true?
正解:A
解説:
A 'U' flow occurs when the goods receipt and dispatch functions are located at the same end of a warehouse building.
Products flow in at receiving, move in to storage in the back of the warehouse, and then to shipping, which is located at the adjacent to receiving on the same side of the building.
Items with higher throughput level are located closer to the loading bays. An example of a 'U' flow design can be seen in the diagram below.
Diagram Description automatically generated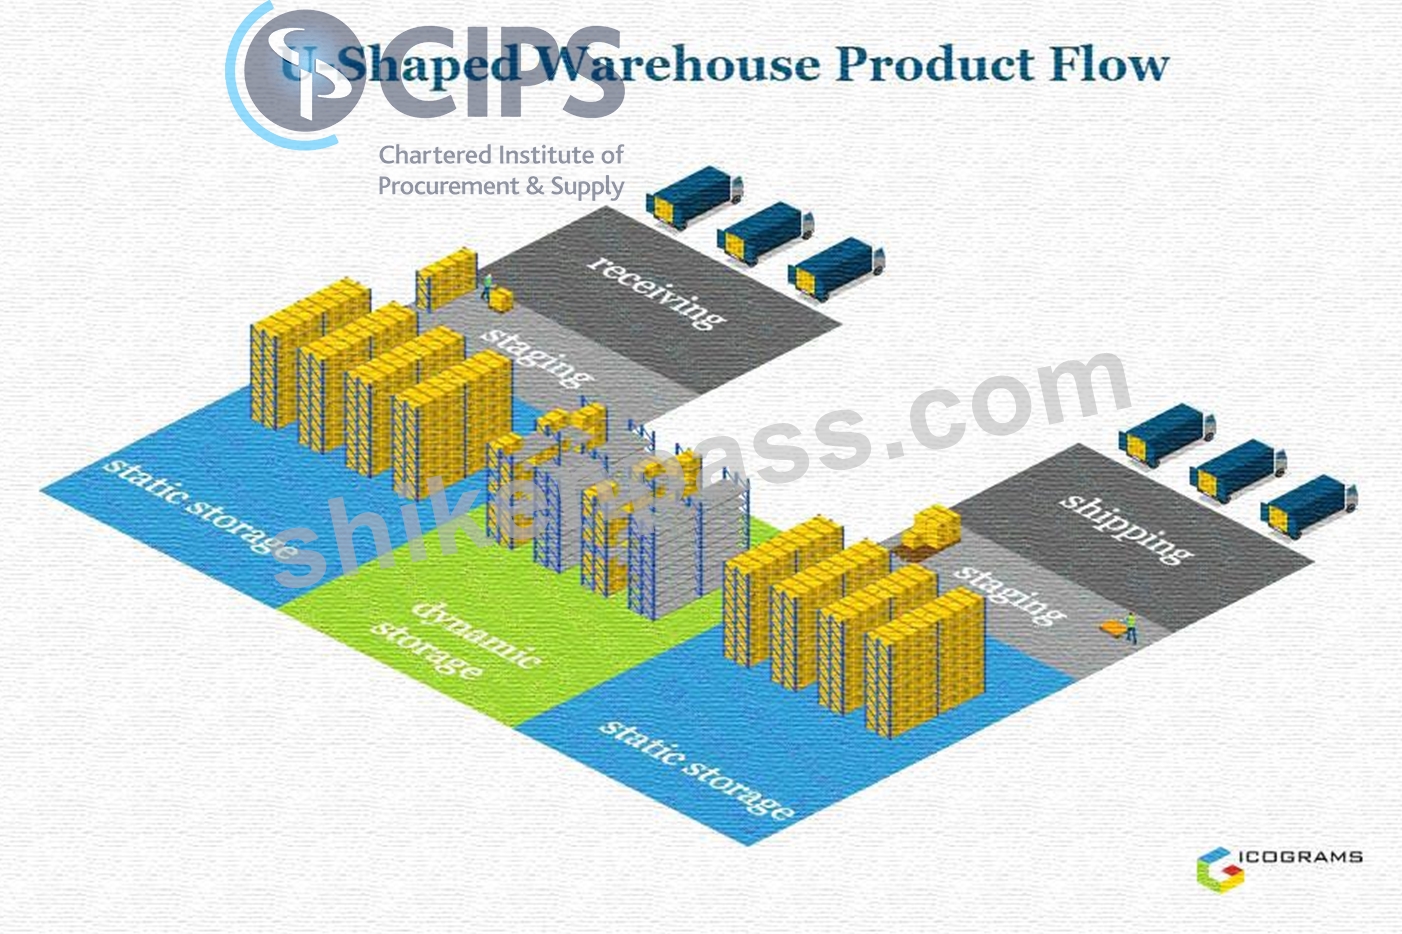
Advantages of 'U' Flow
- Excellent utilization of dock resources because the receiving and shipping processes can share dock doors
- Facilitating cross-docking because the receiving and shipping docks are adjacent to one another and may be co-mingled
- Excellent lift truck utilization because put away and retrieval trips are easily combined and be-cause the storage locations closest to the receiving and shipping docks are natural locations to house fast moving items
- Yields excellent security because there is a single side of the building used for entry and exit
質問 # 217
Which of the following are the different types of inventory that a manufacturing company usually has?
1. Work in progress
2. Economic order quantity
3. Raw materials
4. Finished goods
正解:D
解説:
The normal breakdown in a manufacturing organisation would be raw materials, components, work in progress and finished goods.
Following are the different types of inventory: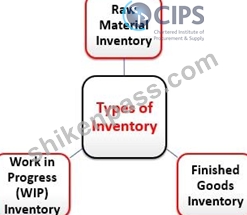
Raw materials are the basic materials that a manufacturing company buys from its suppliers, and that is used by the former to convert them into the final products by applying a set of manufacturing processes. For example, aluminum scrap is the raw material for a company that produces aluminum ingots. Flour is the raw material for a company that produces bread or pizza. Similarly, metal parts and ingots are the raw materials bought by a company that manufactures cars, and crude oil is the raw material for an oil refinery.
Work in progress inventory can also be called semi-finished goods. They are the raw materials that have been taken out of the raw materials store and are now undergoing the process of their conversion into the final products. These are the partly processed raw materials lying on the production floor. And they have also not reached the stage where they have been converted into the final product.
Finished goods are indeed the final products obtained after the application of the manufacturing processes on the raw materials and the semi-finished goods discussed above in the article. They are saleable, and their sale contributes fully to the revenue from the core operations of the company.
Reference:
- Types of Inventory
- CIPS study guide page 82-83
LO 2, AC 2.1
質問 # 218
Which of the following supply chain activities can distort data for forecasting inventory?
1. Sales promotions by the marketing department
2. Over-ordering by customers
3. Increase in stock movements in the warehouse
4. Volatile logistic and container prices
正解:D
質問 # 219
Which of the following are most likely to be direct benefits of applying RFID technology? Select TWO that apply
正解:A、D
解説:
RFID tags are the small devices that can be embedded in labels or attached to tags which work with radio transmitters and/or receivers to identify themselves.
RFID tags can be used to do the following:
- Track individual items
- Track boxes of products, cages of products and pallets
- Track containers with multiple loads
- Locate equipment within a building
- Trigger alarms should equipment or stock be removed without authorisation.
RFID devices have a very small integrated circuit incorporating a small memory capability - many are smaller than 2mm square and 2mm thick. Despite its size, many can hold 2000 characters of data.
RFID operating rage depends on the radio frequency used, receiver capability and the environment. Some tags are only readable from under 1m, others can have a 100m range.
RFID tags and labels are very specific to the type of material and size of your assets. For example, metal will deactivate the RFID antenna and the tag will not transmit at all. Using RFID on metal requires a special type of tag with an RFID block to prevent interference with the antenna. Liquid products can also affect the reliability of the RFID signal. To use RFID tags in specific environ-ments, some technologies are needed to support them.
Reference: CIPS study guide page 49-50
LO 1, AC 1.2
質問 # 220
A company has obsolete inventories and it must write off these inventories. How does writing off inventories impact on the company's financial statements?
1. Stock increases
2. Stock decreases
3. Profit increases
4. Profit decreases
正解:D
解説:
An inventory write-off is a process of removing from the general ledger any inventory that has no value.
Using the direct write-off method, a business will record a credit to the inventory asset account and a debit to the expense account. For example, say a company with $100,000 worth of inventory decides to write off $10,000 in inventory at the end of the year. First, the firm will credit the inventory account with the value of the write-off to reduce the balance. The value of the gross inventory will be reduced as such: $100,000 - $10,000 = $90,000. Next, the inventory write-off expense account will be increased with a debit to reflect the loss.
The expense account is reflected in the income statement, reducing the firm's net income and thus its retained earnings. A decrease in retained earnings translates into a corresponding decrease in the shareholders' equity section of the balance sheet.
If the inventory write-off is immaterial, a business will often charge the inventory write-off to the cost of goods sold (COGS) account. The problem with charging the amount to the COGS account is that it distorts the gross margin of the business, as there is no corresponding revenue entered for the sale of the product. Most inventory write-offs are small, annual expenses. A large inventory write-off (such as one caused by a warehouse fire) may be categorized as a non-recurring loss.
Reference:
- CIPS study guide page 86-90
- Inventory Write-Off
LO 2, AC 2.1
質問 # 221
......
L4M7試験に問題がある場合は、無料のデモを検討してください。弊社の最新のL4M7試験トレントは、この業界では完璧な模範であり、さまざまな程度の試験受験者向けの明確なコンテンツに満ちています。最新のL4M7試験トレントの結果は驚くほど驚くべきもので、試験受験者の98%以上が目標を無事に達成しました。また、L4M7テストダンプにより、あらゆる種類の教材の精度が非常に高いことが保証されました。
L4M7関連合格問題: https://www.shikenpass.com/L4M7-shiken.html
無料でクラウドストレージから最新のShikenPASS L4M7 PDFダンプをダウンロードする:https://drive.google.com/open?id=1D3kST4WgxNAAo5K1Ik-2oFacX_t-WfcX