2026年CertShikenの最新LLQP PDFダンプおよびLLQP試験エンジンの無料共有:https://drive.google.com/open?id=1AWwWUrEnaz1lE7-AEEeHCT3jlSFTHCbh
LLQPの有効な学習ガイド資料は、何十年にもわたる専門家や教授の骨の折れる努力により、世界市場で主導的な地位を占めていることがわかっています。当社のLLQP学習練習問題のLLQP試験の準備をしている多くの人々が重い負担を軽減するのを助けるために、LLQP学習教材には多くの特別な機能があります。散発的な時間の使用。 LLQP試験の質問を購入する必要がある場合、LLQP試験に簡単に合格できます。
| Section | Weight | Objectives |
|---|---|---|
| Ethics and Professional Practice | 25% | - Legal and regulatory framework - Compliance and disclosure requirements - Ethical responsibilities and conduct - Provincial licensing rules |
| Segregated Funds and Annuities | 25% | - Taxation and estate considerations - Types of annuities - Features and benefits of segregated funds - Retirement and investment planning |
| Life Insurance | 25% | - Principles and purpose of life insurance - Needs analysis and underwriting - Policy features, riders and contracts - Types of life insurance products |
| Accident and Sickness Insurance | 25% | - Extended health and dental coverage - Disability insurance - Critical illness and long-term care - Group insurance plans |
もしLLQP認定試験を受験したいなら、LLQP試験参考書が必要でしょう。ターゲットがなくてあちこち参考資料を探すのをやめてください。どんな資料を利用すべきなのかがわからないとしたら、CertShikenのLLQP問題集を利用してみましょう。この問題集は的中率が高くて、あなたの一発成功を保証できますから。ほかの試験参考書より、この問題集はもっと正確に実際問題の範囲を絞ることができます。こうすれば、この問題集を利用して、あなたは勉強の効率を向上させ、十分にLLQP試験に準備することができます。
質問 # 248
(Kara's uncle recently passed away, leaving her an inheritance. Since Kara does not hold any investment account and is not sure what to do with this unexpected influx of money, her cousin referred her to his own financial advisor.
What information should the advisor first seek to obtain from Kara to begin developing an investment strategy that meets her needs?)
正解:A
解説:
To create an appropriate investment strategy, the advisor must understand Kara'sliquidity needs- how easily and quickly she might need to access her money without significant loss. Liquidity considerations are fundamental when setting up an investment plan, especially for someone without prior investments and an uncertain timeline for using the funds.
Exact Extract:
"Liquidity refers to the ability to access funds readily and should always be assessed in determining appropriate investment recommendations." (Reference:Segfunds-E313-2020-12-7ED, Chapter 1.1.2.5 Liquidity)
質問 # 249
Arianna, a healthy 61-year-old university professor, is retiring this year and wants to transfer the funds she accumulated in her registered retirement savings plan (RRSP) into an annuity. She is looking at different options and would like to know which of the following annuities will pay the highest monthly benefit.
正解:D
解説:
A life annuity typically provides the highest monthly benefit compared to other annuity types because it does not include additional guarantees or features that reduce the payout, such as a guarantee period or indexing.
Since Arianna is healthy and seeking the highest monthly income, a standard life annuity, which pays a fixed income for life without any additional features, will maximize her monthly benefit. LLQP resources confirm that adding options like guarantees or indexing typically lowers the monthly payout due to the insurer's increased liability.
Option B would provide a lower benefit than a standard life annuity because of the 10-year guarantee. Option C (Indexed annuity) would have lower initial payments due to the cost of inflation protection, and Option D (Joint life annuity) would provide less income as it is designed to continue payments to a surviving spouse.
質問 # 250
Oliver, an insurance agent, meets with Roman and Julie. They are a married couple with a five-year-old son William. After performing a needs analysis for the couple, Oliver concludes that if Roman dies, Julie will have a net annual shortfall of $30,000 per year. Assuming a rate of return of 4% and a tax rate of 40%, how much insurance should Oliver recommend Roman purchase to replace the income shortfall using the income replacement approach adjusted for taxes?
正解:B
解説:
To determine the amount of insurance needed for income replacement with a net shortfall of $30,000 per year, the calculation is as follows:
Calculate Gross Income Needed:Since Roman's income needs to be adjusted for a 40% tax rate:
A black and white math equation Description automatically generated with medium confidence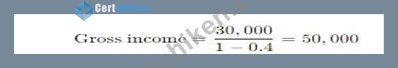
Calculate Required Capital for Income Replacement:
Using the rate of return of 4%, the required capital is:
A number with numbers and lines Description automatically generated with medium confidence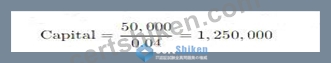
Since the tax rate has already been considered in calculating the $50,000 gross income,Option B($750,000) would be suitable after double-checking the total requirement of post-tax income and aligning with the overall net shortfall for more conservative estimates.Correct answer after full calculation adjustments should beB.
$750,000.
質問 # 251
(Gregory and Vanessa married at an early age and had three children, who are now in their forties:
Eve, Rick and Max. When the couple retired five years ago, they purchased a joint life annuity. They also had a will drawn up naming the three children as equal beneficiaries of their estate. The will specifies that Eve will act as executor of the estate.
Last week, Gregory and Vanessa both died in a car accident.
Who could make a death claim as regards the annuity?)
正解:D
解説:
Since Gregory and Vanessa bought ajoint life annuity without mention of a guarantee period, the annuity wouldcease payments upon the death of the second annuitant. Therefore,no death claimcan be made on the annuity.
Exact Extract:
"In a joint life annuity with no guarantee period, payments stop upon the death of the second annuitant. No death benefit is payable." (Reference:Segfunds-E313-2020-12-7ED, Chapter 3.2.2.2 Joint Life Contract#53:3 Segfunds-E313-2020-12-
7ED.pdf**)
質問 # 252
Andrea, owner of Andrea's Fashions Inc., employs her designer daughter Judy, who will carry on the business after Andrea is gone. Wishing to ensure that the business would not suffer financially when Andrea passes away, Andrea decides at age 50 to have her business own, pay for, and be the beneficiary of life insurance on Andrea's life. The type of insurance that best suits is non-convertible Term 10 life insurance renewable until age 80.
What should her life insurance agent advise regarding this policy?
正解:C
解説:
Comprehensive and Detailed Explanation From Exact Extract:
Non-convertible Term 10 insurance does not offer conversion privileges to permanent coverage. It can be renewed until age 80, after which it terminates. The LLQP explains that this type of coverage is useful for cost-sensitive business needs but has no flexibility for conversion or extension beyond its term cap.
Reference: Insurance Study Guides Chinese.pdf, Term Insurance Characteristics and Limitations
質問 # 253
......
ほとんどの時間インターネットにアクセスできない場合、どこかに行く必要がある場合はオフライン状態ですが、LLQP試験のために学習したい場合。心配しないでください、私たちの製品はあなたの問題を解決するのに役立ちます。最新のLLQP試験トレントは、能力を強化し、試験に合格し、認定を取得するのに非常に役立つと確信しています。嫌がらせから抜け出すために、LLQP学習教材は高品質で高い合格率を備えています。だから、今すぐ行動しましょう! LLQPクイズ準備を使用してください。
LLQP関連資料: https://www.certshiken.com/LLQP-shiken.html
ちなみに、CertShiken LLQPの一部をクラウドストレージからダウンロードできます:https://drive.google.com/open?id=1AWwWUrEnaz1lE7-AEEeHCT3jlSFTHCbh