P.S. Free 2026 National Payroll Institute PF1 dumps are available on Google Drive shared by ExamCost: https://drive.google.com/open?id=14NmY4eIe13vAokzeB2OwUeez-qTa5D8p
If you want the PF1 certification to change your life and make it better, what are you waiting for? You should act quickly and make use of spare time of study or work to obtain a PF1 certification and master one more skill. With the help of our PF1 Exam Materials, you will find all of these desires are not dreams anymore. With the high pass rate as 98% to 100%, our PF1 learning questions can help you get your certification with ease.
| Section | Objectives |
|---|---|
| Topic 1: Non-Statutory Deductions | - Voluntary deductions
|
| Topic 2: Provincial Remittances | - Provincial payroll requirements
|
| Topic 3: Termination of Employment | - Termination processing
|
| Topic 4: Commission Payments | - Commission payroll processing
|
| Topic 5: Federal Remittances | - Government remittance obligations
|
| Topic 6: Year-End Processing | - Federal and provincial year-end reporting
|
| Topic 7: New Employee Information | - Employee setup and documentation
|
| Topic 8: Employment Income – Allowances, Expenses and Benefits | - Taxable and non-taxable benefits
|
| Topic 9: Workers’ Compensation | - Workers compensation administration
|
| Topic 10: Non-Regular Payments | - Special payroll payments
|
| Topic 11: Employment Income – Regular Earnings | - Regular payroll calculations
|
| Topic 12: Record of Employment | - ROE processing
|
| Topic 13: Payroll Accounting | - Payroll accounting practices
|
As old saying goes, no pains, no gains. You must depend on yourself to acquire what you want. No one can substitute you with the process. Of course, life has shortcut, which can ensure you have a bright future. Our PF1 training quiz will become your new hope. As the most popular exam provider in the market, we are warmly praised and we can receive thousands of the grateful feedbacks from our worthy customers on PF1 Exam Questions. please trust and buy our PF1 study materials!
NEW QUESTION # 51
National Hardware, an Ontario organization, will be terminating the employment of Emilie St. Germain on October 28, 2019, the last day of the pay period. Emilie started with National Hardware on September 19,
2007. Complete the paper Record of Employment (ROE) for Emilie based on the information provided in the following chart.
Note: Vacationable earnings already include the pay in lieu of notice.
All dates must be entered in the format DDMMYYYY.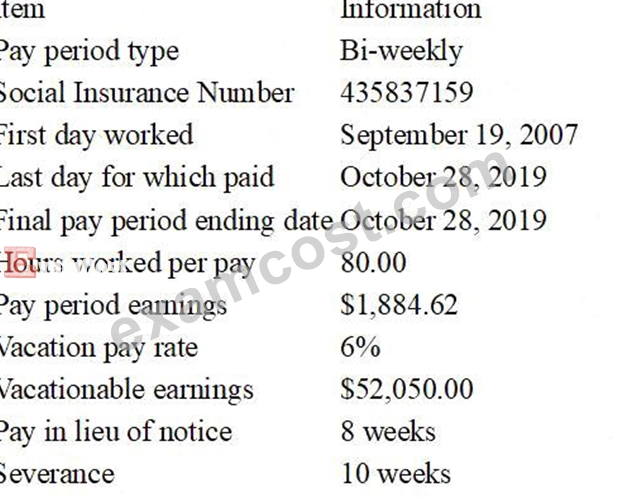
Paper ROE (Form Reference)
Complete the following paper ROE blocks for Emilie:
Block 6 - Pay period type
Block 8 - Social Insurance Number
Block 10 - First day worked
Block 11 - Last day for which paid
Block 12 - Final pay period ending date
Block 15A - Total insurable hours
Block 15B - Total insurable earnings
Block 17A - Vacation pay
Block 17C - Other monies (Pay in lieu of notice)
Block 17C - Other monies (Severance)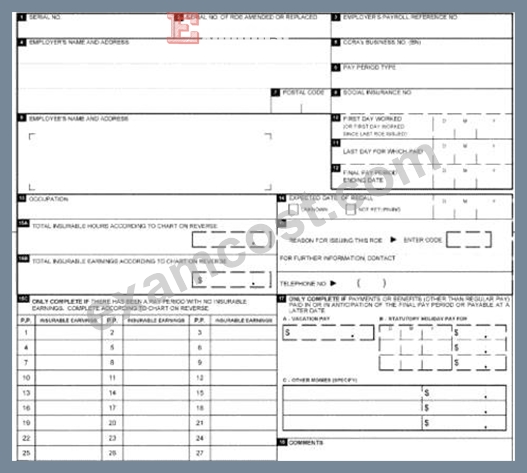
Step 1 - Complete Block 6
Enter the pay period type for Emilie.
Step 2 - Complete Block 8
Enter Emilie's Social Insurance Number.
Step 3 - Complete Block 10
Enter Emilie's first day worked in DDMMYYYY format.
Step 4 - Complete Block 11
Enter Emilie's last day for which paid in DDMMYYYY format.
Step 5 - Complete Block 12
Enter the final pay period ending date in DDMMYYYY format.
Step 6 - Complete Block 15A
Calculate and enter total insurable hours.
Given:
Hours worked per pay period = 80.00
Bi-weekly ROE pay period chart captures 27 pay periods
Step 7 - Complete Block 15B
Calculate and enter total insurable earnings.
Given:
Pay period earnings = $1,884.62
Bi-weekly ROE pay period chart captures 27 pay periods
Step 8 - Complete Block 17A
Calculate and enter vacation pay.
Given:
Vacation pay rate = 6%
Vacationable earnings = $52,050.00
(already includes pay in lieu of notice)
Step 9 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Pay in lieu of notice.
Given:
Pay in lieu of notice = 8 weeks
Use weekly earnings derived from the bi-weekly pay period earnings.
Step 10 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Severance.
Given:
Severance = 10 weeks
Use the same weekly earnings used in Step 9.
Answer:
Explanation:
See the Below Explanation for complete Solution.
Explanation:
Step 1 - Block 6
Bi-weekly
Step 2 - Block 8
435837159
Step 3 - Block 10
September 19, 2007 # 19092007
Step 4 - Block 11
October 28, 2019 # 28102019
Step 5 - Block 12
October 28, 2019 # 28102019
Step 6 - Block 15A (Total insurable hours)
80.00 × 27 = 2160
Block 15A = 2160
Step 7 - Block 15B (Total insurable earnings)
$1,884.62 × 27 = $50,884.74
Block 15B = 50,884.74
Step 8 - Block 17A (Vacation pay)
$52,050.00 × 6% = $3,123.00
Block 17A = 3,123.00
Step 9 - Block 17C (Pay in lieu of notice)
Weekly earnings = $1,884.62 ÷ 2 = $942.31
Pay in lieu = $942.31 × 8 = $7,538.48
Block 17C (Pay in lieu of notice) = 7,538.48
Step 10 - Block 17C (Severance)
Severance = $942.31 × 10 = $9,423.10
Block 17C (Severance) = 9,423.10
NEW QUESTION # 52
How many pay periods will be used to calculate insurable earnings inBlock 15Bon the Record of Employment if the employee is paidweekly?
Answer: C
Explanation:
For apaper ROE, Service Canada's ROE guidance uses a set number ofmost recent consecutive pay periods to support the reporting of insurable earnings. InBlock 15C(insurable earnings by pay period), the paper ROE provides27 fields, which allows reporting up to27 weekly pay periods(or fewer if the employee worked fewer periods).
Block15Bis thetotal insurable earningsfor the applicable number of consecutive pay periods, and for a weekly payroll this aligns with the same maximum count used on the paper ROE earnings grid-27periods.
Practically, this means payroll totals the employee's insurable earnings for thelast 27 consecutive weekly pay periodsleading up to the interruption of earnings (or the full period of employment if shorter). Using the correct number of pay periods ensures Service Canada has the right earnings history to adjudicate EI benefits accurately and reduces ROE processing issues.
NEW QUESTION # 53
What information is required to calculate thestandby charge, thereduced standby charge, and theoperating cost benefitfor a company-owned automobile?
Answer: A
Explanation:
CRA's automobile benefit calculations require multiple data points because there are usuallytwo components thestandby charge(vehicle availability) and theoperating expense benefit(personal driving where the employer pays operating costs). CRA's guidance on employer-provided automobiles explains that standby charge calculations use the automobile'scost (capital cost) including applicable taxesand the time the vehicle wasavailableto the employee, while the reduced standby charge and operating benefit depend on kilometres drivenand the split betweenbusiness and personal use.
To determine whether areduced standby chargeapplies, you need availability plusbusiness-use requirements(which are evidenced through total/business kilometres). To calculate the operating expense benefit, you needpersonal kilometres(often derived from total kilometres minus business kilometres) or detailed personal km directly.
Therefore, the complete and correct set of required inputs is:capital cost (with sales tax), availability, total kilometres, business kilometres, and personal kilometres-which is optionD.
NEW QUESTION # 54
By the authority of which Act can the Canada Revenue Agency garnish the wages of an employee who has failed to pay Employment Insurance premiums, Canada Pension Plan contributions, or income tax deductions?
Answer: B
Explanation:
The CRA's wage garnishment tool is commonly issued as a Requirement to Pay (RTP) (and related instruments such as ERTP/DTP), which directs a third party (often the employer) to redirect amounts that would otherwise be paid to the employee, and send them to the government instead. CRA guidance explains that when an employee owes money, the CRA can send the employer a requirement to pay notice, and the employer must remit the amounts as instructed (or the employer can become liable).
The legal authority for the CRA to issue a Requirement to Pay is found in the Income Tax Act, including section 224, which sets out the mechanism and consequences for non-compliance.
In payroll operations, this is a communication-and-compliance issue: payroll must correctly interpret the notice, apply the withholding/remittance as directed, and communicate impacts to internal stakeholders (HR
/finance) and, where appropriate, the affected employee-while ensuring the remittance is made exactly as the CRA notice requires.
NEW QUESTION # 55
Expense reimbursements are:
Answer: D
Explanation:
An expense reimbursement is paid to repay an employee for actual business expenses the employee incurred while performing their job (for example, meals while travelling on business, supplies purchased for work, etc.). CRA's taxable benefits guidance distinguishes reimbursements from allowances: an allowance is usually a predetermined amount paid without the employee having to support the expense with receipts, while a reimbursement is tied to actual costs.
That distinction matters because reimbursements are generally not compensation for work performed (so they are not "earnings"), and they are not "benefits" in the sense of a good or service provided by the employer (though CRA notes that benefits can include reimbursements of personal expenses-so payroll must still ensure the reimbursement is for business use and properly supported).
Option A correctly describes reimbursements. Option B is typically an allowance (for example, a vehicle allowance for using personal property). Option C describes earnings (wages/salary). Option D describes benefits (value of something provided or paid for on the employee's behalf).
NEW QUESTION # 56
......
Our PF1 exam questions have three versions: the PDF, Software and APP online. Also, there will have no extra restrictions to your learning because different versions have different merits. All in all, you will not be forced to buy all versions of our PF1 Study Materials. You have the final right to select. Please consider our PF1 learning quiz carefully and you will get a beautiful future with its help.
Latest PF1 Test Testking: https://www.examcost.com/PF1-practice-exam.html
P.S. Free & New PF1 dumps are available on Google Drive shared by ExamCost: https://drive.google.com/open?id=14NmY4eIe13vAokzeB2OwUeez-qTa5D8p