Before buying the Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) exam questions, ActualVCE also offers a CSI AFP-Exam-1 exam questions demo of the Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) exam. You can test out the CSI AFP-Exam-1 pdf questions product with this AFP-Exam-1 questions demo before purchasing the full package. The CSI AFP-Exam-1 PDF Questions demo provides an overview of the Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) exam study product and how it can assist you in passing the Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) exam.
| Section | Weight | Objectives |
|---|---|---|
| Technical Competencies | 84% | - Risk Management and Insurance - Tax Planning - Retirement Planning - Estate Planning - Asset and Liability Management - Investment Planning |
| Enabling Competencies | 16% | - Client Relationship and Practice Management - Professional Conduct and Regulatory Compliance |
>> AFP-Exam-1 New Real Exam <<
ActualVCE's AFP-Exam-1 exam training materials is more accurate and easier to understand, more authoritative than other AFP-Exam-1 exam dumps provided by any other website. After choose ActualVCE, you won't regret. If you are still worried, you can first try AFP-Exam-1 Dumps Free demo and answers on probation. After you buy ActualVCE's AFP-Exam-1 exam training materials, we guarantee you will pass AFP-Exam-1 test with 100%.
NEW QUESTION # 23
Edward is risk averse and has limited investment knowledge. He will only purchase 100% guaranteed products insured by the CDIC. Edward is meeting with his financial planner, Marissa, for the third time this year about rates, and starts the meeting by criticizing her employer for paying such low returns on GICs.
Edward says he is considering taking his business elsewhere. How should Marissa respond to Edward's comments?
Answer: B
Explanation:
Marissa should respond with empathy and accuracy. Edward is risk averse, has limited investment knowledge, and will only purchase CDIC-insured guaranteed products. The correct response is to acknowledge his frustration, explain that the displayed rates are the best she can offer, and allow him to compare alternatives without pressure. Matching competitor rates may be outside her authority and could misrepresent the firm's pricing. Telling him to increase risk tolerance to obtain a better return ignores his stated constraints and may lead to unsuitable advice. Claiming her rate is the highest in the market would be inappropriate unless she can substantiate it, and even then the statement may become stale quickly. In AFP client management, the planner preserves trust by respecting the client's risk profile, communicating honestly, and avoiding product pressure. Study Guide focus: client communication, risk tolerance, guaranteed products, suitability, and relationship management. This response protects suitability because Edward's product universe is defined by capital guarantee and deposit insurance.
NEW QUESTION # 24
Leena and Harry are married and hold RRSPs with a value exceeding $500,000. They are concerned about their final tax liability and want to cover the taxes after they have both died. What would their financial planner recommend them to implement in order for the couple to achieve the objective?
Answer: B
Explanation:
A joint last-to-die permanent life insurance policy is designed for a tax liability that arises after both spouses have died. Leena and Harry are concerned about the final tax exposure on large RRSP balances. If one spouse dies first and the surviving spouse is the beneficiary or successor annuitant, RRSP/RRIF amounts may generally roll to the survivor on a tax-deferred basis. The larger tax problem usually appears on the second death, when no spouse remains for rollover and the registered assets are included in income. Last-to-die coverage pays at that point and can provide estate liquidity for taxes without forcing asset sales. A testamentary trust does not itself fund the tax bill. Updating beneficiaries to each other helps deferral but not the final liability. An inter vivos trust cannot simply receive RRSP assets without tax consequences. Study Guide focus: RRSP/RRIF death taxation, spousal rollover, permanent insurance, estate liquidity, and last-to- die planning.
NEW QUESTION # 25
Janet's non-registered account holds the funds listed in the following table: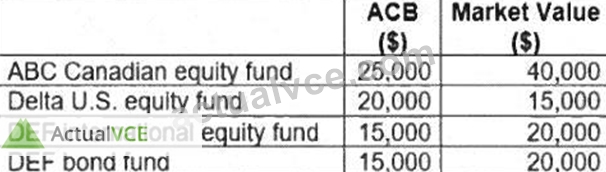
Assuming a marginal tax rate of 45%, what amount of tax payable will Janet incur if she redeems the account to fund the purchase of a new business?
Answer: B
Explanation:
Janet's taxable result comes from the net realized capital gain, not from the total market value redeemed. The ABC Canadian equity fund has a $15,000 gain, the Delta U.S. equity fund has a $5,000 loss, the DEF international equity fund has a $5,000 gain, and the DEF bond fund has a $5,000 gain. Net capital gains are therefore $20,000 after offsetting the Delta loss. Only one-half of the net capital gain is taxable under the standard capital gains inclusion treatment used in AFP-level calculations, producing a $10,000 taxable capital gain. At a 45% marginal tax rate, the tax payable is $4,500. Option A taxes the full net gain; option C and option D reflect incorrect inclusion or arithmetic assumptions. The purpose of the question is to test disposition analysis in a non-registered account and the sequence of gain/loss netting before applying the marginal rate. Study Guide focus: adjusted cost base, fair market value, capital gains inclusion, and non- registered tax planning.
NEW QUESTION # 26
In which life cycle stage would a financial planner identify his client to be if they have a high mortgage balance and an unstable or lower income, and are willing to take on investment risk because of their longer time horizon?
Answer: C
NEW QUESTION # 27
Suzy, age 45, is meeting with a financial planner as she has recently inherited $1.25 million from her late aunt. Suzy has poor spending habits and would like to review options that would safeguard and help her receive stable cash flows. She does not have a lot of experience investing and would like to avoid making day- to-day investment decisions. Which type of investment account is most appropriate for Suzy?
Answer: A
Explanation:
Suzy's facts point to income certainty and behavioural protection. She has inherited significant capital, admits poor spending habits, wants stable cash flow, lacks investment experience, and does not want day-to-day investment decisions. A straight life annuity converts a lump sum into predictable income for life, reducing the risk that she spends the inheritance too quickly or makes unsuitable investment decisions. A separately managed, multi-mandate managed, or discretionary fee-based account may delegate investment decisions, but those structures still expose her to market fluctuation and do not automatically impose a stable lifetime income discipline. The trade-off is that a straight life annuity may provide limited estate value and little liquidity after purchase, so the planner should consider whether only part of the inheritance should be annuitized. Among the options, however, the annuity best matches the stated need. Study Guide focus:
annuities, behavioural risk, retirement income products, capital preservation, and cash-flow certainty. The planner should reserve liquid capital separately if Suzy needs emergency funds or future discretionary purchases.
NEW QUESTION # 28
......
You may doubt about such an amazing data of our pass rate on our AFP-Exam-1 learning prep, which is unimaginable in this industry. But our AFP-Exam-1 exam questions have made it. You can imagine how much efforts we put into and how much we attach importance to the performance of our AFP-Exam-1 Study Guide. We use the 99% pass rate to prove that our AFP-Exam-1 practice materials have the power to help you go through the exam and achieve your dream.
Test AFP-Exam-1 Simulator Online: https://www.actualvce.com/CSI/AFP-Exam-1-valid-vce-dumps.html