BTW, DOWNLOAD part of TestKingFree PF1 dumps from Cloud Storage: https://drive.google.com/open?id=1yiUdjLl5t9zCiVsn8yD5nV--UPeprB0I
In the era of information explosion, people are more longing for knowledge, which bring up people with ability by changing their thirst for knowledge into initiative and "want me to learn" into "I want to learn". As a result thousands of people put a premium on obtaining PF1 certifications to prove their ability. With the difficulties and inconveniences existing for many groups of people like white-collar worker, getting a PF1 Certification may be draining. Therefore, choosing a proper PF1 study materials can pave the path for you which is also conductive to gain the certification efficiently.
| Section | Objectives |
|---|---|
| Year-End Processing | - Federal and provincial year-end reporting
|
| Record of Employment | - ROE processing
|
| Non-Statutory Deductions | - Voluntary deductions
|
| Non-Regular Payments | - Special payroll payments
|
| Commission Payments | - Commission payroll processing
|
| Workers’ Compensation | - Workers compensation administration
|
| Provincial Remittances | - Provincial payroll requirements
|
| Federal Remittances | - Government remittance obligations
|
| Termination of Employment | - Termination processing
|
| Payroll Accounting | - Payroll accounting practices
|
| Employment Income – Regular Earnings | - Regular payroll calculations
|
| New Employee Information | - Employee setup and documentation
|
| Employment Income – Allowances, Expenses and Benefits | - Taxable and non-taxable benefits
|
>> Examcollection PF1 Questions Answers <<
To keep up with the newest regulations of the PF1 exam, our experts keep their eyes focusing on it. Our PF1 exam torrent are updating according to the precise of the real exam. Our PF1 test prep to help you to conquer all difficulties you may encounter. Once you choose our PF1 Quiz torrent, we will send the new updates for one year long, which is new enough to deal with the exam for you and guide you through difficulties in your exam preparation.
NEW QUESTION # 52
Which of the following types of earnings are not considered income from employment?
Answer: C
Explanation:
Regular salary, vacation pay, and commissions are generally treated as income from employment because they are amounts paid for services performed during employment. In contrast, what many people call
"severance pay" is often classified by the CRA as a retiring allowance-an amount paid when or after an employee retires or loses their job, in recognition of long service or for the loss of employment.
This distinction matters in payroll because a retiring allowance has its own rules for withholding and potential RRSP/RPP transfer eligibility, and it is not treated the same way as normal employment income earned while actively employed. CRA technical guidance also draws lines between amounts that are employment income versus retiring allowance depending on the nature/timing of the payment.
So, among the options listed, severance pay (when it is a retiring allowance) is the one that is not considered income from employment in the way salary/vacation pay/commissions are.
NEW QUESTION # 53
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
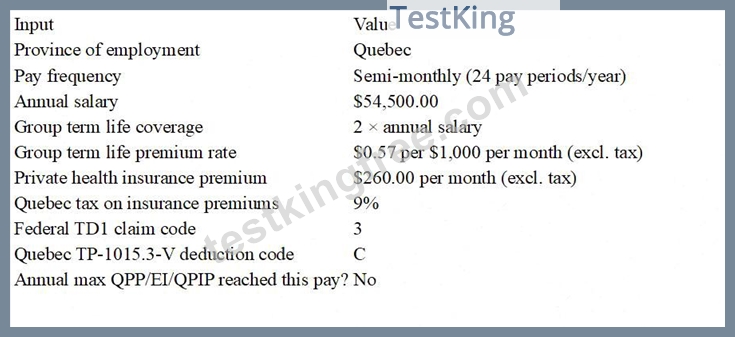
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases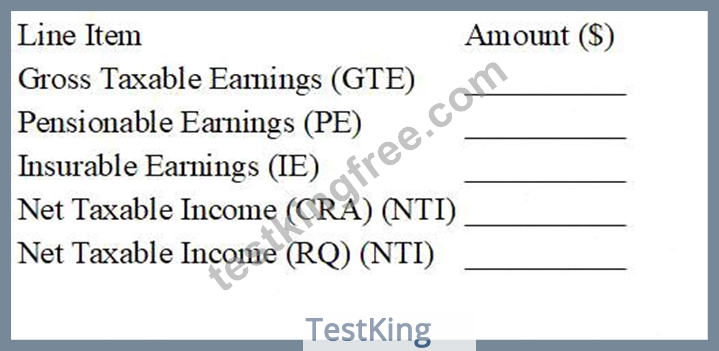
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
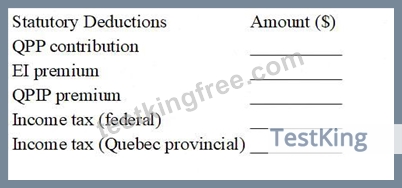
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
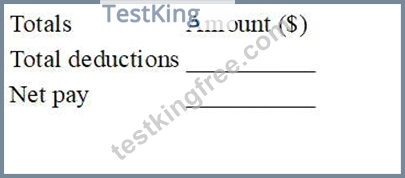
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
NEW QUESTION # 54
How many pay periods will be used to calculate insurable earnings inBlock 15Bon the Record of Employment if the employee is paidweekly?
Answer: D
Explanation:
For apaper ROE, Service Canada's ROE guidance uses a set number ofmost recent consecutive pay periods to support the reporting of insurable earnings. InBlock 15C(insurable earnings by pay period), the paper ROE provides27 fields, which allows reporting up to27 weekly pay periods(or fewer if the employee worked fewer periods).
Block15Bis thetotal insurable earningsfor the applicable number of consecutive pay periods, and for a weekly payroll this aligns with the same maximum count used on the paper ROE earnings grid-27periods.
Practically, this means payroll totals the employee's insurable earnings for thelast 27 consecutive weekly pay periodsleading up to the interruption of earnings (or the full period of employment if shorter). Using the correct number of pay periods ensures Service Canada has the right earnings history to adjudicate EI benefits accurately and reduces ROE processing issues.
NEW QUESTION # 55
Which pension plan requires the services of an actuary to study and forecast future needs of the plan to ensure the plan remains sufficiently funded to provide employees with their retirement benefits?
Answer: B
Explanation:
A defined benefit (DB) pension plan promises a future pension benefit based on a formula (for example, service and earnings). Because the benefit is defined, the plan must ensure it is adequately funded to meet future liabilities. That requires actuarial valuations-professional studies that forecast future obligations and determine required contributions. Regulators describe DB plan funding as being based on actuarial calculations and require administrators to file actuarial valuation reports to establish funding and contribution requirements.
A defined contribution (DC) plan does not promise a specific future pension amount; contributions are defined, and the retirement outcome depends on investment performance-so it does not require the same ongoing actuarial funding valuations for promised liabilities. An RRSP is an individual savings plan, not an employer DB plan requiring actuarial funding reports.
Therefore, the correct answer is Defined benefit pension plan (option A).
NEW QUESTION # 56
The capital cost of an employer-owned vehicle includes:
Answer: C
Explanation:
For CRA automobile benefit purposes (standby charge on an employer-owned automobile), the "cost" used is the capital cost, which includes more than just the sticker price. CRA guidance states the cost includes the trade-in amount (if applicable), additions, and GST/HST and PST as part of the cost base used in the standby charge calculation.
Option D is the best match because it includes vehicle options/accessories, sales taxes, and additions that add to depreciation value. Importantly, CRA also notes that certain specialized equipment added to meet the requirements of a disabled person or employment (examples include heavy-duty suspension and power winches) is not considered part of the automobile's cost for standby charge purposes. This directly rules out options A and C, since they treat specialized equipment as part of capital cost. Option B is incorrect because CRA includes sales taxes (GST/HST and PST) in the cost base.
NEW QUESTION # 57
......
If you just free download the demos of our PF1 exam questions, then you will find that every detail of our PF1 study braindumps is perfect. Not only the content of the PF1 learning guide is the latest and accurate, but also the displays can cater to all needs of the candidates. It is all due to the efforts of the professionals. These professionals have full understanding of the candidates’ problems and requirements hence our PF1 training engine can cater to your needs beyond your expectations.
Reliable PF1 Test Prep: https://www.testkingfree.com/National-Payroll-Institute/PF1-practice-exam-dumps.html
2026 Latest TestKingFree PF1 PDF Dumps and PF1 Exam Engine Free Share: https://drive.google.com/open?id=1yiUdjLl5t9zCiVsn8yD5nV--UPeprB0I