P.S. Free & New IIA-CIA-Part2 dumps are available on Google Drive shared by ExamcollectionPass: https://drive.google.com/open?id=16c8-WPic_Yt9Tg6XPWqCa74N-lesc886
The price for IIA-CIA-Part2 study materials is quite reasonable, no matter you are a student at school or an employee in the company, you can afford it. Just think that you just need to spend some money, you can get the certificate. What’s more, IIA-CIA-Part2 exam materials are compiled by skilled professionals, and they cover the most knowledge points and will help you pass the exam successfully. We have online and offline chat service stuff, they have the professional knowledge about IIA-CIA-Part2 Exam Dumps, and you can have a chat with them if you have any questions.
| Section | Weight | Objectives |
|---|---|---|
| Performing the Engagement | 40% | - Information gathering: interviews, observation, document review, and data analysis - Assessing IT governance, security, and control frameworks - Assessing compliance with laws, regulations, and organizational policies - Root cause analysis and evaluation of evidence - Use of technology tools to support engagement execution (e.g., CAATs, data analytics) - Assessing the adequacy and effectiveness of risk management and controls - Applying analytical approaches and process mapping techniques - Drawing conclusions and formulating recommendations - Development of engagement findings: criteria, condition, cause, and effect - Evaluation of fraud risk and fraud-related indicators during engagements |
| Planning the Engagement | 20% | - Understanding business processes, IT systems, and relevant regulations - Detailed engagement work program development - Risk and control identification and assessment for the engagement - Engagement planning procedures including data analytics and sampling - Coordination with stakeholders during engagement planning - Engagement objectives, scope, and resource allocation |
| Communicating Engagement Results and Monitoring Progress | 20% | - Monitoring and follow-up on the resolution of engagement findings - Reporting on the adequacy of management's corrective actions - Communication of engagement results: objectives, scope, conclusions, recommendations, action plans - Developing recommendations vs. requesting management action plans vs. collaborative approaches - Attributes of effective engagement communication: accurate, objective, clear, concise, constructive, complete, timely - Disseminating final results to appropriate stakeholders - Management response and action plan tracking |
| Managing the Internal Audit Activity | 20% | - Risk-based audit planning and alignment with organizational strategy - Strategic role of internal audit within governance, risk management, and control - Knowledge management and information sharing across the internal audit activity - Internal audit operations: planning, organizing, directing, and monitoring - Coordination with external auditors and other internal assurance providers - Managing financial, human, and IT resources within the internal audit function |
>> IIA-CIA-Part2 Free Exam Questions <<
You can also trust ExamcollectionPass IIA IIA-CIA-Part2 exam questions and start this journey with complete peace of mind and satisfaction. The Internal Audit Engagement practice questions are designed and verified by experienced and qualified Internal Audit Engagement (IIA-CIA-Part2) exam experts. They work collectively and put their expertise to ensure the top standard of ExamcollectionPass IIA IIA-CIA-Part2 Exam Dumps. So we can say that with the ExamcollectionPass IIA IIA-CIA-Part2 exam questions, you will get everything that you need to learn, prepare and pass the difficult IIA IIA-CIA-Part2 certification exam with good scores.
NEW QUESTION # 650
During the planning phase of an internal audit engagement, what is the primary reason for conducting interviews with operational management?
Answer: C
Explanation:
The primary reason for interviewing operational management during engagement planning is to understand the objectives of the area or process under review. This ensures that the audit aligns with business goals and assesses the relevance of internal controls.
* Validating the engagement work program (A) occurs later in the planning process.
* Assessing management's knowledge of risks and controls (C) is important but not the primary purpose of interviews.
* Reviewing past action plans (D) is relevant for follow-up audits, not initial engagement planning.
Reference:IIA's Practice Guide: Engagement Planning - Understanding the Business Process and Risks.
NEW QUESTION # 651
Which of the following tests must an internal auditor perform in order to ensure that inbound electronic data interchange (EDI) transactions are received and translated accurately?
I. Computerized tests to assess transaction reasonableness and validity.
II. Review of log books to ensure that transactions are logged upon receipt.
III. Edit checks to identify unusual transactions.
IV. Verification of limitations on the authority of users to initiate specific EDI transactions.
Answer: A
Explanation:
Section: Volume B
NEW QUESTION # 652
An internal auditor s examination of accounts receivable generates the following results: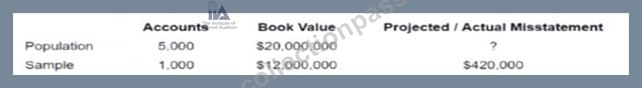
What is the projected misstatement for the population if ratio estimation is used?
Answer: B
Explanation:
To determine the projected misstatement for the population using ratio estimation, the following calculation can be used:
Projected Misstatement=(Sample MisstatementSample Book Value)
×Population Book ValueProjected Misstatement=(Sample Book ValueSample Misstatement)
×Population Book Value
Given:
* Sample Misstatement = $420,000
* Sample Book Value = $12,000,000
* Population Book Value = $20,000,000
Projected Misstatement=(420,00012,000,000)×20,000,000Projected Misstatement=(12,000,000420,000)×20,
000,000
Projected Misstatement=0.035×20,000,000=700,000Projected Misstatement=0.035×20,000,000=700,000 Therefore, the projected misstatement is $700,000.
:
IIA Standards: 2320 - Analysis and Evaluation
IIA Practice Guide: Statistical Sampling
NEW QUESTION # 653
Which of the following would most likely form part of the engagement scope?
Answer: C
Explanation:
The engagement scope outlines the specific boundaries, focus areas, and activities that the internal audit will examine. The analysis of wire transfers exceeding $10,000 within a specified timeframe is a clear, specific task that defines what will be reviewed during the engagement, making it a typical element of an engagement scope.
IIA Reference:
IIA Standard 2220: Engagement Scope states that the scope must be sufficient to satisfy the engagement's objectives and should outline specific areas and processes to be reviewed. Analyzing transactions over a certain threshold, like wire transfers exceeding $10,000, is a well-defined aspect of what the audit will cover.
NEW QUESTION # 654
When forming an opinion on the adequacy of management's systems of internal control, which of the following findings would provide the most reliable assurance to the chief audit executive?
* During an audit of the hiring process in a law firm, it was discovered that potential employees' credentials were not always confirmed sufficiently. This process remained unchanged at the following audit.
* During an audit of the accounts payable department, auditors calculated that two percent of accounts were paid past due. This condition persisted at a follow up audit.
* During an audit of the vehicle fleet of a rental agency, it was determined that at any given time, eight percent of the vehicles were not operational. During the next audit, this figure had increased.
* During an audit of the cash handling process in a casino, internal audit discovered control deficiencies in the transfer process between the slot machines and the cash counting area. It was corrected immediately.
Answer: C
Explanation:
The most reliable assurance comes from findings that demonstrate both the identification of issues and the effectiveness of corrective actions. In the provided scenarios, the accounts payable audit (2) and the cash handling process audit (4) illustrate instances where issues were identified, and actions were either needed (2) or taken promptly (4), thus providing a clear basis for forming an opinion on internal control adequacy.
References: = IIA Standard 2410 - Criteria for Communicating and Standard 2500 - Monitoring Progress.
NEW QUESTION # 655
......
Before you purchase our product you can have a free download and tryout of our IIA-CIA-Part2 study tool. We provide the demo on our pages of our product on the websites and thus you have an understanding of part of our titles and the form of our IIA-CIA-Part2 test torrent. We guarantee to you if you fail in we will refund you in full immediately and the process is simple. If only you provide us the screenshot or the scanning copy of the IIA-CIA-Part2 failure marks we will refund you immediately. If you have doubts or other questions please contact us by emails or contact the online customer service and we will reply you and solve your problem as quickly as we can. So feel relieved when you buy our IIA-CIA-Part2 guide torrent.
Test IIA-CIA-Part2 Questions Fee: https://www.examcollectionpass.com/IIA/IIA-CIA-Part2-practice-exam-dumps.html
P.S. Free & New IIA-CIA-Part2 dumps are available on Google Drive shared by ExamcollectionPass: https://drive.google.com/open?id=16c8-WPic_Yt9Tg6XPWqCa74N-lesc886