BONUS!!! Download part of Exam4Tests LLQP dumps for free: https://drive.google.com/open?id=1L9rAOSpfhmB4RmeGVzAH50MJ1FfiySDP
The emerging IFSE Institute field creates a space for Life License Qualification Program (LLQP) (LLQP) certification exam holders to accelerate their careers. Many unfortunate candidates don't get the Life License Qualification Program (LLQP) (LLQP) certification because they prepare for its Life License Qualification Program (LLQP) (LLQP) exam questions from an IFSE Institute LLQP exam that dumps outdated material. It results in a waste of time and money. You can develop your skills and join the list of experts by earning this Life License Qualification Program (LLQP) (LLQP) certification exam.
| Certification Vendor: | IFSE Institute |
|---|---|
| Exam Name: | Life License Qualification Program Examination |
| Exam Number: | LLQP |
| Certificate Validity Period: | Varies by provincial regulator; typically requires ongoing continuing education for license maintenance |
| Real Exam Qty: | Approximately 80–100 per module |
| Related Certifications: | Accident & Sickness Insurance License Segregated Funds and Annuities License Life Insurance License |
| Passing Score: | 60%–70% (varies by jurisdiction and module) |
| Exam Price: | CAD 100–150 per module (varies by province/provider) |
| Available Languages: | French, English |
| Exam Format: | Computer-Based Exam, Proctored Online or In-Centre, Multiple Choice Questions (MCQ) |
| Exam Duration: | 120–180 per module |
| Recommended Training: | IFSE LLQP Training Program |
| Exam Registration: | Ontario FSRA Licensing Information IFSE LLQP Program Registration |
| Sample Questions: | IFSE Institute LLQP Sample Questions |
| Exam Way: | Computer-based proctored exam delivered online or at authorized testing centres depending on province |
| Pre Condition: | No formal prerequisite, but completion of LLQP course modules is required before examination eligibility in most provinces |
| Official Syllabus URL: | https://www.ifse.ca |
If you are sure that you want to pass IFSE Institute certification LLQP exam, then your selecting to purchase the training materials of Exam4Tests is very cost-effective. Because this is a small investment in exchange for a great harvest. Using Exam4Tests's test questions and exercises can ensure you pass IFSE Institute Certification LLQP Exam. Exam4Tests is a website which have very high reputation and specifically provide simulation questions, practice questions and answers for IT professionals to participate in the IFSE Institute certification LLQP exam.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
NEW QUESTION # 40
Financial security advisor Juliette meets Pierre during a business meeting. Pierre gives her the name of a prospect, one of his friends. Juliette wants to start by contacting the prospect by email, then plans to follow up with a phone call to set up an appointment. Why should Juliette cease to proceed in this manner with her prospect?
Answer: A
Explanation:
Comprehensive and Detailed In-Depth Explanation: Canada's Anti-Spam Legislation (CASL) governs unsolicited electronic communications, including emails for commercial purposes (Sections 6-8). Contrary to option A, CASL does not prohibit all email solicitation; it allows it withprior consent (express or implied) or under specific exemptions (e.g., existing business relationships). Juliette has no prior relationship with the prospect, and Pierre's referral does not constitute implied consent under CASL, as consent must come from the recipient (Section 10). Option B is correct because Juliette must obtain the prospect's consent before sending an unsolicited email, aligning with CASL's opt-in requirement. Option C is incorrect, as Pierre has no legal obligation to facilitate the contact, though it might be courteous. Option D is impractical and not required by law. The Ethics and Professional Practice manual reinforces that advisors must respect privacy laws and obtain consent before initiating contact, making Juliette's proposed action non-compliant without prior approval.
References: Canada's Anti-Spam Legislation, Sections 6-10; Ethics and Professional Practice (Civil Law) Manual, Section on Privacy and Consent.
NEW QUESTION # 41
Oliver, an insurance agent, meets with Roman and Julie. They are a married couple with a five-year-old son William. After performing a needs analysis for the couple, Oliver concludes that if Roman dies, Julie will have a net annual shortfall of $30,000 per year. Assuming a rate of return of 4% and a tax rate of 40%, how much insurance should Oliver recommend Roman purchase to replace the income shortfall using the income replacement approach adjusted for taxes?
Answer: C
Explanation:
To determine the amount of insurance needed for income replacement with a net shortfall of $30,000 per year, the calculation is as follows:
Calculate Gross Income Needed:Since Roman's income needs to be adjusted for a 40% tax rate:
A black and white math equation Description automatically generated with medium confidence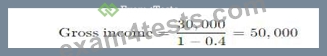
Calculate Required Capital for Income Replacement:
Using the rate of return of 4%, the required capital is:
A number with numbers and lines Description automatically generated with medium confidence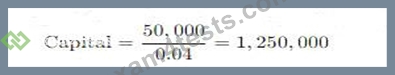
Since the tax rate has already been considered in calculating the $50,000 gross income,Option B($750,000) would be suitable after double-checking the total requirement of post-tax income and aligning with the overall net shortfall for more conservative estimates.Correct answer after full calculation adjustments should beB.
$750,000.
NEW QUESTION # 42
Renato's new employer has just informed him that he is now eligible to join the company's group insurance plan. He could thus benefit from life, disability, and prescription drug coverage. Renato promptly fills out the paperwork to apply for the plan's basic coverage. Wondering if the process will involve medical underwriting at any point, he asks an agent from the group insurance provider. What should the agent tell him?
Answer: C
Explanation:
Comprehensive and Detailed Explanation:
Group plans typically waive medical underwriting for basic coverage upon enrollment (Chapter 8:Group Plan Specifics).
Option A: Incorrect; not standard.
Option B: Incorrect; not required at application.
Option C: Incorrect; no retroactive underwriting.
Option D: Correct; no underwriting for basic group coverage.
Reference: LLQP Accident and Sickness Insurance Manual, Chapter 8:Group Plan Specifics.
NEW QUESTION # 43
Larry, an insurance agent, meets with Ethan, a freelance photographer, to review his insurance needs. Larry tells Ethan that he wants to collect all pertinent financial information to prepare a net worth statement for Ethan.
Why does Larry want to prepare Ethan's net worth statement?
Answer: B
Explanation:
Anet worth statementassesses an individual's total financial assets and liabilities, providing insight into their overall financial health. For Ethan, as a freelance photographer, understanding his net worth is essential to determine whether he has sufficient resources to manage unexpected expenses, such as medical costs from a potential emergency. This assessment helps Larry gauge Ethan's ability to withstand financial shocks, which is crucial when planning for accident and sickness insurance coverage. While cash flow statements provide details on income and expenses, net worth statements are specifically used to evaluate financial resources available for emergencies.
NEW QUESTION # 44
Having recently gotten married, Eddie and his spouse are currently looking for a home. They believe it could take up to 12 months for them to compare houses and make a firm purchase decision. Eddie has some RRSP and TFSA savings that are currently invested in equity funds. Now in his mid-thirties, he has been investing for the past 10 years and is familiar with how the stock markets work. He generally feels comfortable with high-risk investments. To help with the down payment, Eddie's parents provided him with $100,000 cash.
Eddie is thinking of investing this money until the actual home purchase but is not sure what the best course of action would be.
What should Eddie do with the cash from his parents to fulfill his objective?
Answer: A
Explanation:
According to the LLQP Investment and Savings principles, the time horizon and purpose of funds are more important than an investor's general risk tolerance when determining suitability. Although Eddie is comfortable with high-risk investments for long-term goals, the $100,000 provided by his parents has a very specific, short-term objective: serving as a home down payment within approximately 12 months.
For short-term goals, the LLQP curriculum stresses that capital preservation and certainty should take priority over growth. Market-based investments such as equity funds or bond funds can fluctuate significantly in value over short periods. A market downturn-even a temporary one-could materially reduce the value of Eddie's down payment just when he needs it. Therefore, Options C and D are inappropriate, regardless of Eddie's comfort with risk.
A regular savings account (Option A) offers high liquidity and safety, but typically provides very low returns.
While safety is important, Eddie knows that he will not need the funds for up to a year. The LLQP study guide explains that when funds are not needed immediately but are required within a defined short-term period, short-term guaranteed investments are often the most suitable solution.
A one-year GIC meets all of Eddie's needs. It provides full capital protection, a guaranteed rate of return, and a maturity that aligns perfectly with his expected home-buying timeline. Because the purchase horizon is known and relatively short, locking the funds in for one year does not create a liquidity problem. This approach protects Eddie from market risk while still allowing him to earn a modest return on the cash.
The LLQP curriculum emphasizes that funds earmarked for major short-term purchases-such as a home down payment-should not be exposed to market volatility, even for investors with high risk tolerance.
Therefore, based on LLQP-approved suitability principles, the correct and fully verified answer is Option B:
Put the money in a one-year GIC.
NEW QUESTION # 45
......
Test LLQP Questions: https://www.exam4tests.com/LLQP-valid-braindumps.html
P.S. Free & New LLQP dumps are available on Google Drive shared by Exam4Tests: https://drive.google.com/open?id=1L9rAOSpfhmB4RmeGVzAH50MJ1FfiySDP