As is known to us, it must be of great importance for you to keep pace with the times. If you have difficulty in gaining the latest information when you are preparing for the AFP-Exam-1, it will be not easy for you to pass the exam and get the related certification in a short time. However, if you choose the AFP-Exam-1 exam reference guide from our company, we are willing to help you solve your problem. There are a lot of IT experts in our company, and they are responsible to update the contents every day. If you decide to buy our AFP-Exam-1 study question, we can promise that we will send you the latest information every day.
| Section | Weight | Objectives |
|---|---|---|
| Technical Competencies | 84% | - Retirement Planning - Risk Management and Insurance - Asset and Liability Management - Tax Planning - Investment Planning - Estate Planning |
| Enabling Competencies | 16% | - Client Relationship and Practice Management - Professional Conduct and Regulatory Compliance |
>> AFP-Exam-1 Actual Braindumps <<
As we all know, we are now facing more and more competition. The AFP-Exam-1 exam is an important way to improve our competitiveness. The certification can show others whether we have a certain skill, whether we meet the requirements of others, for us. Get approved at work to increase your chips. For different needs, our AFP-Exam-1 Certification Exam questions are flexible and changeable. On the one hand, AFP-Exam-1 pdf files allow you to make full use of fragmented time, and you will be able to pass the AFP-Exam-1 exam with the least time and effort with our AFP-Exam-1 training materials.
NEW QUESTION # 98
Demario, age 28, has just started his own law firm. He met with his financial planner, Ivy, and she told him that he needs insurance, but Ivy did not specify which type. Demario is single and owns his own home. At this point in his career, his greatest asset is his human capital. Which type of insurance should Ivy have specified to purchase in order for Demario to best protect this asset?
Answer: C
Explanation:
Demario's human capital is his capacity to earn professional income from his law practice. A disability can destroy that earning capacity without causing death and without necessarily triggering critical illness coverage. Disability insurance is therefore the correct product to protect his greatest asset. Term life insurance would be more relevant if he had dependants, estate obligations, or a debt-repayment need at death. Extended health care helps with medical and dental costs but does not replace a lawyer's income if he cannot work.
Critical illness insurance pays on diagnosis of specified illnesses and can supplement planning, but it does not provide the same ongoing income-replacement function as disability coverage. Because Demario is self- employed, policy features such as own-occupation definition, elimination period, benefit period, and business overhead coverage should be reviewed carefully. Study Guide focus: human capital, disability insurance, self- employed professionals, income replacement, and risk management. The recommendation is therefore built around income continuity, not estate creation or reimbursement of medical expenses.
NEW QUESTION # 99
Robert is meeting with his wealth advisor to review options to put a plan in place to save for his children's education. He has a daughter, age seven, and a disabled son, age four Robert would like to maximize his savings towards this goal, ensure the strategy is tax efficient and utilize available grants. Which option is most appropriate for Robert's plan?
Answer: D
Explanation:
A family RESP is the most appropriate education savings structure for Robert's two children. It permits multiple related beneficiaries and provides flexibility if one child does not use all of the education funding.
Contributions can attract available education savings grants, and growth is tax-deferred until paid as educational assistance payments. A group RESP is less flexible and may impose restrictions that are not ideal for a family with different education paths. Individual RESPs can work, but they reduce the ability to shift unused resources between siblings compared with a family plan. An education-purpose trust lacks the RESP grant structure and tax treatment. The disabled son's broader planning may also require RDSP analysis, but that option is not offered and does not replace RESP education funding. The planner should confirm grant limits, contribution limits, beneficiary eligibility, and withdrawal rules. Study Guide focus: RESPs, family plans, education grants, tax-deferred education savings, and beneficiary flexibility.
NEW QUESTION # 100
Ali wishes to retire in five years. His financial planner calculates that he needs to save an additional $40,000 to meet his retirement income objectives. What would Ali's financial planner advise him to do in order to meet his retirement income objectives?
Answer: C
Explanation:
With only five years until retirement, Ali's planner should recommend reducing current expenses and redirecting the freed cash flow to retirement savings. The short time horizon makes aggressive corrective strategies dangerous. Borrowing through a mortgage to invest introduces leverage risk and could worsen retirement security if markets underperform. Increasing equity exposure solely to chase a higher return may be inconsistent with the time horizon and risk capacity. Whole life insurance is not an efficient solution for a near-term retirement savings shortfall; it combines insurance and investment features but does not directly solve a five-year funding gap. Expense reduction is controllable, immediate, and aligned with the identified
$40,000 savings need. The planner should quantify how much monthly savings is required and monitor progress annually. Study Guide focus: retirement shortfall strategies, savings rate, time horizon, risk capacity, leverage risk, and expense management. The recommendation is conservative because the closer the retirement date, the less time Ali has to recover from investment error.
NEW QUESTION # 101
James is visiting Gurjeet, his financial planner, to discuss his financial affairs after the recent passing of his long-time partner Peter. James is concerned that the cost of probate will be a heavy burden. Which holdings should Gurjeet advise James are included in calculating the cost of probate?
Answer: A
Explanation:
Probate is generally calculated on assets that form part of the deceased's estate. A tenancy in common interest is owned by the deceased as a separate property interest and does not pass automatically to the other owner by survivorship. It is therefore included in the estate unless another legal arrangement applies. Insurance contracts with a preferred or named beneficiary usually pay directly to the beneficiary. Assets held in a formal irrevocable trust are owned by the trust, not personally by the deceased. Registered plans with a valid adult child beneficiary designation generally bypass the estate, although tax consequences may still arise on the deceased's terminal return. Gurjeet should distinguish probate inclusion from income tax inclusion; an asset may bypass probate and still create tax. For the probate-cost question, the tenancy in common holding is the correct inclusion. Study Guide focus: probate property, beneficiary designations, trusts, joint ownership, and estate administration.
NEW QUESTION # 102
Justis, age 62, and his wife Jen, age 58, are meeting with their financial planner, Luke. They are both planning to retire by age 65. Their goals are to minimize debt and reduce taxes. The couple's financial situation is outlined below.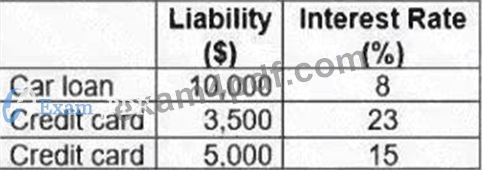
Justis' annual income is $25,000. He has a $15,000 RRSP, $30,000 single non-registered account and a
$25,000 TFSA. Jen's annual income is $60,000, and she has a $150,000 RRSP, $50,000 single non-registered account and a $20,000 TFSA.
Jen's marginal tax rate is 35%, and Justis' is 25%. Assuming all investments are making interest income of
10%, what would be the most appropriate strategy for Luke to recommend for the couple?
Answer: A
Explanation:
Luke should recommend using Jen's non-registered funds because that option clears the liabilities without triggering registered-plan withdrawal income. The debts total $18,500 and include expensive consumer borrowing: credit cards at 23% and 15%, plus a car loan at 8%. The couple's taxable investments earn 10% interest before tax, so Jen's after-tax return is approximately 6.5% at a 35% marginal rate. Paying the credit cards is equivalent to earning a risk-free after-tax return equal to the interest avoided, which is materially better than leaving the money invested. Using either spouse's RRSP would create taxable income and permanently reduce retirement capital. Using Justis's non-registered funds is less effective because his lower tax rate makes his after-tax investment return higher than Jen's, so Jen's taxable account is the better source.
Study Guide focus: debt repayment priority, after-tax returns, registered versus non-registered withdrawals, and household cash-flow planning. The recommendation also preserves retirement accounts for the couple's age-65 objective while eliminating the highest-cost liabilities first.
NEW QUESTION # 103
......
Services like quick downloading within five minutes, convenient and safe payment channels made for your convenience. Even newbies will be tricky about this process. Unlike product from stores, quick browse of our AFP-Exam-1 practice materials can give you the professional impression wholly. So, they are both efficient in practicing and downloading process. By the way, we also have free demo as freebies for your reference to make your purchase more effective.
AFP-Exam-1 Valid Test Topics: https://www.exam4pdf.com/AFP-Exam-1-dumps-torrent.html