The high efficiency method is targeted learning rather than comprehensive learning. Comprehensive learning can improve your basic knowledge but it is not the best to clear exams and obtain certifications. Our valid CSI AFP-Exam-1 exam cram review can help you pass this subject in a short time. If your goal is passing all exams and obtain a useful certification. The best shortcut is to buy Valid AFP-Exam-1 Exam Cram Review. Most experienced people can prove that. Good products are here waiting for you.
| Section | Weight | Objectives |
|---|---|---|
| Technical Competencies | 84% | - Estate Planning - Investment Planning - Risk Management and Insurance - Tax Planning - Retirement Planning - Asset and Liability Management |
| Enabling Competencies | 16% | - Professional Conduct and Regulatory Compliance - Client Relationship and Practice Management |
>> AFP-Exam-1 Valid Learning Materials <<
They are all masterpieces from processional experts and all content are accessible and easy to remember, so no need to spend a colossal time to practice on them. Just practice with our AFP-Exam-1 exam guide on a regular basis and desirable outcomes will be as easy as a piece of cake. On some tricky questions, you don't need to think too much. Only you memorize our questions and answers of AFP-Exam-1 study braindumps, you can pass exam simply. With our customer-oriented AFP-Exam-1 actual question, you can be one of the former exam candidates with passing rate up to 98 to 100 percent.
NEW QUESTION # 97
Jackson, a wealth advisor, is helping Terry, a self-employed IT professional, determine his net income. The goal is to develop a budget and savings strategy for the year ahead Terry has provided the information below: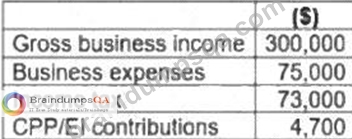
What is Terry's net business income?
Answer: C
Explanation:
Terry's net business income is $225,000. The calculation starts with gross business income of $300,000 and subtracts deductible business expenses of $75,000. Income tax is not deducted in computing net business income for this purpose; it is calculated after taxable income is determined. CPP/EI contributions are also not treated as ordinary business expenses in this basic net business income calculation. Option A and option B incorrectly subtract personal tax and statutory contribution amounts. Option D subtracts the CPP/EI amount from business profit but still incorrectly treats it as part of the business-income calculation. The planner needs the correct net business income figure because it drives budgeting, savings capacity, tax installments, retirement contribution planning, insurance affordability, and debt-service analysis. AFP cash-flow work separates business operating results from personal tax payments and after-tax cash flow. Study Guide focus:
self-employment income, deductible business expenses, net income, tax planning, and budgeting.
NEW QUESTION # 98
Dianna has just taken a 20-year mortgage and wants insurance only to ensure the mortgage can be repaid if she dies during that period. She is considering whole life insurance. What should her planner most likely explain?
Answer: B
Explanation:
The need described is temporary: repay a mortgage if death occurs during the 20-year amortization or term horizon. Term life insurance is usually designed for exactly this type of time-limited risk. It provides a death benefit for a selected period and is typically less expensive than permanent insurance for the same initial coverage amount. Option A is inaccurate because whole life includes lifetime coverage and cash-value features, which increase cost and may be unnecessary for a temporary debt. Option C confuses mortgage default insurance, which protects the lender against borrower default, with life insurance that protects the family's cash flow. Option D is wrong because critical illness insurance pays on survival after a covered illness; it does not pay a death benefit. The planner should compare personally owned term insurance with creditor insurance, considering underwriting, beneficiary control, portability, and conversion privileges. The recommendation should match the liability duration and the client's broader survivor-income needs.
References/topics: term life insurance, mortgage protection, temporary insurance needs, risk management.
NEW QUESTION # 99
Ivan has been relocated to a new office by his employer and is considering moving to a home closer to his new workplace. What is the minimum distance Ivan will have to move in order to qualify for the work-related moving expenses income tax deduction?
Answer: A
Explanation:
The minimum distance rule for work-related moving expense deductibility is 40 kilometres. The new home must be at least 40 kilometres closer to the new work location, measured by the shortest normal public route, for the move to qualify under the standard Canadian tax rule. This is a threshold test; moving 15 or 25 kilometres closer is not enough, and 60 kilometres is more than the required minimum. The planner should also confirm that the move relates to employment or business income, that the new residence becomes the ordinary place of residence, and that eligible expenses are claimed only to the extent permitted by the rules.
The fact that Ivan was relocated by his employer makes the moving-expense issue relevant, but the question asks only the minimum distance. Study Guide focus: moving expense deduction, employment relocation, 40- kilometre test, and personal tax deductions. The distance rule should be confirmed before the client assumes moving costs will produce a tax deduction.
NEW QUESTION # 100
A retiree holds most of her investments in interest-bearing GICs inside a non-registered account while her TFSA is invested in cash. She has unused TFSA room and wants to improve after-tax efficiency without increasing total portfolio risk materially. What should the planner consider?
Answer: D
Explanation:
Interest income is fully taxable in a non-registered account, so sheltering interest-bearing assets in a TFSA can improve after-tax results without changing the underlying risk profile materially. If the retiree already wants conservative holdings, placing some GIC or high-interest savings exposure inside the TFSA may reduce annual taxable income and preserve capital. Option B changes the risk profile and is not responsive to the client's objective. Option C may be an estate or family-support decision, but it does not directly improve asset-location efficiency. Option D introduces leverage and repayment risk, which conflicts with the retiree's conservative profile. The planner should evaluate available TFSA room, maturity dates, liquidity needs, CDIC eligibility where relevant, estate beneficiary designations, and whether non-registered accrued interest will be triggered. The principle is asset location: tax-inefficient income is often better sheltered where possible, provided the recommendation remains suitable. References/topics: asset location, TFSA, interest income taxation, retirement portfolio efficiency.
NEW QUESTION # 101
Keitaro, age 42, and Ruth, age 52, are married and have two children - Maximo, age 20, and Hannah, age 16, both from Keitaro's previous marriage. In the event Keitaro dies, he would like to minimize taxes, provide for Ruth for the remainder of her life, and then after her death leave the residual to his children. What estate planning strategy should his financial planner recommend to help Keitaro achieve his goal?
Answer: C
Explanation:
A testamentary spousal trust is the best strategy for Keitaro's blended-family objective. It can provide Ruth with income for life, defer tax on assets transferred at death to a qualifying spouse or spousal trust, and preserve the remaining capital for Maximo and Hannah after Ruth's death. The trust is created through Keitaro's will, so it is testamentary, not inter vivos. The children should be capital beneficiaries, not income beneficiaries during Ruth's lifetime, because the goal is to provide for Ruth first and leave the residual to the children later. Naming the children as income and capital beneficiaries while Ruth is alive would undermine the spousal-trust rollover requirements and the planning objective. The planner should refer Keitaro to an estate lawyer to draft the trust terms precisely. Study Guide focus: testamentary spousal trusts, blended-family planning, spousal rollover, income beneficiary, and capital remainder. The will should also address trustee powers, encroachment rights, tax filings, and the treatment of registered assets.
NEW QUESTION # 102
......
Whether you want to improve your skills, expertise or career growth of AFP-Exam-1 exam, with Braindumpsqa's AFP-Exam-1 training materials and AFP-Exam-1 certification resources can help you achieve your goals. Our AFP-Exam-1 Exams files feature hands-on tasks and real-world scenarios; in just a matter of days, you'll be more productive and embracing new technology standards.
AFP-Exam-1 Latest Exam Notes: https://www.braindumpsqa.com/AFP-Exam-1_braindumps.html