さらに、ShikenPASS LLQPダンプの一部が現在無料で提供されています:https://drive.google.com/open?id=1jF1UEx4U6h1l18Z3HOJ-x8wni-Pfj2Yr
長年にわたり、ShikenPASSはずっとIT認定試験を受験する皆さんに最良かつ最も信頼できる参考資料を提供するために取り組んでいます。IT認定試験の出題範囲に対して、ShikenPASSは豊富な経験を持っています。また、ShikenPASSは数え切れない受験生を助け、皆さんの信頼と称賛を得ました。ですから、ShikenPASSのLLQP問題集の品質を疑わないでください。これは間違いなくあなたがLLQP認定試験に合格することを保証できる問題集です。ShikenPASSは試験に失敗すれば全額返金を保証します。このような保証があれば、ShikenPASSのLLQP問題集を購入しようか購入するまいかと躊躇する必要は全くないです。この問題集をミスすればあなたの大きな損失ですよ。
| トピック | 出題範囲 |
|---|---|
| トピック 1 |
|
| トピック 2 |
|
| トピック 3 |
|
| トピック 4 |
|
あなたは短い時間でLLQP試験に合格できるために、我々は多くの時間と労力を投資してあなたにIFSE InstituteのLLQP試験を開発しますから、我々の提供する商品はIT認定試験という分野で大好評を得ています。だからこそ、我々はShikenPASSの問題集に自信があります。自信があるから、我々は失敗返金ということを承諾します。
質問 # 162
Six years ago, Diu purchased an immediate life annuity with a 10-year guarantee period. The annuity paid her a monthly benefit of $1,800. She named her son Shan as the beneficiary of the policy and her niece Haru as a contingent beneficiary. Shan died four months ago in a motorcycle accident and between grieving and planning the funeral, Diu forgot to update her beneficiary designation. Last week, Diu died of a heart attack.
Who would receive the annuity benefits?
正解:B
解説:
Since Diu had designated her son Shan as the primary beneficiary and her niece Haru as the contingent beneficiary, the death benefit from the annuity will pass to Haru, the contingent beneficiary, after Shan's death. In annuity contracts, if the primary beneficiary predeceases the annuitant and no changes are made to the designation, the benefits will typically go to the contingent beneficiary. According to LLQP principles, a contingent beneficiary is entitled to receive the remaining guaranteed payments when the primary beneficiary is no longer able to do so.
Option A is incorrect as Shan's widow is not mentioned as a beneficiary. Option B is incorrect as Shan's estate would not receive the benefits if a contingent beneficiary exists. Option D is incorrect as Diu's estate would only receive the benefits if no beneficiaries were named.
質問 # 163
Ali has all his non-registered savings and his RRSP invested in cashable GICs with terms of five years or less.
His key objective is to have enough funds for retirement. He asks his insurance agent, Rivka, whether he should have any concerns about his current strategy.
What should Rivka tell him about his portfolio?
正解:C
解説:
According to the LLQP Segregated Funds and Annuities and Investment & Savings curriculum, understanding investment risk is a critical part of assessing whether a client's portfolio aligns with their long- term objectives. Ali's stated goal is retirement funding, which is typically a long-term objective requiring growth that at least keeps pace with inflation. His current strategy consists entirely of cashable GICs with short- to medium-term maturities.
The primary concern with this strategy is inflation risk, which is the risk that the purchasing power of money will decline over time due to rising prices. The LLQP study guide explains that conservative investments such as cash and GICs often provide relatively low returns. While these returns may preserve capital in nominal terms, they may fail to keep pace with inflation, especially over long periods such as a retirement planning horizon. As a result, even though Ali's account balances may grow slightly, their real value may decrease.
Cashable GICs are designed to provide capital preservation and stability, not long-term growth. For retirement purposes, relying exclusively on these instruments may result in insufficient accumulation of funds to meet future income needs. The LLQP curriculum highlights that portfolios heavily weighted toward low-risk, fixed- income investments are particularly vulnerable to inflation risk when used for long-term goals.
The other answer choices are incorrect based on LLQP definitions. Industry risk applies to investments concentrated in a specific economic sector, which is not the case here. Liquidity risk refers to difficulty accessing funds; however, cashable GICs are generally considered liquid or moderately liquid, especially compared to long-term locked-in investments. Credit risk involves the possibility that an issuer will default; GICs issued by reputable financial institutions are typically low credit risk, and many are protected by deposit insurance.
Therefore, under LLQP-approved investment principles, Rivka should explain that Ali's portfolio is most exposed to inflation risk, making Option A the correct answer.
質問 # 164
Alexandre, a financial security advisor, recently left FinCode Inc. because of an unresolved dispute with the company. He is continuing his career as an independent advisor. This week, he has an appointment with a client who tells him that he met with another FinCode Inc. employee. However, that employee has a disciplinary record at the CSF for fraudulently copying a signature on a form. Since the client does not work in insurance and the information is public knowledge, Alexandre provides him with some clarification regarding the other advisor's case. How can Alexandre encourage the client to do business with him without denigrating his competitor?
正解:B
解説:
Comprehensive and Detailed In-Depth Explanation: The CSF Code of Ethics (Section 11) prohibits advisors from denigrating competitors, requiring professionalism in client interactions. Alexandre can't disparage the FinCode advisor despite the public disciplinary record. Option C-emphasizing his unique approach- focuses on his strengths, encouraging business ethically without criticism. Option A (check CSF records) indirectly highlights the competitor's fault, risking denigration. Option B (departure dispute) introduces irrelevant negativity. Option D (past experience) could lead to prohibited criticism. The Ethics manual promotes positive differentiation over competitor critique, making C the compliant choice.
References: CSF Code of Ethics, Section 11; Ethics and Professional Practice (Civil Law) Manual, Section on Professional Conduct.
質問 # 165
(Arthur's assets include a home worth $744,000, savings of $41,000, and a whole life insurance policy with a death benefit of $300,000 and a cash value of $196,000. His liabilities include a $150,000 reverse mortgage and $2,090 income tax owed.
What is Arthur's net worth?)
正解:D
解説:
Net worth is calculated by addingassetsand subtractingliabilities:
Assets = $744,000 + $41,000 + $196,000 = $981,000
Liabilities = $150,000 + $2,090 = $152,090
Net Worth = $981,000 - $152,090 =$828,910
Exact Extract:
"Net worth equals total assets minus total liabilities. Whole life insurance cash values are counted as assets." (Reference:Segfunds-E313-2020-12-7ED, Chapter 4.1 Financial Position of Client)
質問 # 166
Jasper is the sole breadwinner in his family. His wife Stephanie has chosen to dedicate all of her time to raising their 3 young children. Luckily, Jasper earns a monthly after-tax income of $25,000 working as a family doctor in the local clinic. Jasper meets with his insurance agent Odda to purchase a life insurance policy that will ensure his family will be able to continue to enjoy their current lifestyle in the event of his death. If his average tax rate is 40% and theinvestment return is 4%, how much life insurance should Jasper purchase based on the income replacement approach?
正解:D
解説:
The income replacement approach calculates the amount of life insurance needed to replace Jasper'safter-tax income for his dependents over a given period, accounting for an investment return. To maintain the family's current lifestyle, we need to determine the capital required to generate a monthly after-tax income of $25,000.
Calculate the Annual Income Needed:Monthly income required: $25,000Annual income required: $25,000 ×
12 = $300,000
Adjust for Tax:Since Jasper's income needs to be replaced at a pre-tax level with a tax rate of 40%, his gross income requirement is calculated as follows:
A close-up of a math Description automatically generated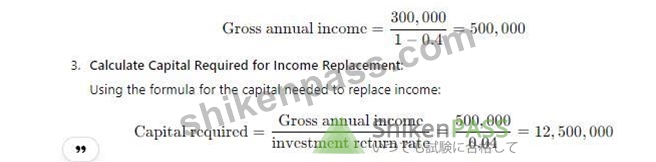
Thus, Jasper needs a life insurance policy worth$12,500,000to replace his income, allowing his family to maintain their lifestyle with a 4% investment return. This calculation aligns with LLQP principles, ensuring that the income replacement fully addresses both current lifestyle needs and tax implications.
質問 # 167
......
ShikenPASS IFSE InstituteのLLQP試験問題集は完全な無制限のダンプが含まれていますから、ShikenPASSを利用したら気楽に試験に受かることができます。製品検定合格の証明書あるいは他の人気がある身分検定によって、ShikenPASS IFSE InstituteのLLQP試験トレーニング資料の長所を完璧に見せることができます。依頼だけでなく、指導のことも最高です。ShikenPASS IFSE InstituteのLLQP試験トレーニング資料に含まれている問題と解答を利用して、IFSE InstituteのLLQP認定試験に合格することができます。
LLQP試験概要: https://www.shikenpass.com/LLQP-shiken.html
ちなみに、ShikenPASS LLQPの一部をクラウドストレージからダウンロードできます:https://drive.google.com/open?id=1jF1UEx4U6h1l18Z3HOJ-x8wni-Pfj2Yr