BTW, DOWNLOAD part of PassSureExam PF1 dumps from Cloud Storage: https://drive.google.com/open?id=1vur4IOiNMJW9nGHrIlu-iOIXDwtVuPoG
PF1 certification exam is a very import component National Payroll Institute certification exam. But passing National Payroll Institute certification PF1 exam is not so simple. In order to give to relieve pressure and save time and effort for candidates who take a preparation for the PF1 Certification Exam, PassSureExam specially produce a variety of training tools. So you can choose an appropriate quick training from PassSureExam to pass the exam.
| Section | Objectives |
|---|---|
| Earnings, Deductions, and Taxation | - Types of earnings
|
| Payroll Records and Compliance Reporting | - Government reporting
|
| Payroll Fundamentals and Compliance Framework | - Payroll legislation and regulatory bodies
|
On our webiste, you have easy access to our free demos of our PF1 exam braindumps. Once you apply for our free trials of the PF1 study materials, our system will quickly send it via email. Last but not least, you are available for our free updated version of the PF1 Real Exam. Whenever you have problems about our study materials, you can contact our online workers via email. We warmly welcome you to experience our considerate service.
NEW QUESTION # 51
Which of the following types of earnings are not considered income from employment?
Answer: A
Explanation:
Regular salary, vacation pay, and commissions are generally treated as income from employment because they are amounts paid for services performed during employment. In contrast, what many people call
"severance pay" is often classified by the CRA as a retiring allowance-an amount paid when or after an employee retires or loses their job, in recognition of long service or for the loss of employment.
This distinction matters in payroll because a retiring allowance has its own rules for withholding and potential RRSP/RPP transfer eligibility, and it is not treated the same way as normal employment income earned while actively employed. CRA technical guidance also draws lines between amounts that are employment income versus retiring allowance depending on the nature/timing of the payment.
So, among the options listed, severance pay (when it is a retiring allowance) is the one that is not considered income from employment in the way salary/vacation pay/commissions are.
NEW QUESTION # 52
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
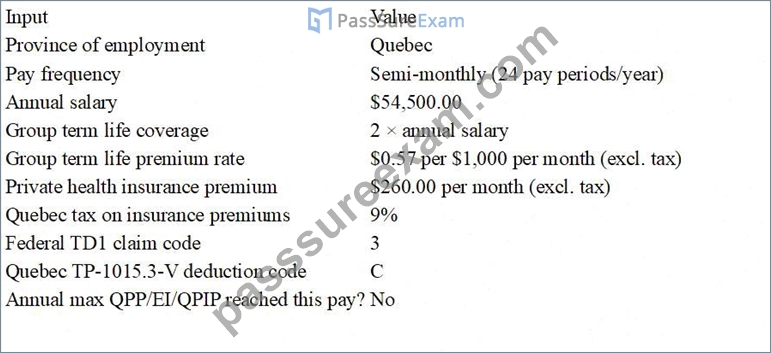
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases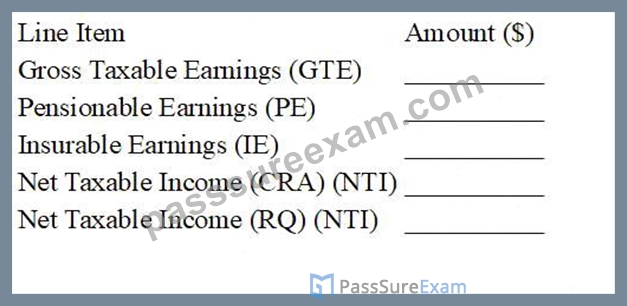
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
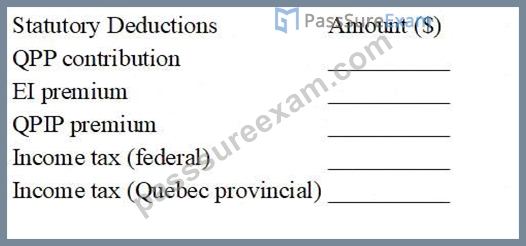
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
Step 11 - Calculate Mara's total deductions.
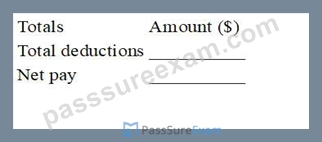
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
NEW QUESTION # 53
A death benefit is a:
Answer: B
Explanation:
The CRA defines a death benefit as the gross amount of any payment made on or after the death of an employee to recognize the employee's service in an office or employment. It can be paid to a surviving spouse
/common-law partner, heir, or the estate.
This is different from amounts the employee already earned before death (for example, regular wages up to the date of death, or vacation pay that was accrued/earned). CRA guidance treats wages and employment income earned up to and including the date of death as amounts to be reported on a T4 slip, not as a death benefit.
It's also different from a life insurance payout from an insurer (which is not an employer-paid "death benefit" for payroll reporting purposes). The payroll impact is that a qualifying death benefit is generally reported as a special payment (often on a T4A), following CRA rules for deductions and reporting of death benefits.
NEW QUESTION # 54
Phan was employed fromMarch 1, 1992throughJanuary 10, 2007. He was not a member of the organization' s pension plan. Calculate the number of years eligible for the$1,500.00portion of a retiring allowance.
Answer: A
Explanation:
The special$1,500transfer eligibility connected to retiring allowances is based specifically onyears (or part- years) of service before 1989where the employee hadno vested employer pension/DPSP benefitsfor those years. CRA explains that, in addition to the $2,000-per-year pre-1996 rule, you can also transfer an additional
$1,500 for each year or part-year before 1989that meets the vesting condition.
Phan's employment began in1992, which isafter 1989. Because he haszeroservice before 1989, there areno years that can qualify for the $1,500 portion-regardless of whether he belonged to a pension plan.
Therefore, the number of eligible years for the$1,500component is0(option A). Payroll must base this calculation on actual service dates, including any related-employer service if applicable, but here the start date alone makes the $1,500 portion ineligible.
NEW QUESTION # 55
Helen is reimbursed for the cost of the protective clothing that is legally required for her job. The clothing she bought isnot supported by receiptsand is a reasonable reimbursement amount. This is considered:
Answer: D
Explanation:
Even though the question uses the word "reimbursed," the key fact isno receipts. In CRA terms, when an employee is paid a set amount or is not required to substantiate the expense, the payment functions like an allowance, not an accountable reimbursement. CRA's guidance on uniforms/special or protective clothing states these amounts aregenerally taxable, and only in specific circumstances under CRA administrative policy would they be non-taxable.
CRA interpretations also reinforce that where employeesdo not have to provide receipts, a clothing allowance is generally ataxable employment benefit; non-taxable treatment is linked to substantiation and meeting strict conditions (for example, safety footwear with receipts).
So, because Helen's payment isnot supported by receipts, it is best classified as ataxable allowance(option A). Payroll should include the amount in taxable income, apply required withholdings as applicable, and ensure policy/records support whatever treatment is used.
NEW QUESTION # 56
......
Top Rated Features of National Payroll Institute PF1 Practice Test Questions. The PassSureExam is committed to making the National Payroll Institute PF1 exam preparation journey simple, smart, and swift. To meet this objective the PassSureExam is offering PF1 practice test questions with top-rated features. These features are updated and real National Payroll Institute PF1 Exam Questions, availability of Payroll Fundamentals 1Exam PF1 exam real questions in three easy-to-use and compatible formats, three months free updated National Payroll Institute PF1 exam questions download facility, affordable price and 100 percent Payroll Fundamentals 1Exam PF1 exam passing money back guarantee.
PF1 Reliable Exam Pdf: https://www.passsureexam.com/PF1-pass4sure-exam-dumps.html
DOWNLOAD the newest PassSureExam PF1 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1vur4IOiNMJW9nGHrIlu-iOIXDwtVuPoG