Sorgen Sie noch um die Prüfungsunterlagen der CSI AFP-Exam-1? Jetzt brauchen Sie keine Sorgen! Weil uns zu finden bedeutet, dass Sie schon die Schlüssel zur Prüfungszertifizierung der CSI AFP-Exam-1 gefunden haben. Wir ExamFragen beschäftigen uns seit Jahren mit der Entwicklung der Software der IT-Zertifizierungsprüfung. Jetzt genießen wir einen guten Ruf weltweit. Wir bieten Ihnen die effektivsten Hilfe bei der Vorbereitung der CSI AFP-Exam-1.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Tax Planning | 14% | - Tax-Efficient Strategies - Tax Deductions and Credits - Registered Plans - Income Tax Fundamentals |
| Topic 2: Retirement Planning | 17% | - Pension Plans - Registered Retirement Savings Plans - Retirement Needs Analysis - Retirement Income Strategies |
| Topic 3: Investment Planning | 17% | - Portfolio Construction - Asset Allocation - Investment Theory - Investment Products |
| Topic 4: Asset and Liability Management | 11% | - Personal Balance Sheet Analysis - Debt Management - Cash Flow Management - Budgeting |
| Topic 5: Estate Planning | 13% | - Wills - Estate Transfer Strategies - Trust and Beneficiary Planning - Powers of Attorney |
| Topic 6: Client Relationship and Practice Management | 6% | - Client Discovery - Practice Management - Communication and Advisory Process |
| Topic 7: Risk Management and Insurance | 12% | - Life Insurance - Risk Transfer Strategies - Disability and Health Insurance - Risk Assessment |
| Topic 8: Professional Conduct and Regulatory Compliance | 10% | - Regulatory Requirements - Compliance Responsibilities - Ethics and Professional Standards |
Sind Sie auf CSI AFP-Exam-1 Zeritifizierungsprüfung bereit? Die Prüfungszeit ist angekommen. Sind Sie sehr selbstbewusst für die CSI AFP-Exam-1 Prüfungen? Wenn Sie nicht sehr Selbstbewusst, empfehlen wir Ihnen die ausgezeichneten Prüfungsunterlagen. Mit den neuesten AFP-Exam-1 Dumps von ExamFragen können Sie in sehr beschränkter Zeit diese Prüfung zu bestehen.
99. Frage
Consider the following information for a client's portfolio: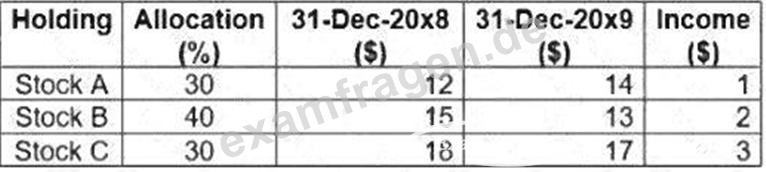
What is the annual rate of return for this portfolio?
Antwort: A
Begründung:
The portfolio return must combine price change and income for each holding, then weight each holding by its allocation. Stock A rises from $12 to $14 and pays $1 of income, producing a return of ($14 + $1 - $12) / $12
= 25%. Stock B falls from $15 to $13 but pays $2, producing a 0% total return. Stock C falls from $18 to $17 and pays $3, producing ($17 + $3 - $18) / $18 = 11.11%. Applying the allocation weights gives 30% × 25%, plus 40% × 0%, plus 30% × 11.11%, which is approximately 10.8%. The answer is not based only on market value movement and not on a simple average of the three returns. AFP investment calculations require total return and allocation weighting. Study Guide focus: portfolio return, income return, capital return, weighted averages, and performance measurement. This is why the answer is a weighted total-return figure, not a yield figure or a price-only performance measure.
100. Frage
Alexis has an index-linked GIC with an adjusted cost base of $20,500. The GIC was issued one year ago, has four years remaining to maturity and provides her with 60% participation in the gains of the S & P/TSX 60 Index, based on the level of the Index at maturity or at redemption prior to maturity. The GIC has a 2% fee if redeemed in the first two years. Alexis notices that the S & P/TSX 60 Index is up 25% and she would like to redeem her GIC. She asked her financial planner if she redeems her GIC, how much she would receive upon redemption. What will her financial planner tell her?
Antwort: C
Begründung:
The redemption calculation follows the participation formula and then applies the early redemption fee.
Alexis's adjusted cost base is $20,500. The S & P/TSX 60 is up 25%, and the GIC gives her 60% participation, so the credited gain is 15% of principal. That brings the value to $23,575 before charges.
Because the GIC is redeemed during the first two years, the 2% fee applies. Two percent of $23,575 is
$471.50, leaving approximately $23,104 after the fee. Option B ignores the participation cap and uses the full index gain. Option D calculates the participation gain but ignores the redemption charge. Option A ignores the positive index-linked value. This question tests structured-product mechanics: index participation does not equal full market exposure, and liquidity before maturity may carry explicit cost. Study Guide focus: index- linked GICs, participation rates, early redemption fees, ACB, and investment liquidity. The adviser should also explain that index-linked guarantees protect principal differently from direct equity ownership.
101. Frage
Francois and Brigitte are meeting with their financial planner, Robin. They would like to ensure that if one of them were to die suddenly that their mortgage would be paid in full. Their current mortgage has an outstanding balance of $400,000 with 10 years remaining. The couple are in good health and have a well- balanced financial plan that focuses on debt reduction and savings. Which type of insurance policy should Robin recommend to assist the couple in meeting their objective?
Antwort: D
Begründung:
A joint 10-year term first-to-die policy matches the couple's exact risk. Francois and Brigitte want the mortgage paid if one spouse dies suddenly, and the mortgage has 10 years remaining. First-to-die coverage pays on the first death, which is when the survivor would need funds to discharge the mortgage. A 10-year term aligns the coverage period with the debt. Last-to-die coverage is inappropriate because it pays only after both insured persons have died, too late to protect the survivor's mortgage obligation. Whole life coverage is permanent and more expensive than necessary for a temporary mortgage balance. Since the couple is healthy and already has a balanced plan, the planner should recommend efficient, purpose-built term insurance rather than over-insuring with a permanent policy. Study Guide focus: mortgage insurance needs, first-to-die coverage, term insurance, debt protection, and risk matching. The death benefit should be sized to the outstanding debt and reviewed as the mortgage is repaid.
102. Frage
Jelena, age 32, is single and works as a partner in a law firm. She is meeting with her financial planner, May, as she would like to start investing. Her friend John talks about hot sectors in the stock markets and has recently brought up the cannabis sector. She has done some reading about this sector and is willing to experience large decline in her investments. Jelena also mentioned to May that she believes in high long-term returns. What conclusion can May draw based on their discussions about the stock market and Jelena's expectations?
Antwort: D
Begründung:
Jelena has limited investment knowledge and limited investment experience. Reading about a hot sector and being willing to accept large losses does not establish investment competence. Knowledge requires understanding risk, diversification, valuation, volatility, liquidity, taxation, and how a sector investment fits an overall portfolio. Experience requires actual investing history through different market conditions. The facts show interest in cannabis stocks and belief in high long-term returns, but no demonstrated track record or technical understanding. A planner should not equate confidence with knowledge or willingness with capacity. May should use this discovery to educate Jelena, assess risk tolerance and risk capacity separately, and avoid concentrated speculative recommendations unless they are suitable within a properly diversified plan. Option A and B overstate her knowledge, and option C invents experience not present in the facts. Study Guide focus: investment knowledge, investment experience, behavioural risk, sector concentration, and suitability. The proper planning response is education and diversification, not a conclusion that she is ready for concentrated speculation.
103. Frage
A financial planner, Rachel, is preparing to recommend a discretionary portfolio manager to her client. The portfolio manager is owned by Rachel's former employer, and Rachel receives no referral fee. However, the former employer regularly sends new clients to Rachel's practice. What should Rachel do before making the recommendation?
Antwort: D
Begründung:
Course-guide reasoning starts with the conflict, not the commission. A conflict exists when a planner's judgment could reasonably be influenced by a relationship, incentive, expectation, or business arrangement.
Rachel's former employer may not pay her directly, but the reciprocal referral pattern creates a benefit that could affect, or appear to affect, objectivity. Professional conduct requires timely disclosure in plain language before the client acts on the recommendation. Disclosure should explain the relationship, the nature of the benefit, and how Rachel will continue to act in the client's interest. Option A is too narrow because conflicts are not limited to cash compensation. Option C is unnecessarily defensive; a conflicted recommendation may still be made if it is suitable and properly managed. Option D does not cure the conflict because acknowledging investment risk is different from understanding adviser bias. The defensible action is written disclosure, suitability analysis, and clear documentation. References/topics: conflicts of interest, disclosure obligations, objectivity, professional conduct.
104. Frage
......
Manchmal muss man mit große Menge von Prüfungsaufgaben üben, um eine wichtige Prüfung zu bestehen. Die CSI AFP-Exam-1 von uns hat diese Forderung gut erfüllt. Und mit den fachlichen Erklärungen können Sie besser die Antworten verstehen. Die Demo der CSI AFP-Exam-1 von unterschiedlichen Versionen werden von uns gratis angeboten. Probieren Sie mal und wählen Sie die geeignete Version für Sie! Mit unserer gemeinsamen Arbeit werden Sie bestimmt die CSI AFP-Exam-1 Prüfung erfolgreich bestehen!
AFP-Exam-1 Musterprüfungsfragen: https://www.examfragen.de/AFP-Exam-1-pruefung-fragen.html