DOWNLOAD the newest PrepAwayPDF ClaimCenter-Business-Analysts PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1pza3Y98cYA3q4IRDM3_BOVdnQ3_pSmqg
After choosing ClaimCenter-Business-Analysts training engine, you will surely feel very pleasantly surprised. First of all, our ClaimCenter-Business-Analysts study materials are very rich, so you are free to choose. At the same time, you can switch to suit your learning style at any time. Because our ClaimCenter-Business-Analysts learning quiz is prepared to meet your diverse needs. If you are not confident in your choice, you can seek the help of online services.
| Certification Vendor: | Guidewire |
|---|---|
| Exam Name: | ClaimCenter Business Analyst - Mammoth Proctored Exam |
| Exam Number: | ClaimCenter-Business-Analysts |
| Related Certifications: | Guidewire InsuranceSuite Analyst Certification |
| Exam Format: | Multiple Choice, Multiple Select, Scenario-based Questions |
| Available Languages: | English |
| Real Exam Qty: | 50-70 (varies by version) |
| Exam Registration: | Guidewire Education Portal |
| Sample Questions: | Guidewire ClaimCenter-Business-Analysts Sample Questions |
| Exam Way: | Online proctored (Mammoth Proctored Exam) |
| Pre Condition: | Recommended: Guidewire InsuranceSuite Analyst foundational training (no strict formal prerequisite publicly specified) |
>> Examcollection ClaimCenter-Business-Analysts Dumps <<
Our ClaimCenter-Business-Analysts training materials are excellent. The quality is going through official authentication. So your money paid for our ClaimCenter-Business-Analysts practice engine is absolutely worthwhile. In addition, you are advised to invest on yourselves. After all, no one can be relied on except yourself. And you can rely on our ClaimCenter-Business-Analysts learning quiz. We can claim that if you study with our ClaimCenter-Business-Analysts exam questions for 20 to 30 hours, then you are bound to pass the exam for we have high pass rate as 98% to 100%.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
| Topic 5 |
|
NEW QUESTION # 38
Losses incurred because of an accident with other vehicles can be very large. Because of the risk of large losses, all claims must include both a police report and the details of any passengers in the vehicle, whether they sustained injuries or not. The claim must show whether there were passengers in the vehicle at the time of the accident. Succeed wants the ability to include a very detailed description of the loss event information on intake of the claim.
When the claim is created, Succeed wants to flag the claim with a reminder for the Adjuster to contact the insured.
There should be reminders for the Adjuster to complete the following items for every new claim created:
. Review any photographs of the accident
. Contact and Interview each passenger
. Collect statements from each witness
. Record the vehicle's mileage
Which business requirement is based on assumptions?
Answer: D
Explanation:
In the context of business requirements analysis, an assumption is a statement that is accepted as true or certain to happen without proof.
* Why A is the correct answer:The requirement to generate a reminder to "review any photographs" for everynew claim assumes that photographs will be available for every accident. In reality, photos are not always taken or provided at the First Notice of Loss (FNOL). Creating a mandatory task for an optional piece of evidence is based on the assumption of data availability.
* Why D is incorrect:"All claims must include a police report..." is aBusiness Ruleor constraint. It is a mandatory condition imposed by the business ("must include") rather than an assumption about what is currently present.
* Why B is incorrect:Contacting the insured is a standard, universal step in the claims process that applies to every claim, so it is not considered an assumption.
NEW QUESTION # 39
Succeed Insurance has plans to expand operations in Greeley, Colorado. Due to a history of hailstorm related damage in the area, the company plans to offer reimbursement for hail damage as an option.
Which two actions should the Business Analyst (BA) take to determine the requirements for the project?
(Choose two.)
Answer: A,C
Explanation:
In the Guidewire delivery methodology, the "Determine Requirements" phase (often part of Inception or Elaboration) focuses on understanding the business need and mapping it to the software capabilities.
* Lead an Elaboration Workshop (A):TheElaboration Workshopis the primary forum where BAs engage with stakeholders (like the Greeley operations team) to discuss the specific needs for the new
"hail damage" product. This is where the raw requirements are gathered, discussed, and refined.
* Recommend Base Product Features (B):A critical responsibility of the Guidewire BA is to maximize product value by reducing unnecessary customization. When determining requirements for
"reimbursement" and "hail damage," the BA should immediately demonstrate and recommend how ClaimCenter's out-of-the-box Coverage, Exposure, and Incident features can handle this scenario. This aligns the customer's expectations with the standard software capabilities, expediting the implementation.
* Why not C or D?Authoring user stories (C) and defining typelists (D) areoutputsortasksthat occurafter the requirements have been determined and the solution approach (Standard vs. Custom) has been agreed upon.
NEW QUESTION # 40
Succeed Insurance requires that a new 'Driver under 18?' field be added to the vehicle incident screen for personal auto claims to indicate whether or not the driver of the vehicle was a minor when the loss occurred.
The field will be set by calculating the driver's age using the date of loss and the driver's date of birth.
There are two validation requirements:
* The field must be set if the 'Date of Birth' field for the driver is not null.
* No payments can be made for collision exposures if the 'Date of Birth' field for the driver of the vehicle is null.
A Business Analyst (BA) documents the validation requirements in the validation tab of the User Story Card
'Adjudicate - Update Maintain Vehicle Incident for Personal Auto Claims' as shown in the exhibit.
What information in the two validation examples is either missing or incorrectly documented? (Choose two.)
Answer: B,D
Explanation:
The User Story Card exhibit contains several documentation errors when compared to standard Guidewire requirements gathering best practices and the specific scenario provided.
* Missing Requirement Number and Logic Gap (Option C):
* Traceability:In the second row of the exhibit (the payment validation rule), the "Requirement Number" column is completely blank. Traceability back to the original requirements document is mandatory for all entries.
* Logic Precision:The requirement explicitly states that the rule applies to"personal auto claims"
. However, the logic documented in the "Rules" column (If Exposure Type = VehicleDamage Then Block...) doesnotcheck the Policy Type. It relies solely on the Exposure Type, which could exist on Commercial Auto policies as well. To accurately reflect the business requirement, the condition If PolicyType = Personal Auto must be added (similar to how it was done in the first row).
* Missing DV/LV Context for Validation (Option D):
* UI Anchoring:The second requirement is a validation rule that triggers an error ("Driver's Date of Birth is required..."). For the system to highlight the specific field on the screen (the "Driver Date of Birth" widget) when the error occurs, the rule must be associated with the specificDetail View (DV)orList View (LV)where that field resides (e.g., VehicleIncidentDV). The exhibit lists
"Not Applicable" in the "Name of DV or LV" column. This is incorrect because providing the DV name ensures the error message is displayed contextually next to the field rather than as a generic page-level error, improving the user experience.
Why other options are incorrect:
* Option A:The LOB column is used for filtering, reporting, and release management. Even if the rule logic checks the policy type, the LOB column is required metadata and should not be removed.
* Option B:While the first requirement (the calculation) lacks a DV name (which it should have), it is a Business Rule(assignment), not a validation. Therefore, it doesnotgenerate an error or warning message for the user, so the second part of Option B is incorrect.
* Option E:The "Rules" column is exactly where the calculation logic (Date of Loss - Date of Birth) belongs. The developer needs this information to implement the automation.
NEW QUESTION # 41
Succeed Insurance handles a small volume of asbestos claims in their legacy system. These claims can remain open for many years to cover medical costs to claimants due to illnesses caused by exposure to asbestos in the workplace.
Succeed has the following requirements for paying these claims with the New Check Wizard:
. No indemnity (claim cost) payments can be made until a medical assessment of the claimant is completed.
. Expense payments can be made to cover Succeed's costs to process the claim.
Which feature in the base product can be extended to support both of these requirements?
Answer: A
Explanation:
250 to 350 words From Exact Extract of Guidewire ClaimCenter Business Analyst documentation:
The requirement to block specific types of payments (Indemnity) while allowing others (Expenses) based on the status of claim data (Medical Assessment) is best handled by Validation Rules at the Ability to Pay level.
* Ability to Pay (Option D):In Guidewire ClaimCenter, the "Ability to Pay" is a specificValidation Level. When a user attempts to issue a check, the system runs a set of validation rules to ensure the claim has reached a sufficient level of maturity and data completeness. This is the "gatekeeper" for payments.
* How it works for this scenario:A Business Analyst can define a validation rule at the "Ability to Pay" level that states:"If the Payment Type is Indemnity AND the Medical Assessment is incomplete, then raise an error."
* Why it fits:This logic perfectly satisfies both requirements.
* It blocks Indemnity payments if the assessment is missing.
* It implicitly allows Expense payments to proceed because the rule only checks for Indemnity payments.
Why other options are incorrect:
* Authority Limits (A)control theamountof money a user can approve, not the prerequisites for payment.
* Transaction Approval Rules (B)are used to route checks for supervisory review based on criteria, not to block them entirely due to missing data.
* Financial Holds (C)are generally applied to a whole claim or exposure to suspendallpayments (or broadly all payments of a certain category). While possible to configure, they are less flexible than Validation Rules for checking specific data fields like "Medical Assessment" dynamically during the check wizard process.
NEW QUESTION # 42
An Adjuster at Succeed Insurance is handling a homeowners claim with a dwelling exposure for damage to the insured's home. The Adjuster's Authority Limit Profile has the following limits: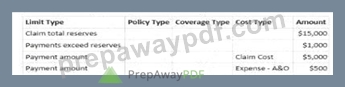
The table below is a view of the property claims organization within Succeed Insurance. The Adjuster is a member of the group Property - Team A.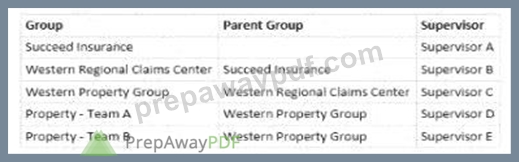
The Adjuster creates a payment in the amount of $6,500 for repairs to the insured's home. How will it be processed assuming that the claim has sufficient reserves for the payment?
Answer: D
Explanation:
This scenario involves checking financial Authority Limits and determining the correct Approval Routing hierarchy in Guidewire ClaimCenter.
* Check Authority Limits:First, compare the transaction amount against the user's specific limits.
* The payment is for "repairs to the insured's home," which is classified asClaim Cost(Indemnity).
* According to the provided Authority Limit Profile, the Adjuster has a "Payment amount" limit of
$5,000for Claim Cost.
* The transaction amount is$6,500.
* Since$6,500 > $5,000, the limit is exceeded, meaning the paymentrequires approval(Ruling out Option B).
* Determine Routing:When a financial transaction requires approval, ClaimCenter routes the approval activity to the supervisor of the group to which the user belongs.
* The Adjuster is a member ofProperty - Team A.
* According to the Organization chart provided, the Supervisor for "Property - Team A" is Supervisor D.
* Therefore, the system will generate an approval activity and assign it specifically to Supervisor D). Supervisor C is the manager of theparentgroup (Western Property Group), so the activity would only go to them if Supervisor Dalsolacked the authority to approve the $6,500, requiring further escalation. However, the initial routing is always to the immediate supervisor.
Why other options are incorrect:
* Option A:Supervisor C is the "Grand-boss" (Supervisor of the parent group), not the immediate supervisor.
* Option B:The amount ($6,500) clearly exceeds the defined limit ($5,000), so automatic processing is impossible.
* Option C:Supervisor A is at the top of the hierarchy (Succeed Insurance), far removed from the initial approval step.
NEW QUESTION # 43
......
Real ClaimCenter-Business-Analysts Exam Answers: https://www.prepawaypdf.com/Guidewire/ClaimCenter-Business-Analysts-practice-exam-dumps.html
P.S. Free & New ClaimCenter-Business-Analysts dumps are available on Google Drive shared by PrepAwayPDF: https://drive.google.com/open?id=1pza3Y98cYA3q4IRDM3_BOVdnQ3_pSmqg