What's more, part of that Actual4Exams PF1 dumps now are free: https://drive.google.com/open?id=1h65Dbj-G1QX9VOVoyUcM4DIu8TEXXvD2
The go-to resource for effective and efficient National Payroll Institute exam preparation is Actual4Exams National Payroll Institute PF1 practice material in three formats. Our updated National Payroll Institute questions are available in these three different formats: web-based practice test, desktop practice exam software, and National Payroll Institute PDF file of real exam questions. The goal of these formats is to aid test candidates in preparing for the National Payroll Institute PF1 test according their styles.
| Section | Objectives |
|---|---|
| Topic 1: Payroll Records and Compliance Reporting | - Government reporting
|
| Topic 2: Earnings, Deductions, and Taxation | - Types of earnings
|
| Topic 3: Payroll Fundamentals and Compliance Framework | - Payroll system overview in Canada
|
The PF1 Exam Dumps are compiled by experienced experts, they are quite familiar with the development the exam and they are also the specialists of the field. Besides the price of tPF1 exam braindumps are reasonable, no matter you are students or employees, you can afford it. Pass guarantee and money back guarantee for failure of your exams. We also offer you free update for 365 days, the update version will send to your email automatically.
NEW QUESTION # 42
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
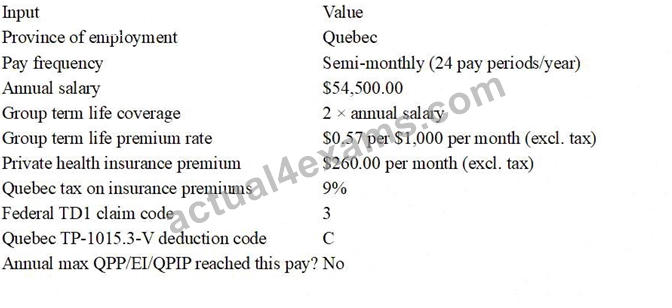
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases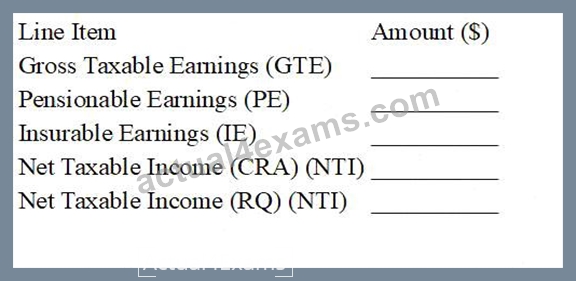
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
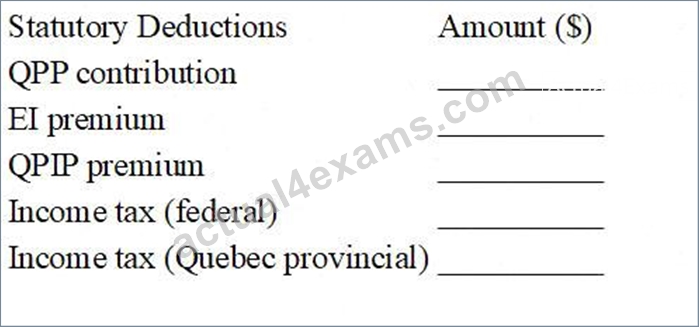
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
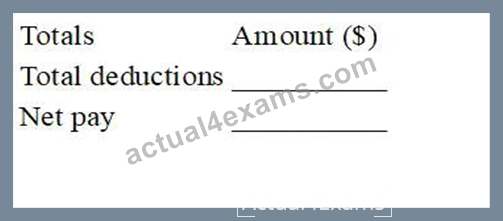
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
NEW QUESTION # 43
An organization pays the premiums for a sickness or accident plan for their president only. This would be considered:
Answer: C
Explanation:
Because the plan is for the president only, it is a non-group insurance plan (a plan offered to an individual employee). The CRA states that when an employer pays premiums or makes contributions to a non-group insurance plan, the amounts paid are a taxable benefit. The CRA explicitly includes sickness or accident, disability, and income maintenance plans in this non-group category.
This benefit is generally treated as a non-cash taxable benefit because the employer is paying the premium directly to the insurer (the employee receives the coverage, not cash). CRA guidance distinguishes cash benefits (paid as money, reimbursements, or allowances) from benefits provided in a manner other than cash.
Payroll must therefore include the value of the employer-paid premium in the employee's taxable income and report it on the appropriate slip (commonly T4 code 40 for current employees, as noted in CRA instructions for insurance premiums).
NEW QUESTION # 44
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)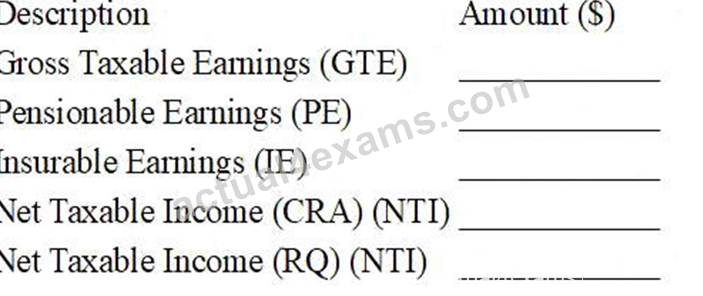
STATUTORY DEDUCTIONS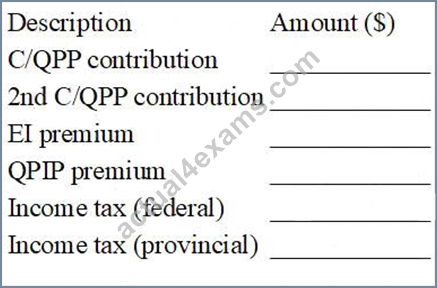
OTHER DEDUCTIONS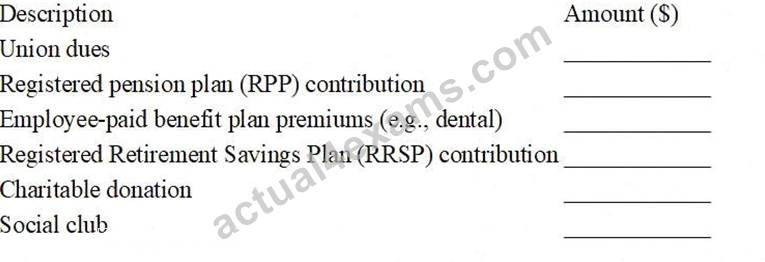
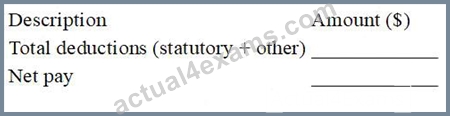
Given Data (Reference)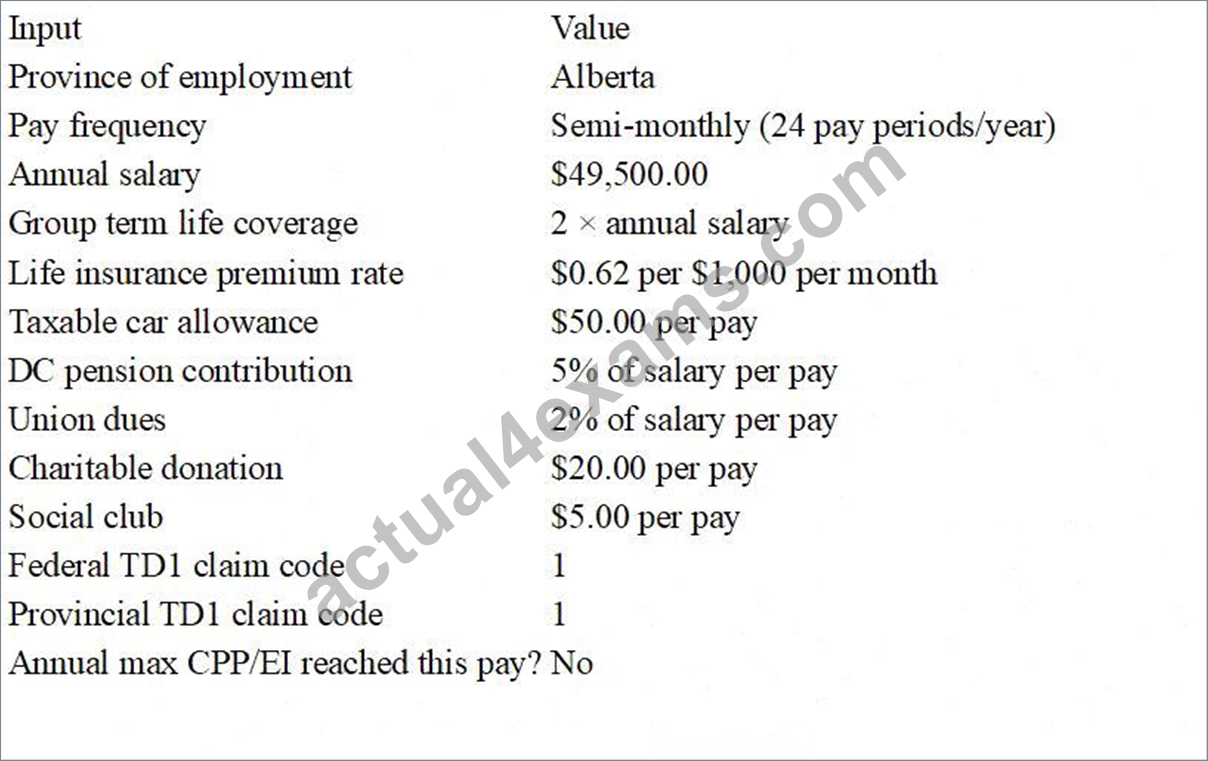
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
NEW QUESTION # 45
A death benefit is a:
Answer: C
Explanation:
The CRA defines a death benefit as the gross amount of any payment made on or after the death of an employee to recognize the employee's service in an office or employment. It can be paid to a surviving spouse
/common-law partner, heir, or the estate.
This is different from amounts the employee already earned before death (for example, regular wages up to the date of death, or vacation pay that was accrued/earned). CRA guidance treats wages and employment income earned up to and including the date of death as amounts to be reported on a T4 slip, not as a death benefit.
It's also different from a life insurance payout from an insurer (which is not an employer-paid "death benefit" for payroll reporting purposes). The payroll impact is that a qualifying death benefit is generally reported as a special payment (often on a T4A), following CRA rules for deductions and reporting of death benefits.
NEW QUESTION # 46
Which of the following types of earnings are not considered income from employment?
Answer: A
Explanation:
Regular salary, vacation pay, and commissions are generally treated as income from employment because they are amounts paid for services performed during employment. In contrast, what many people call
"severance pay" is often classified by the CRA as a retiring allowance-an amount paid when or after an employee retires or loses their job, in recognition of long service or for the loss of employment.
This distinction matters in payroll because a retiring allowance has its own rules for withholding and potential RRSP/RPP transfer eligibility, and it is not treated the same way as normal employment income earned while actively employed. CRA technical guidance also draws lines between amounts that are employment income versus retiring allowance depending on the nature/timing of the payment.
So, among the options listed, severance pay (when it is a retiring allowance) is the one that is not considered income from employment in the way salary/vacation pay/commissions are.
NEW QUESTION # 47
......
The pass rate is 98% for PF1 training materials, and our exam materials have gained popularity in the international for its high pass rate. If you choose us, we can ensure that you can pass your exam just one time. In addition, PF1 exam dumps are high-quality, and you can use it with ease. You can obtain PF1 exam materials within ten minutes, and if you don’t receive, you can email to us, and we will solve this problem for you immediately. You can enjoy the free update for 365 days after purchasing, and the update version for PF1 Exam Braindumps will be sent to you automatically, you just need to exam your email and change your practicing ways according to the new changes.
PF1 Trustworthy Exam Torrent: https://www.actual4exams.com/PF1-valid-dump.html
P.S. Free 2026 National Payroll Institute PF1 dumps are available on Google Drive shared by Actual4Exams: https://drive.google.com/open?id=1h65Dbj-G1QX9VOVoyUcM4DIu8TEXXvD2