What's more, part of that VCEEngine PF1 dumps now are free: https://drive.google.com/open?id=1rQhh4TyILceOjuN_xDZ4bDIbcSg0kFAb
If you have any question about our PF1 test torrent, do not hesitate and remember to contact us. we are glad to help you solve your problem. If you buy our Payroll Fundamentals 1Exam guide torrent and take it seriously consideration, you will find you can take your exam after twenty to thirty hours’ practice. So come to buy our PF1 Test Torrent, it will help you pass your exam and get the certification in a short time that you long to own.
| Section | Objectives |
|---|---|
| Topic 1: Earnings, Deductions, and Taxation | - Types of earnings
|
| Topic 2: Payroll Fundamentals and Compliance Framework | - Payroll system overview in Canada
|
| Topic 3: Payroll Records and Compliance Reporting | - Recordkeeping requirements
|
The pass rate is 98.75% for PF1 study materials, and if you choose us, we can ensure you that you can pass the exam just one time. PF1 exam dumps are high-quality and high accuracy, since we have a professional team to compile and examine the questions and answers. What’s more, PF1 exam materials have both questions and answers, and you can check your answers very conveniently after practicing. We offer you free update for one year for PF1 Study Materials, and our system will send the latest version to your email address automatically, and you need to receive and change your learning ways according to the latest version.
NEW QUESTION # 13
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
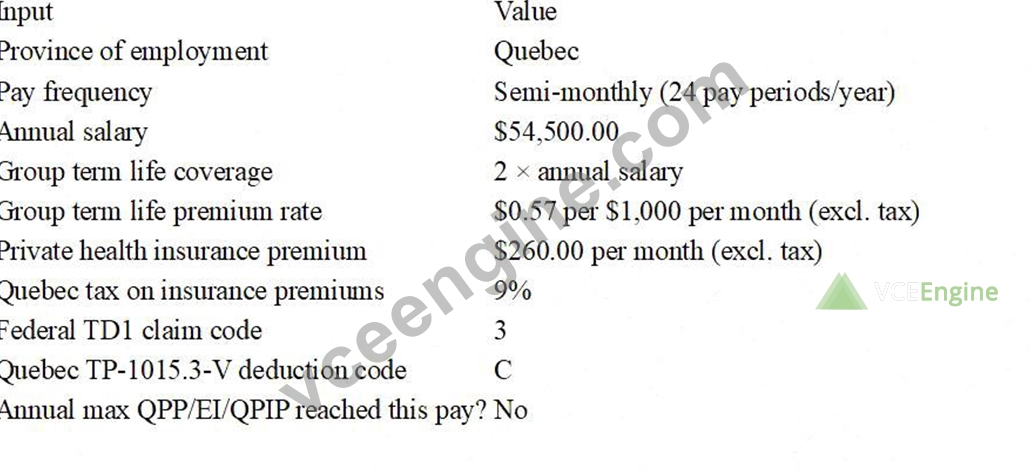
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
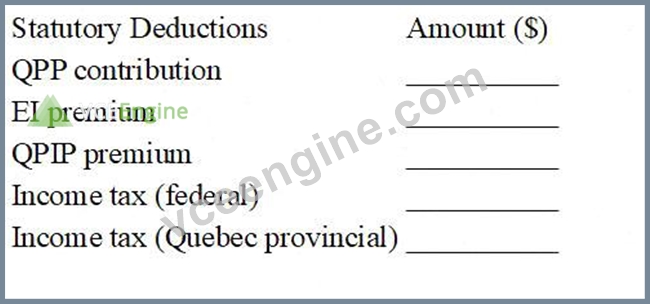
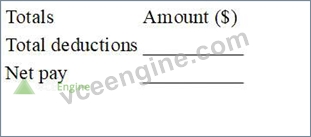
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases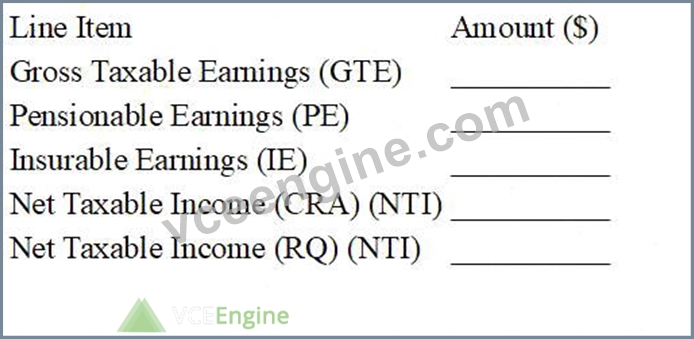
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
NEW QUESTION # 14
Matt earns $10.10 per hour and works 37.5 hours per week. Calculate Matt's regular bi-weekly earnings.
Answer:
Explanation:
$757.50
Explanation:
Regular earnings for an hourly employee are calculated as hourly rate × hours worked. Because "bi-weekly" means two weeks of work paid together, you calculate one week's regular earnings and then multiply by two (assuming the hours are the same each week and there is no overtime premium indicated).
Step 1: Weekly regular earnings:
$10.10 × 37.5 hours = $10.10 × 37 + $10.10 × 0.5
= $373.70 + $5.05
= $378.75.
Step 2: Bi-weekly regular earnings (2 weeks):
$378.75 × 2 = $757.50.
So Matt's regular bi-weekly earnings are $757.50.
In payroll documentation, "regular earnings" are the employee's base wages before statutory deductions (CPP
/QPP, EI, income tax) and before other deductions, and they exclude any separately calculated earnings like overtime premiums or taxable benefits unless stated. This approach (rate × hours, then adjust for pay period) is the standard method used to compute gross/regular pay for hourly employees before moving on to deductions and net pay.
NEW QUESTION # 15
Duncan Drapak was employed in Ontario. Upon termination of his employment, he will be paid $7,760.00 legislated wages in lieu of notice together with his final weekly pay of $875.00. Calculate Duncan's Canada Pension Plan (CPP) contribution if the yearly maximum contribution will not be exceeded.
Answer:
Explanation:
$509.78
Explanation:
Legislated wages in lieu of notice are treated as pensionable employment earnings for CPP purposes, so they are included with the employee's final regular pay when calculating CPP deductions (assuming no CPP exemption applies).
Step 1: Determine total pensionable earnings for the week:
$7,760.00 + $875.00 = $8,635.00.
Step 2: Subtract the CPP basic exemption (Year's Basic Exemption is $3,500 annually). For a weekly payroll, the basic exemption is prorated:
$3,500 ÷ 52 = $67.31.
CPP contributory earnings for the week:
$8,635.00 # $67.31 = $8,567.69.
Step 3: Apply the 2026 CPP employee contribution rate of 5.95% (base CPP). The question states the annual maximum will not be exceeded, so no capping is required in this calculation.
CPP contribution:
$8,567.69 × 5.95% = $509.7777..., rounded to $509.78.
NEW QUESTION # 16
Paula is granted a pay increase. The paperwork informing the payroll department of the pay increase is two pay periods late. What method would be used to calculate income taxes on the separate retroactive payment?
Answer: C
Explanation:
A payment made to "catch up" wages because a pay increase was processed late is a retroactive payment. The CRA provides different income tax calculation approaches depending on the payment type and specifically lists "Retroactive payments" as its own category, separate from regular tax-table calculations, lump-sum, and bonus/irregular methods.
For bonuses and retroactive pay increases, the CRA also points employers to the Payroll Deductions Online Calculator (PDOC) to calculate CPP, EI, and income tax correctly, which aligns with using the appropriate CRA method for retroactive amounts.
Because this situation is explicitly a retroactive adjustment (two pay periods late), the correct choice is the Retroactive tax method (option C), not the bonus/irregular method, not the lump-sum method, and not the regular tax tables.
NEW QUESTION # 17
Ronda earns $12.50 per hour and worked 40 hours this week. Calculate her Canada Pension Plan (CPP) contribution for this weekly pay period.
Answer:
Explanation:
$25.75
Explanation:
First calculate Ronda's pensionable earnings for the week. Her gross pay is:
$12.50 × 40 = $500.00.
CPP is calculated on pensionable earnings after subtracting the basic exemption (the Year's Basic Exemption, YBE), prorated to the pay period. The CRA confirms the YBE is $3,500 and the employee CPP contribution rate for 2026 is 5.95% for base CPP.
Weekly exemption = $3,500 ÷ 52 = $67.31 (rounded to cents).
Pensionable earnings subject to CPP this week = $500.00 # $67.31 = $432.69.
CPP contribution = $432.69 × 5.95% = $432.69 × 0.0595 = $25.745..., which rounds to $25.75.
This deduction continues each pay until the employee reaches the annual CPP maximum contribution for the year (at which point CPP stops for the remainder of the year).
NEW QUESTION # 18
......
The study material provided to the customers is available in three different formats. The first one is PDF (Portable Document Format). It is commonly used for quick preparation. Customers can access the National Payroll Institute PF1 Pdf Dumps anywhere anytime on their smartphones, tablets, and laptops to prepare for National Payroll Institute PF1 certification exam in a short time.
PF1 Verified Answers: https://www.vceengine.com/PF1-vce-test-engine.html
BTW, DOWNLOAD part of VCEEngine PF1 dumps from Cloud Storage: https://drive.google.com/open?id=1rQhh4TyILceOjuN_xDZ4bDIbcSg0kFAb