What's more, part of that Dumpcollection PF1 dumps now are free: https://drive.google.com/open?id=1sY7aUde_aFw_r12dvcg7NsTHyXysRwV2
One of the main unique qualities of the Dumpcollection National Payroll Institute Exam Questions is its ease of use. Our practice exam simulators are user and beginner friendly. You can use Payroll Fundamentals 1Exam (PF1) PDF dumps and Web-based software without installation. Payroll Fundamentals 1Exam (PF1) PDF questions work on all the devices like smartphones, Macs, tablets, Windows, etc.
| Section | Weight | Objectives |
|---|---|---|
| Individual Pay Calculations | 40% | - Regular earnings
|
| Communication and Compliance | 10% | - Accuracy and documentation
|
| Record of Employment (ROE) | 20% | - Submission and deadlines
|
| Termination and Special Payments | 30% | - Leaves and absences
|
After our practice materials were released ten years ago, they have been popular since then and never lose the position of number one in this area. Our PF1 practice quiz has authority as the most professional exam material unlike some short-lived PF1 Exam Materials. Targeting exam candidates of the exam, we have helped over tens of thousands of exam candidates achieved success now. So you can be successful by make up your mind of our PF1 training guide.
NEW QUESTION # 15
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
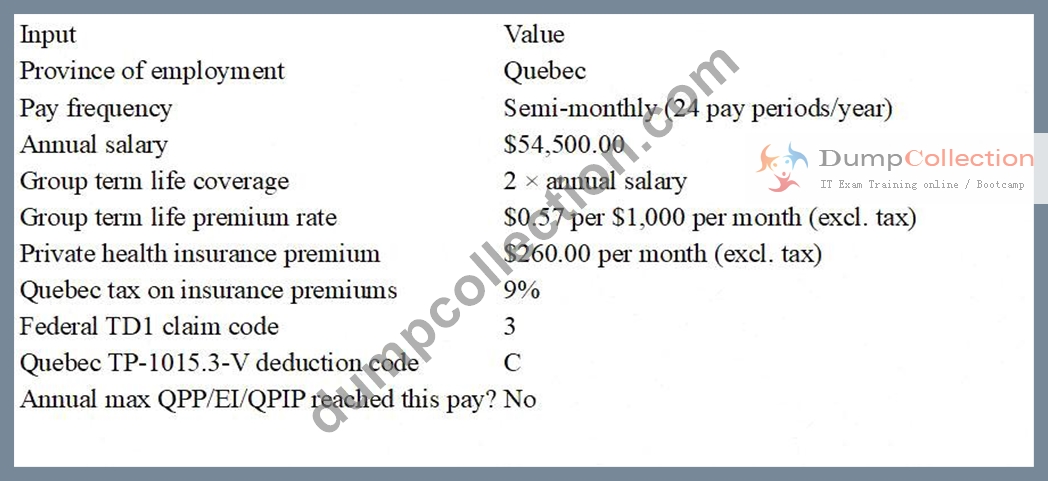
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases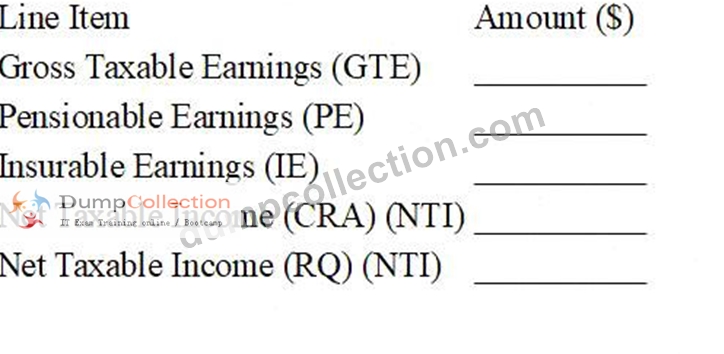
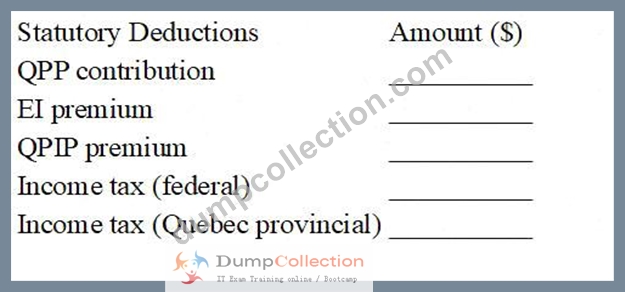
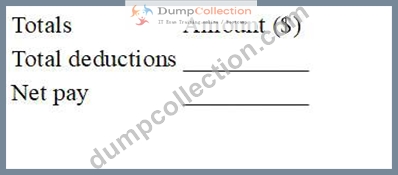
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
NEW QUESTION # 16
Bonus and incentive pays are subject to which statutory deductions?
Answer: C
Explanation:
Bonuses and incentives are treated as taxable remuneration, so they are generally subject to the same core statutory deductions as regular earnings: CPP/QPP, EI, and income tax (and in Quebec, QPIP also applies when the remuneration is subject to EI). The CRA specifically notes that you must deduct EI premiums from bonuses/retroactive pay (up to the annual maximum), and the CRA's guidance for bonuses/irregular amounts uses tools (PDOC/formulas) that calculate CPP contributions, EI premiums, and income tax on these payments.
In Quebec payroll, remuneration that is subject to EI premiums is generally also subject to QPIP premiums, so bonuses/incentives that are EI-insurable are typically QPIP-insurable as well.
In the Northwest Territories and Nunavut, there is also a statutory territorial payroll tax that employers must withhold/remit where applicable, and the NWT guidance explicitly lists bonuses as part of employment income subject to payroll tax.
NEW QUESTION # 17
The authorization for hiring form should contain a checklist to ensure the organization obtains all required information. What is an example of an item that could be on that checklist?
Answer: A
Explanation:
A hiring authorization package/checklist typically ensures the organization collects the documents needed to onboard the employee and set them up correctly in payroll and HR systems. This often includes items like an offer letter, signed policies, banking details for direct deposit, emergency contacts, and required HR/legal acknowledgements. A confidentiality agreement is a common onboarding document because it protects the employer's confidential information and can be required regardless of payroll deductions.
The other options are not good examples of "required information" for all new hires. Employees do not give
"consent" for statutory deductions-deductions like CPP, EI, and income tax withholding are required by law and employers must withhold them when applicable. A "clearance certificate" is not a standard universal onboarding requirement for payroll in Canada. A T1213 is only completed in special situations where an employee requests CRA authorization to reduce tax withheld at source; it is not something most new hires must provide.
NEW QUESTION # 18
Elodie is paid her commissions together with her bi-weekly salary of $1,000.00. This pay period her commissions are $4,300.00. Calculate her Quebec Pension Plan (QPP) contribution for this pay period.
Answer:
Explanation:
$325.42
Explanation:
Because Elodie is subject to QPP, her pensionable earnings for the pay period include both salary and commissions (both are pensionable employment earnings, assuming no exemptions apply). First, determine total pensionable earnings for the bi-weekly pay:
$1,000.00 + $4,300.00 = $5,300.00.
For 2026, Revenu Quebec shows the QPP basic exemption is $3,500 annually and the (employee) QPP contribution rate on earnings up to the maximum pensionable earnings is 6.30%.
Payroll applies the exemption per pay period. For bi-weekly pay (26 pay periods):
$3,500 ÷ 26 = $134.62 (rounded to cents).
Pensionable earnings subject to QPP this pay:
$5,300.00 # $134.62 = $5,165.38.
QPP contribution:
$5,165.38 × 6.30% = $5,165.38 × 0.063 = $325.41894, which rounds to $325.42.
NEW QUESTION # 19
Ursula is 17 years old, works in Quebec and earns $750.00 weekly. Ursula pays weekly union dues of $18.00 along with a special weekly union assessment of $10.00 for construction of a new union hall for its members.
Ursula also has registered pension plan (RPP) contributions of $20.00 deducted from each pay. Calculate Ursula's net federal taxable income.
Answer:
Explanation:
$712.00
Explanation:
For payroll income tax purposes, net taxable income starts with the employee's gross taxable income and then subtracts only those deductions that are deductible for income tax and can be recognized at source. CRA payroll guidance shows this approach by subtracting items such as RPP contributions and union dues when determining net taxable income for calculating income tax deductions.
Gross taxable income (weekly): $750.00.
RPP contributions are deductible (the amounts reported from box 20 of the T4 are generally deductible).
Regular union dues are deductible; however, the CRA states that deductible annual union/professional dues do not include special assessments or charges for anything other than ordinary operating costs. A levy specifically for constructing a new union hall is a special assessment, so it is not deductible as union dues.
So the deductions that reduce federal taxable income here are: $18.00 (union dues) + $20.00 (RPP) = $38.00.
Net federal taxable income = $750.00 # $38.00 = $712.00.
NEW QUESTION # 20
......
Obtaining this PF1 certificate is not an easy task, especially for those who are busy every day. However, if you use our PF1 exam torrent, we will provide you with a comprehensive service to overcome your difficulties and effectively improve your ability. If you can take the time to learn about our PF1 Quiz prep, I believe you will be interested in our PF1 exam questions. Our PF1 learning materials are practically tested, choosing our PF1 exam guide, you will get unexpected surprise.
Reliable PF1 Study Notes: https://www.dumpcollection.com/PF1_braindumps.html
P.S. Free 2026 National Payroll Institute PF1 dumps are available on Google Drive shared by Dumpcollection: https://drive.google.com/open?id=1sY7aUde_aFw_r12dvcg7NsTHyXysRwV2