What's more, part of that Itbraindumps AFP-Exam-1 dumps now are free: https://drive.google.com/open?id=15SFfbBJRVcIntt4W5fbz-n1fMgfwsAol
You can get an idea about the actual AFP-Exam-1 test pattern and AFP-Exam-1 exam questions. It will also assist you to enhance your CSI AFP-Exam-1 exam time management skills. You can easily use all these three AFP-Exam-1 exam questions format. These formats are compatible with all devices, operating systems, and the latest browsers. All three CSI AFP-Exam-1 Exam Questions formats are easy to use and compatible with all devices, operating systems, and the latest browsers.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Enabling Competencies | 16% | - Professional Conduct and Regulatory Compliance - Client Relationship and Practice Management |
| Topic 2: Technical Competencies | 84% | - Tax Planning - Asset and Liability Management - Retirement Planning - Risk Management and Insurance - Investment Planning - Estate Planning |
>> AFP-Exam-1 Exam Testking <<
In order to make you have a deeper understanding of what you are going to buy, we offer you free demo for AFP-Exam-1 training materials. We recommend you have a try before buying. If you are quite content with the AFP-Exam-1 training materials, just add them into your cart and pay for them. You will get the downloading link and password and you can start your learning right now. In addition, we have online and offline chat service stuff who possess the professional knowledge of the AFP-Exam-1 Exam Dumps, if you have any questions, just contact us.
NEW QUESTION # 59
Janet's non-registered account holds the funds listed in the following table: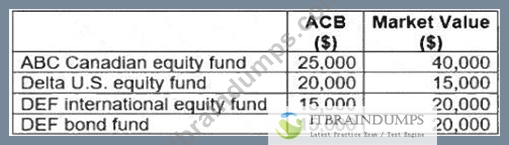
Assuming a marginal tax rate of 45%, what amount of tax payable will Janet incur if she redeems the account to fund the purchase of a new business?
Answer: D
Explanation:
Janet's taxable result comes from the net realized capital gain, not from the total market value redeemed. The ABC Canadian equity fund has a $15,000 gain, the Delta U.S. equity fund has a $5,000 loss, the DEF international equity fund has a $5,000 gain, and the DEF bond fund has a $5,000 gain. Net capital gains are therefore $20,000 after offsetting the Delta loss. Only one-half of the net capital gain is taxable under the standard capital gains inclusion treatment used in AFP-level calculations, producing a $10,000 taxable capital gain. At a 45% marginal tax rate, the tax payable is $4,500. Option A taxes the full net gain; option C and option D reflect incorrect inclusion or arithmetic assumptions. The purpose of the question is to test disposition analysis in a non-registered account and the sequence of gain/loss netting before applying the marginal rate. Study Guide focus: adjusted cost base, fair market value, capital gains inclusion, and non- registered tax planning.
NEW QUESTION # 60
Demario, age 28, has just started his own law firm. He met with his financial planner, Ivy, and she told him that he needs insurance, but Ivy did not specify which type. Demario is single and owns his own home. At this point in his career, his greatest asset is his human capital. Which type of insurance should Ivy have specified to purchase in order for Demario to best protect this asset?
Answer: B
Explanation:
Demario's human capital is his capacity to earn professional income from his law practice. A disability can destroy that earning capacity without causing death and without necessarily triggering critical illness coverage. Disability insurance is therefore the correct product to protect his greatest asset. Term life insurance would be more relevant if he had dependants, estate obligations, or a debt-repayment need at death. Extended health care helps with medical and dental costs but does not replace a lawyer's income if he cannot work.
Critical illness insurance pays on diagnosis of specified illnesses and can supplement planning, but it does not provide the same ongoing income-replacement function as disability coverage. Because Demario is self- employed, policy features such as own-occupation definition, elimination period, benefit period, and business overhead coverage should be reviewed carefully. Study Guide focus: human capital, disability insurance, self- employed professionals, income replacement, and risk management. The recommendation is therefore built around income continuity, not estate creation or reimbursement of medical expenses.
NEW QUESTION # 61
Harley is a novice investor who has just set up his first FHSA. He has a high-risk tolerance to market volatility and his primary investment objective is growth. He would like to invest $10,000 and will use the funds as part of the first-time home buyers plan within the next year. What investment should Harley purchase within this FHSA?
Answer: A
Explanation:
Harley's stated risk tolerance is not the controlling fact. The decisive constraint is time horizon: he intends to use the FHSA money within the next year for a first home purchase. When a required withdrawal is near, capital preservation and liquidity outrank long-term growth. A high-interest savings account is therefore the appropriate holding because it keeps the funds accessible and avoids exposing the down payment to equity market volatility. A locked-in one-year GIC may preserve capital, but it can create liquidity problems if the home purchase occurs before maturity. Equity-focused and income-focused mutual funds can fluctuate in value and may be unsuitable for funds earmarked for a near-term transaction. In AFP investment planning, risk capacity can be low even when risk tolerance is high; the client cannot afford a market loss shortly before the purchase. Study Guide focus: FHSA funding, investment time horizon, liquidity, risk capacity, and short- term goal funding.
NEW QUESTION # 62
Jimi and Macy, both age 26, consider themselves risk averse. After reviewing their budget with their financial planner, they discovered that they have a negative cash flow every couple of months due to their discretionary spending habits. What would be an appropriate strategy for their financial planner to recommend to the couple to manage their negative cash flow?
Answer: B
Explanation:
The problem is recurring negative cash flow caused by discretionary spending, not a need to add credit facilities. A personal line of credit would make the symptom easier to finance but would not correct the spending behaviour; for risk-averse young clients, it can also normalize the use of debt for lifestyle expenses.
A TFSA contribution plan creates a disciplined cash-flow structure, preserves access to funds, and allows tax- free growth. The account should be individual because TFSAs are registered to one holder, even if both members of a couple coordinate their savings strategy. A joint non-registered account may be useful in other circumstances, but pairing it with a line of credit does not address the planning issue. The most appropriate AFP recommendation is a budget-supported pre-authorized contribution strategy into individual TFSAs so liquidity is built before discretionary spending absorbs the surplus. Study Guide focus: budgeting, cash-flow controls, emergency savings, TFSA structure, and behavioural money management.
NEW QUESTION # 63
A client, age 60, is in a low tax bracket today and expects a larger taxable pension after age 65. She has TFSA and RRSP room. Which contribution priority is generally more appropriate?
Answer: A
Explanation:
The contribution decision turns on current versus future tax rates and the effect on retirement income. RRSP contributions are most powerful when the deduction is taken at a higher tax rate than the withdrawal rate. If the client is in a low bracket now and expects higher taxable income later, the RRSP deduction may be less valuable than the future tax cost. A TFSA provides no deduction, but qualified withdrawals are tax-free and do not increase taxable income or income-tested benefit exposure. Option A is incorrect because RRSP withdrawals are taxable. Option B ignores tax-sheltered growth and flexibility. Option D is impossible in ordinary RRSP planning because RRSPs must be matured by the end of the year the annuitant turns 71. The planner should still test exact brackets, pension timing, OAS exposure, available cash flow, and estate objectives. As a general rule in this fact pattern, TFSA priority is more defensible. References/topics: TFSA vs RRSP, marginal tax rate planning, retirement cash flow, income-tested benefits.
NEW QUESTION # 64
......
You are in a quest for high quality practice materials like our AFP-Exam-1 preparation exam. We avail ourselves of this opportunity to approach you to satisfy your needs. In order to acquaint you with our AFP-Exam-1 practice materials, we wish to introduce a responsible company dealing with exclusively in area of AFP-Exam-1 training engine and it is our company which keeps taking care of the readers' requests, desires and feeling about usage of our AFP-Exam-1 study questions in mind.
Exam AFP-Exam-1 Material: https://www.itbraindumps.com/AFP-Exam-1_exam.html
2026 Latest Itbraindumps AFP-Exam-1 PDF Dumps and AFP-Exam-1 Exam Engine Free Share: https://drive.google.com/open?id=15SFfbBJRVcIntt4W5fbz-n1fMgfwsAol