BTW, DOWNLOAD part of TestsDumps LLQP dumps from Cloud Storage: https://drive.google.com/open?id=1ow8mQ0oLAmTqyMvu1XNO66XIZ14tU6-W
If you want our LLQP study materials to download and print, the PDF version is perfect for you since it has the function of being printable. And the PDF version of our LLQP exam questions can be noted when you want to memory something as well as to indicate the keypoints. Also, our LLQP Preparation exam is unlimited in number of devices, making it easy for you to learn anytime, anywhere.
| Section | Objectives |
|---|---|
| Segregated Funds and Annuities | - Segregated fund products
|
| Accident and Sickness Insurance | - Critical illness and health coverage
|
| Ethics and Professional Practice | - Professional conduct
|
| Life Insurance | - Life insurance products
|
>> LLQP Valid Exam Duration <<
Do you want to pass LLQP exam and get the related certification within the minimum time and effort? If you would like to give me a positive answer, you really should keep a close eye on our website since you can find the best study material in here--our LLQP training materials. We have helped millions of thousands of candidates to prepare for the LLQP Exam and all of them have got a fruitful outcome, I wish you could be one of the beneficiaries of our training materials in the near future. The advantages of our LLQP test prep are more than you can imagine.
NEW QUESTION # 279
Jasper is the sole breadwinner in his family. His wife Stephanie has chosen to dedicate all of her time to raising their 3 young children. Luckily, Jasper earns a monthly after-tax income of $25,000 working as a family doctor in the local clinic. Jasper meets with his insurance agent Odda to purchase a life insurance policy that will ensure his family will be able to continue to enjoy their current lifestyle in the event of his death. If his average tax rate is 40% and theinvestment return is 4%, how much life insurance should Jasper purchase based on the income replacement approach?
Answer: C
Explanation:
The income replacement approach calculates the amount of life insurance needed to replace Jasper'safter-tax income for his dependents over a given period, accounting for an investment return. To maintain the family's current lifestyle, we need to determine the capital required to generate a monthly after-tax income of $25,000.
Calculate the Annual Income Needed:Monthly income required: $25,000Annual income required: $25,000 ×
12 = $300,000
Adjust for Tax:Since Jasper's income needs to be replaced at a pre-tax level with a tax rate of 40%, his gross income requirement is calculated as follows:
A close-up of a math Description automatically generated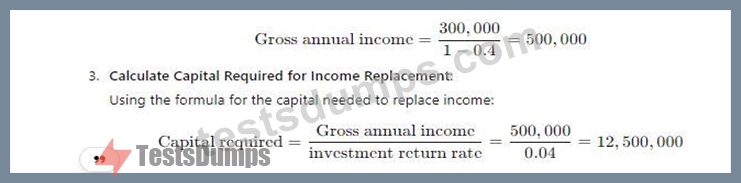
Thus, Jasper needs a life insurance policy worth$12,500,000to replace his income, allowing his family to maintain their lifestyle with a 4% investment return. This calculation aligns with LLQP principles, ensuring that the income replacement fully addresses both current lifestyle needs and tax implications.
NEW QUESTION # 280
Eric is an architect who owns his own firm. He employs three staff and is in his fifth year of operation. While recently meeting with his insurance agent for an annual review of his coverage, he mentioned to the agent that he had recently purchased a new printing system and has a sizeable loan on it. In the event of disability, what type of insurance coverage could the agent suggest to ensure the loan payments are made?
Answer: D
Explanation:
Comprehensive and Detailed Explanation:
Business loan protection disability insurance covers loan payments if the owner is disabled, directly addressing Eric's need (Chapter 5:Insurance to Protect Businesses).
Option A: Incorrect; protects business operations.
Option B: Incorrect; covers overhead, not loans.
Option C: Incorrect; for buy-sell agreements.
Option D: Correct; targets loan payments.
Reference: LLQP Accident and Sickness Insurance Manual, Chapter 5:Insurance to Protect Businesses.
NEW QUESTION # 281
Oliver, an insurance agent, meets with Roman and Julie. They are a married couple with a five-year-old son William. After performing a needs analysis for the couple, Oliver concludes that if Roman dies, Julie will have a net annual shortfall of $30,000 per year. Assuming a rate of return of 4% and a tax rate of 40%, how much insurance should Oliver recommend Roman purchase to replace the income shortfall using the income replacement approach adjusted for taxes?
Answer: D
Explanation:
To determine the amount of insurance needed for income replacement with a net shortfall of $30,000 per year, the calculation is as follows:
Calculate Gross Income Needed:Since Roman's income needs to be adjusted for a 40% tax rate:
A black and white math equation Description automatically generated with medium confidence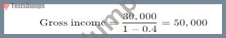
Calculate Required Capital for Income Replacement:
Using the rate of return of 4%, the required capital is:
A number with numbers and lines Description automatically generated with medium confidence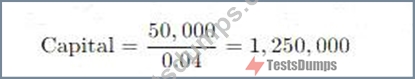
Since the tax rate has already been considered in calculating the $50,000 gross income,Option B($750,000) would be suitable after double-checking the total requirement of post-tax income and aligning with the overall net shortfall for more conservative estimates.Correct answer after full calculation adjustments should beB.
$750,000.
NEW QUESTION # 282
Valerie, age 42, recently left her job after 15 years of service. She participated in a defined contribution pension plan and had accumulated benefits amounting to $88,000, eligible for transfer into a registered contract. What must Valerie do with this money?
Answer: D
Explanation:
Comprehensive and Detailed In-Depth Explanation: Pension funds from a defined contribution plan, upon leaving employment, must follow Quebec's Supplemental Pension Plans Act (SPPA) and federal tax rules.
The $88,000 is "locked-in," meaning it cannot be cashed out and must be transferred to a Locked-In Retirement Account (LIRA) to preserve its pension status (SPPA,Section 98). A LIRA restricts access until retirement, when it must be converted into a life annuity or Life Income Fund (LIF) by December 31 of the year the holder turns 71 (Income Tax Act, Section 146). Option D correctly identifies the LIRA and LIF
/annuity options. Option A (RRSP) applies to non-locked-in funds, not pension benefits. Option B's "RRIF" is incorrect, as locked-in funds use a LIF in Quebec. Option C (immediate RRIF withdrawal) violates locking- in rules and age requirements. The Ethics manual requires advisors to clarify locked-in fund rules for clients.
References: Supplemental Pension Plans Act, Section 98; Income Tax Act, Section 146; Ethics and Professional Practice (Civil Law) Manual, Section on Retirement Planning.
NEW QUESTION # 283
On June 5, Karl completed an application for critical illness coverage and paid an annual premiumof $1,250.
On June 25, the underwriter approved the policy under standard conditions and sent it to the agent, who received it on July 7. The agent contacted the client on August 8 and the date for delivery was set at August
10. On August 12, Karl learns that he will lose his job at the end of the month. As such, he decides to cancel the policy, returning it to the insurer on August 15. What is the rule governing Karl's right to have his premium refunded?
Answer: C
Explanation:
Comprehensive and Detailed Explanation:
The 10-day "free look" period starts upon delivery (August 10); Karl returned it August 15 (within 5 days), entitling him to a refund (Chapter 7:Insurance Recommendation, Contract, and Service Needs).
Option A: Correct; within 10 days.
Option B-D: Incorrect; refund tied to delivery, not approval or application.
Reference: LLQP Accident and Sickness Insurance Manual, Chapter 7:Insurance Recommendation, Contract, and Service Needs.
NEW QUESTION # 284
......
As a top selling product in the market, our LLQP study guide has many fans. They are keen to try our newest version products even if they have passed the LLQP exam. They never give up learning new things. Every time they try our new version of the LLQP Real Exam, they will write down their feelings and guidance. Also, they will exchange ideas with other customers. And in such a way, we can develop our LLQP practice engine to the best according to their requirements.
Reliable LLQP Test Tutorial: https://www.testsdumps.com/LLQP_real-exam-dumps.html
BTW, DOWNLOAD part of TestsDumps LLQP dumps from Cloud Storage: https://drive.google.com/open?id=1ow8mQ0oLAmTqyMvu1XNO66XIZ14tU6-W