For some candidates, a good after-sale service is very important to them, since they may have some questions about the AFP-Exam-1 exam materials. We have the both live chat service stuff and offline chat service, if any question that may bother you , you can ask for a help for our service stuff. They have the professional knowledge about the AFP-Exam-1 Exam Materials, and they will give you the most professional suggestions.
| Section | Weight | Objectives |
|---|---|---|
| Enabling Competencies | 16% | - Professional Conduct and Regulatory Compliance - Client Relationship and Practice Management |
| Technical Competencies | 84% | - Estate Planning - Asset and Liability Management - Investment Planning - Tax Planning - Risk Management and Insurance - Retirement Planning |
>> Exam AFP-Exam-1 Questions Pdf <<
The passing rate of our AFP-Exam-1 training braindump is 99% which means that you almost can pass the AFP-Exam-1 test with no doubts. The reasons why our AFP-Exam-1 test guide’ passing rate is so high are varied. That is because our test bank includes two forms and they are the PDF test questions which are selected by the senior lecturer, published authors and professional experts and the practice test software which can test your mastery degree of our AFP-Exam-1 study question at any time. The two forms cover the syllabus of the entire AFP-Exam-1 test. You will pass the AFP-Exam-1 exam with it.
NEW QUESTION # 49
Alexander and Irena, age 30 and 32 respectively, are married and have been working full-time for one year.
They have a daughter, age 3, and are expecting their second child. They recently bought a home with a mortgage balance of $390,000 at 4% amortized over 25 years. Their financial planner is trying to determine their tolerance for risk. After completing the life-cycle analysis, how can their financial planner explain the stage in which the couple finds themselves and the risk tolerance associated with it?
Answer: A
Explanation:
Alexander and Irena are in the accumulation stage. They are young, recently established in full-time work, have young dependants, and carry a large mortgage. This stage commonly involves high debt, rising income potential, competing family costs, and a long investment horizon. A high tolerance for investment risk may be appropriate if cash flow, emergency reserves, insurance, and debt servicing are properly managed. The consolidation stage usually applies later when debts are lower and retirement savings become a stronger priority. Financial independence and gifting are later stages, usually associated with retirement security or surplus wealth transfer. The planner should explain that accumulation clients can often take more market risk because time is on their side, but they must also protect human capital and family obligations. Study Guide focus: life-cycle analysis, accumulation stage, family protection, mortgage debt, and risk tolerance. The planner should separate their willingness to take risk from their capacity after mortgage, childcare, and insurance costs.
NEW QUESTION # 50
A client wants to state her wishes about medical treatment if she becomes incapable of communicating.
Which document is most directly relevant?
Answer: A
Explanation:
A living will, advance health-care directive, or personal care directive records the client's wishes regarding medical and personal-care decisions if the client later lacks capacity or cannot communicate. The exact terminology varies by province, but the planning purpose is consistent: it guides substitute decision-makers and health-care providers about treatment preferences, end-of-life care, and personal values. Option A governs investment objectives and constraints. Option C authorizes trading activity and has no health-care function. Option D summarizes assets and liabilities but does not express medical wishes. A planner should not draft legal health-care documents unless qualified, but should identify the planning need and recommend legal advice. The document should be coordinated with any power of attorney for personal care or equivalent appointment, because naming the decision-maker and documenting wishes are complementary. Incapacity planning is distinct from a will, which operates after death. References/topics: living will, personal care directive, incapacity planning, substitute decision-making.
NEW QUESTION # 51
Which statement best distinguishes a defined benefit pension plan from a defined contribution pension plan?
Answer: C
Explanation:
A defined benefit pension plan promises a retirement benefit determined by a formula, commonly based on earnings, service, and an accrual rate. The member can estimate retirement income with greater certainty, subject to plan terms and funding rules. A defined contribution plan specifies contributions to an account; the eventual retirement income depends on contributions, investment returns, fees, annuity rates or withdrawal decisions, and longevity. Option A reverses the distinction. Option C is inaccurate because defined benefit plans are employer-sponsored arrangements with plan governance and funding obligations. Option D is wrong because defined contribution members bear significant investment and longevity risk unless they later purchase an annuity or otherwise transfer risk. For planning purposes, the distinction affects retirement projections, RRSP room through pension adjustments, asset allocation, risk capacity, and income sustainability. A planner must not treat all pensions alike; the type of pension determines both certainty of income and the risks remaining with the client. References/topics: defined benefit plans, defined contribution plans, pension risk, retirement projections.
NEW QUESTION # 52
Jackson, a wealth advisor, is helping Terry, a self-employed IT professional, determine his net income. The goal is to develop a budget and savings strategy for the year ahead Terry has provided the information below: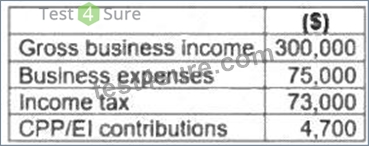
What is Terry's net business income?
Answer: D
Explanation:
Terry's net business income is $225,000. The calculation starts with gross business income of $300,000 and subtracts deductible business expenses of $75,000. Income tax is not deducted in computing net business income for this purpose; it is calculated after taxable income is determined. CPP/EI contributions are also not treated as ordinary business expenses in this basic net business income calculation. Option A and option B incorrectly subtract personal tax and statutory contribution amounts. Option D subtracts the CPP/EI amount from business profit but still incorrectly treats it as part of the business-income calculation. The planner needs the correct net business income figure because it drives budgeting, savings capacity, tax installments, retirement contribution planning, insurance affordability, and debt-service analysis. AFP cash-flow work separates business operating results from personal tax payments and after-tax cash flow. Study Guide focus:
self-employment income, deductible business expenses, net income, tax planning, and budgeting.
NEW QUESTION # 53
Barbara, age 50, is meeting with her financial planner, Clark. Barbara has been hired as the Chief Executive Officer of a very successful privately owned business. Her salary will be $200,000 annually, plus a bonus.
Which retirement savings option should Clark recommend for Barbara?
Answer: B
Explanation:
An individual pension plan is the appropriate retirement savings option for Barbara. She is age 50, will earn a high salary as CEO of a successful privately owned business, and is likely in a position where an employer- sponsored defined benefit style arrangement can provide enhanced retirement funding. IPPs are particularly useful for older, high-income incorporated business owners or executives because permitted contributions can exceed RRSP limits under actuarial funding rules. A retirement compensation arrangement can supplement retirement benefits for very high earners, but the standard AFP recommendation in this fact pattern is the IPP.
A general defined benefit plan is not as targeted as an individual pension plan, and a deferred profit-sharing plan is usually less appropriate for maximizing retirement savings for a specific senior executive.
Implementation requires actuarial, legal, and tax administration. Study Guide focus: individual pension plans, executive retirement planning, incorporated businesses, RRSP limits, and tax-assisted savings. The recommendation should be confirmed with actuarial and tax advice because IPPs carry formal funding and administration rules.
NEW QUESTION # 54
......
Test4Sure would give you access to Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) exam questions that are factual and unambiguous, as well as information that is important for the preparation of the AFP-Exam-1 exam. You won't be anxious because the available Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) exam dumps are structured instead of distributed. Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) certification exam candidates have specific requirements and anticipate a certain level of satisfaction before buying a CSI AFP-Exam-1 practice exam. The Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) practice exam applicants can rest assured that Test4Sure's round-the-clock support staff will answer their questions.
Practice AFP-Exam-1 Test: https://www.test4sure.com/AFP-Exam-1-pass4sure-vce.html