BTW, DOWNLOAD part of Exam-Killer IFC dumps from Cloud Storage: https://drive.google.com/open?id=1iHOdFI7waZEGEZKru3A9KLLSTrEok1S6
The latest IFC exam torrent covers all the qualification exam simulation questions in recent years, including the corresponding matching materials at the same time. Do not have enough valid IFC practice materials, can bring inconvenience to the user, such as the delay progress, learning efficiency and to reduce the learning outcome was not significant, these are not conducive to the user persistent finish learning goals. Therefore, to solve these problems, the IFC test material is all kinds of qualification examination, the content of the difficult point analysis, let users in the vast amounts of find the information you need in the study materials, the IFC practice materials improve the user experience, to lay the foundation for good grades through qualification exam.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
| Topic 5 |
|
| Topic 6 |
|
| Topic 7 |
|
Simplified language allows candidates to see at a glance. With this purpose, our IFC learning materials simplify the questions and answers in easy-to-understand language so that each candidate can understand the test information and master it at the first time, and they can pass the test at their first attempt. Our experts aim to deliver the most effective information in the simplest language. Each candidate takes only a few days can attend to the IFC Exam. In addition, our IFC IFC provides end users with real questions and answers. We have been working hard to update the latest IFC learning materials and provide all users with the correct IFC answers. Therefore, our IFC learning materials always meet your academic requirements.
NEW QUESTION # 55
Dakota is a Dealing Representative with Harvest Wealth Inc., a mutual fund dealer. Dakota starts a marketing campaign to contact prospective new clients and increase sales with existing clients. Which of the following CORRECTLY describes activities that Dakota can engage in under her marketing campaign?
Answer: A
Explanation:
Dakota can send promotional emails to clients who have opted in to receive commercial electronic messages (CEMs). A CEM is any electronic message that encourages participation in a commercial activity, such as an email, a text message, or a social media message. Under Canada's anti-spam legislation (CASL), Dakota must obtain consent from the recipients before sending CEMs, either explicitly (e.g., by asking them to sign up for a newsletter) or implicitly (e.g., by having an existing business relationship with them). Dakota must also identify himself and his dealer, provide contact information, and include an unsubscribe mechanism in every CEM. The other statements are incorrect. Dakota cannot make telemarketing calls to clients who are listed on the National Do Not Call List (DNCL). The DNCL is a list of telephone numbers of consumers who do not want to receive unsolicited telemarketing calls. Under the Telecommunications Act, Dakota must register with the National DNCL operator, subscribe to the National DNCL, and avoid calling any number on the list, unless he has express consent from the consumer or an exemption applies. Dakota cannot send promotional emails to clients who have opted into Harvest Wealth's Do Not Call List. A Do Not Call List is a list of telephone numbers of consumers who do not want to receive telemarketing calls from a specific organization.
Under the Telecommunications Act, Dakota must maintain an internal Do Not Call List for his dealer and respect the requests of consumers who ask not to be called by his dealer. However, this does not mean that he can send promotional emails to those consumers, as that would violate CASL. Dakota cannot make telemarketing calls to clients who have opted in to receive commercial electronic messages (CEMs). Opting in to receive CEMs does not imply consent to receive telemarketing calls, as they are different forms of communication governed by different laws . Dakota must obtain separate consent from the clients before making telemarketing calls to them, either explicitly or implicitly. References: [Canada's anti-spam legislation], [National Do Not Call List]
NEW QUESTION # 56
You have been researching Canadian equity mutual funds for a new client. You come across the following information.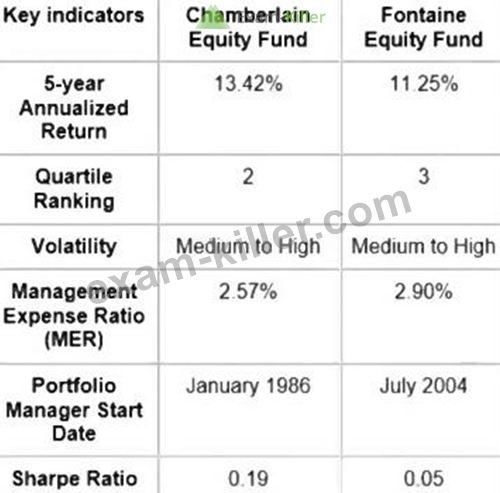
What can you conclude from this information?
Answer: B
Explanation:
The management expense ratio (MER) is the percentage of a fund's assets that is paid to the fund manager for operating and managing the fund. A higher MER means that more of the fund's returns are eaten up by fees, leaving less for the investors. Therefore, Fontaine Equity Fund's higher MER of 2.99% contributes to its lower 5-year annualized return of 11.25%, compared to Chamberlain Equity Fund's MER of 2.57% and 5- year annualized return of 13.42%. Therefore, D is the correct answer. , Management Expense Ratio (MER):
Definition and How It Works - Investopedia
NEW QUESTION # 57
What expense ratio is paid by mutual fund investors for the explicit costs of running the fund?
Answer: B
Explanation:
The management expense ratio (MER) represents the total of all management fees and operating expenses charged to the fund, expressed as a percentage of average net asset value.
Operating expense ratio is not a standard measure.
Management fee ratio refers only to the management fee portion.
Trading expense ratio covers only trading commissions.
Therefore, mutual fund investors pay expenses through the MER
NEW QUESTION # 58
Matthew is planning on making the following investments in December: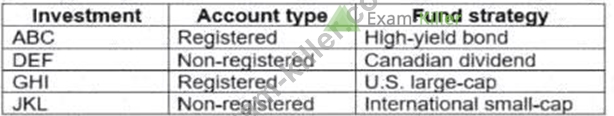
Assuming all four investments have performed well throughout the year, which investment will trigger the highest unexpected taxes?
Answer: D
Explanation:
The correct answer is A. JKL , the non-registered international small-cap fund , because it is most likely to generate unexpected and fully taxable distributions at year-end. The Investment Funds in Canada course explains that mutual funds held in non-registered accounts are subject to taxation on distributions, even if the investor does not sell the fund . These distributions may include interest income, foreign income, dividends, and capital gains.
International equity funds typically generate foreign-source income , which does not qualify for the Canadian dividend tax credit and is therefore fully taxable at the investor's marginal tax rate. In addition, international small-cap funds tend to have higher portfolio turnover , increasing the likelihood of realizing capital gains inside the fund. The CIFC curriculum emphasizes that " capital gains distributions are taxable to investors even when automatically reinvested ," making them a common source of unexpected taxes.
By contrast, DEF (Canadian dividend fund in a non-registered account) benefits from the dividend tax credit
, reducing its tax burden. ABC and GHI are held in registered accounts , where income and capital gains are either tax-deferred or tax-sheltered, meaning no current tax consequences apply.
The course specifically warns that purchasing funds late in the year in non-registered accounts can result in
"buying a taxable distribution" , especially with international equity funds.
NEW QUESTION # 59
During the calendar year, Firmansyah received a $1,800 eligible dividend from a large Canadian bank and a
$US dollar (USD) dividend of $882.02 from a foreign-based corporation. The USD/CAD exchange rates is
1.3605.
Firmansyah's federal marginal tax bracket is 29%. The enhanced dividend gross-up rate is 38% and the federal dividend tax credit rate for eligible dividends is 15%.
What federal tax liability will be result from his investment income?
Answer: B
Explanation:
To calculate the federal tax liability from the investment income, we need to consider the following steps:
* Convert the foreign dividend to Canadian dollars using the exchange rate.In this case, $882.02 USD x
1.3605 = $1,200.00 CAD.
* Gross up the eligible dividend by the enhanced dividend gross-up rate of 38%.In this case, $1,800 x
1.38 = $2,484.
* Add the grossed-up eligible dividend and the foreign dividend to get the total taxable income from dividends.In this case, $2,484 + $1,200 = $3,684.
* Multiply the total taxable income from dividends by the federal marginal tax rate of 29% to get the gross federal tax payable.In this case, $3,684 x 0.29 = $1,068.36.
* Multiply the grossed-up eligible dividend by the federal dividend tax credit rate of 15% to get the federal dividend tax credit.In this case, $2,484 x 0.15 = $372.60.
* Subtract the federal dividend tax credit from the gross federal tax payable to get the net federal tax liability.In this case, $1,068.36 - $372.60 = $695.76.
Therefore, Firmansyah's federal tax liability from his investment income is $695.76.
1: Canadian Investment Funds Course - IFSE Institute 2 (Unit 9: Retirement)
NEW QUESTION # 60
......
Our IFC prep torrent boosts the highest standards of technical accuracy and only use certificated subject matter and experts. We provide the latest and accurate Investment Funds in Canada (IFC) Exam exam torrent to the client and the questions and the answers we provide are based on the real exam. But you buy our IFC prep torrent you can mainly spend your time energy and time on your job, the learning or family lives and spare little time every day to learn our Investment Funds in Canada (IFC) Exam exam torrent. Our answers and questions are compiled elaborately and easy to be mastered. Because our IFC Test Braindumps are highly efficient and the passing rate is very high you can pass the exam fluently and easily with little time and energy needed.
Exam IFC Flashcards: https://www.exam-killer.com/IFC-valid-questions.html
What's more, part of that Exam-Killer IFC dumps now are free: https://drive.google.com/open?id=1iHOdFI7waZEGEZKru3A9KLLSTrEok1S6