Now as you have the best test study material from ExamcollectionPass, you must start with the process of learning. Hard work always pays off and there is no chance to fail the AFP-Exam-1 exam if you are fully prepared with ExamcollectionPass PDF questions. There is no way that your preparation with real Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) questions PDF shall disappoint you.
| Section | Objectives |
|---|---|
| Investment Planning | - Asset allocation and portfolio basics - Investment products and risk-return profiles |
| Taxation Concepts | - Personal income tax principles - Tax-efficient investment strategies |
| Insurance and Risk Management | - Life and health insurance fundamentals - Risk mitigation strategies in financial planning |
| Financial Planning Foundations | - Ethics and professional standards in financial advising - Financial planning process and client relationship management |
| Retirement Planning | - Retirement savings vehicles and planning principles |
>> CSI AFP-Exam-1 Certification Cost <<
Do you have bought the CSI pdf version for your preparation? If not, hurry up to choose our AFP-Exam-1 pdf torrent. Our AFP-Exam-1 pdf study material is based on the AFP-Exam-1 real exam scenarios covering all the exam objectives. You will find it is very helpful and precise in the subject matter since all the AFP-Exam-1 Exam contents is regularly updated and has been checked and verified by our professional experts. AFP-Exam-1 will help you to strengthen your technical knowledge and allow you pass at your first try.
NEW QUESTION # 119
Janet's non-registered account holds the funds listed in the following table: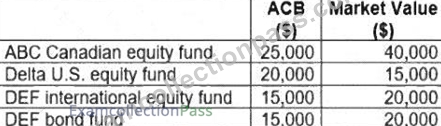
Assuming a marginal tax rate of 45%, what amount of tax payable will Janet incur if she redeems the account to fund the purchase of a new business?
Answer: C
Explanation:
Janet's taxable result comes from the net realized capital gain, not from the total market value redeemed. The ABC Canadian equity fund has a $15,000 gain, the Delta U.S. equity fund has a $5,000 loss, the DEF international equity fund has a $5,000 gain, and the DEF bond fund has a $5,000 gain. Net capital gains are therefore $20,000 after offsetting the Delta loss. Only one-half of the net capital gain is taxable under the standard capital gains inclusion treatment used in AFP-level calculations, producing a $10,000 taxable capital gain. At a 45% marginal tax rate, the tax payable is $4,500. Option A taxes the full net gain; option C and option D reflect incorrect inclusion or arithmetic assumptions. The purpose of the question is to test disposition analysis in a non-registered account and the sequence of gain/loss netting before applying the marginal rate. Study Guide focus: adjusted cost base, fair market value, capital gains inclusion, and non- registered tax planning.
NEW QUESTION # 120
William and Jennifer are selling their business which qualifies as a Canadian-controlled private corporation.
When the sale is complete at the end of this year, William and Jennifer will each receive $4 million for their common shares which have nominal cost. Jennifer has unused capital losses from previous years. They are meeting with Laurel, their financial planner, to discuss the tax implications of the sale. Based on the information provided, what should Laurel recommend to William and Jennifer so that they are best able to make use of the Lifetime Capital Gains Exemption?
Answer: D
Explanation:
William should claim the Lifetime Capital Gains Exemption, while Jennifer should first use her unused capital losses. The planning issue is not whether both shareholders own qualifying Canadian-controlled private corporation shares; they do. The deciding fact is Jennifer's unused capital losses. In the personal tax calculation, capital losses are applied against taxable capital gains before the capital gains deduction is used.
If Jennifer has available losses, claiming the LCGE may waste exemption room or fail to deliver the intended tax result because the losses already shelter some or all of her taxable capital gain. William has no stated capital-loss pool, so his large gain is the clean use of the exemption. Options that split the exemption or have Jennifer claim it ignore the ordering rules and the clue in the facts. The planner should coordinate the transaction with tax counsel and confirm QSBC eligibility, CNIL effects, and each spouse's remaining exemption room. Study Guide focus: qualified small business corporation shares, capital gains deduction, net capital losses, and LCGE planning.
NEW QUESTION # 121
Sarah Jones is an incorporated owner of a successful manufacturing company. She currently has a large month to month cash flow surplus. This is expected to continue until she retires in seven years. Her personal mortgage is up for renewal. She needs to borrow $50,000 so that she can replace a piece of equipment that is needed in the manufacturing process. She would like a solution that results in paying the lowest interest cost over the life of the loan. Which loan product should the financial planner recommend to Sarah? Assume monthly compounding for all products and no pre-payment options.
Answer: C
Explanation:
The correct comparison is total interest cost over the life of the loan, not simply the lowest stated rate. Sarah has a persistent cash-flow surplus and needs $50,000 for business equipment. The secured corporate loan has a higher nominal rate than the mortgage alternatives, but it amortizes over only five years. The 25-year corporate mortgage and refinanced personal mortgage keep the debt outstanding for much longer and can create more total interest despite lower rates. The HELOC requires interest-only payments for seven years and a balloon repayment, which extends interest exposure. Because the question excludes prepayment options, Sarah cannot reduce the longer-amortization cost early. The secured corporate loan is therefore the lowest lifetime-interest solution among the choices. The planner should also consider deductibility, corporate purpose, security, and business cash flow. Study Guide focus: loan amortization, interest cost, business borrowing, cash-flow surplus, and debt-structure analysis. The business purpose also supports reviewing whether the borrowing should remain corporate rather than personal.
NEW QUESTION # 122
Mina has $20,000 in a savings account earning 3% before tax. She also has a $9,000 credit card balance at
22%, a $7,000 unsecured line of credit at 10%, and a $14,000 car loan at 4%. Her marginal tax rate is 35%.
Which liability should she target first?
Answer: D
Explanation:
The credit card is the highest-cost non-deductible liability and should be the first repayment target, subject to retaining an adequate emergency reserve. Mina's savings account produces only 3% before tax, or 1.95% after tax at a 35% marginal rate. That return is overwhelmed by a 22% credit card rate. Paying the card produces a risk-free improvement equal to avoided interest; no conservative investment can justify carrying that balance. Option A is lower priority because the car loan rate is modest. Option C is important but still secondary to the credit card. Option D ignores the after-tax spread between savings income and debt cost. The planning principle is not simply "pay debt"; it is to compare after-tax investment returns with after-tax borrowing costs, prioritizing expensive consumer debt while preserving liquidity. The planner should then structure a repayment plan and address the spending pattern that created the balance. References/topics: debt prioritization, cash flow, after-tax return, asset and liability management.
NEW QUESTION # 123
Richard pays periodic spousal support and child support under a written separation agreement. Which statement is generally correct?
Answer: C
Explanation:
Tax treatment depends on the type of support. Periodic spousal support paid under a qualifying written agreement or court order is generally deductible to the payer and taxable to the recipient. Child support is generally not deductible to the payer and not taxable to the recipient. Option B wrongly treats child support like deductible spousal support. Option C confuses payment frequency with tax character; monthly payment does not make child support taxable. Option D is plainly incorrect because spousal support can materially affect after-tax cash flow for both parties. A financial planner should distinguish periodic support from lump- sum settlements, property transfers, arrears, legal fees, and combined agreements because classification changes projections. The planner should also ensure tax assumptions follow the wording of the agreement and should recommend legal or tax advice where facts are unclear. The planning result is measured on after-tax cash flow, not simply the gross support amount. References/topics: support payments, divorce planning, cash flow, tax deductibility.
NEW QUESTION # 124
......
Our AFP-Exam-1 exam review contains the latest test questions and accurate answers along with the professional explanations. A little attention to prepare AFP-Exam-1 practice test will improve your skills to clear exam with high passing score. For most busy IT workers, AFP-Exam-1 Dumps PDF is the best alternative to your time and money to secure the way of success in the IT filed.
Valid AFP-Exam-1 Test Questions: https://www.examcollectionpass.com/CSI/AFP-Exam-1-practice-exam-dumps.html