P.S.JpexamがGoogle Driveで共有している無料の2026 National Payroll Institute PF1ダンプ:https://drive.google.com/open?id=1Mc_wg4-tbIs91McWco3t1vldYf_bEAPk
JpexamのNational Payroll InstituteのPF1の試験問題は同じシラバスに従って、実際のNational Payroll InstituteのPF1認証試験にも従っています。弊社はずっとトレーニング資料をアップグレードしていますから、提供して差し上げた製品は一年間の無料更新サービスの景品があります。あなたはいつでもサブスクリプションの期間を延長することができますから、より多くの時間を取って充分に試験を準備できます。Jpexamというサイトのトレーニング資料を利用するかどうかがまだ決まっていなかったら、Jpexamのウェブで一部の試験問題と解答を無料にダウンローしてみることができます。あなたに向いていることを確かめてから買うのも遅くないですよ。あなたが決して後悔しないことを保証します。
| Section | Objectives |
|---|---|
| Topic 1: New Employee Information | - Employee setup and documentation
|
| Topic 2: Termination of Employment | - Termination processing
|
| Topic 3: Non-Regular Payments | - Special payroll payments
|
| Topic 4: Provincial Remittances | - Provincial payroll requirements
|
| Topic 5: Federal Remittances | - Government remittance obligations
|
| Topic 6: Employment Income – Regular Earnings | - Regular payroll calculations
|
| Topic 7: Payroll Accounting | - Payroll accounting practices
|
| Topic 8: Year-End Processing | - Federal and provincial year-end reporting
|
| Topic 9: Commission Payments | - Commission payroll processing
|
| Topic 10: Workers’ Compensation | - Workers compensation administration
|
| Topic 11: Record of Employment | - ROE processing
|
| Topic 12: Employment Income – Allowances, Expenses and Benefits | - Taxable and non-taxable benefits
|
| Topic 13: Non-Statutory Deductions | - Voluntary deductions
|
あなたより優れる人は存在している理由は彼らはあなたの遊び時間を効率的に使用できることです。どのようにすばらしい人になれますか?ここで、あなたに我々のNational Payroll Institute PF1試験問題集をお勧めください。弊社JpexamのPF1試験問題集を介して、速く試験に合格してPF1試験資格認定書を受け入れる一方で、他の人が知らない知識を勉強して優れる人になることに近くなります。
質問 # 34
Bonus and incentive pays are subject to which statutory deductions?
正解:B
解説:
Bonuses and incentives are treated as taxable remuneration, so they are generally subject to the same core statutory deductions as regular earnings: CPP/QPP, EI, and income tax (and in Quebec, QPIP also applies when the remuneration is subject to EI). The CRA specifically notes that you must deduct EI premiums from bonuses/retroactive pay (up to the annual maximum), and the CRA's guidance for bonuses/irregular amounts uses tools (PDOC/formulas) that calculate CPP contributions, EI premiums, and income tax on these payments.
In Quebec payroll, remuneration that is subject to EI premiums is generally also subject to QPIP premiums, so bonuses/incentives that are EI-insurable are typically QPIP-insurable as well.
In the Northwest Territories and Nunavut, there is also a statutory territorial payroll tax that employers must withhold/remit where applicable, and the NWT guidance explicitly lists bonuses as part of employment income subject to payroll tax.
質問 # 35
What is the portion of a retiring allowance eligible to be transferred into a Registered Retirement Savings Plan (RRSP) or a registered pension plan (RPP) tax free based on?
正解:D
解説:
The CRA sets out that the "eligible" portion of a retiring allowance that may be transferred directly to an RRSP/RPP under special rules is based on years of service before 1996 (and potentially an additional amount for certain pre-1989 years if specific pension/DPSP conditions are met). The CRA explains the eligible part is
$2,000 for each year (or part-year) of service before 1996, plus you may be able to transfer an additional
$1,500 for each year (or part-year) of service before 1989 where no employer pension/DPSP benefit was vested (or previously paid) for those years.
This is why the correct basis in the answer choices is the employee's years of service prior to 1996, not wages, age, or average earnings. Payroll needs this service history (including related employers where applicable) to correctly identify the eligible/non-eligible split and apply the right withholding and transfer reporting.
質問 # 36
National Hardware, an Ontario organization, will be terminating the employment of Emilie St. Germain on October 28, 2019, the last day of the pay period. Emilie started with National Hardware on September 19,
2007. Complete the paper Record of Employment (ROE) for Emilie based on the information provided in the following chart.
Note: Vacationable earnings already include the pay in lieu of notice.
All dates must be entered in the format DDMMYYYY.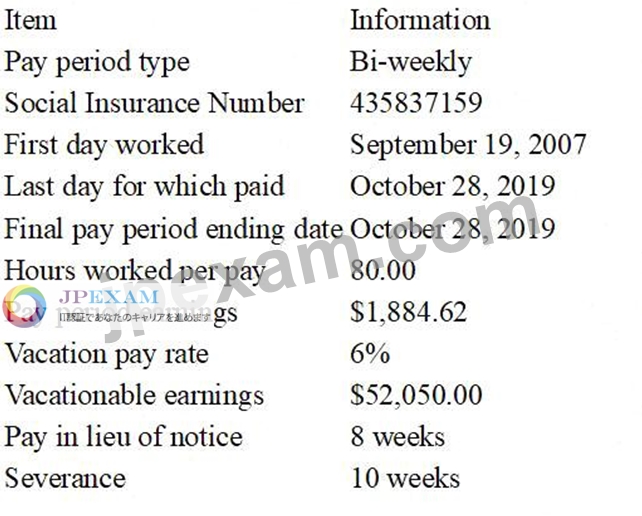
Paper ROE (Form Reference)
Complete the following paper ROE blocks for Emilie:
Block 6 - Pay period type
Block 8 - Social Insurance Number
Block 10 - First day worked
Block 11 - Last day for which paid
Block 12 - Final pay period ending date
Block 15A - Total insurable hours
Block 15B - Total insurable earnings
Block 17A - Vacation pay
Block 17C - Other monies (Pay in lieu of notice)
Block 17C - Other monies (Severance)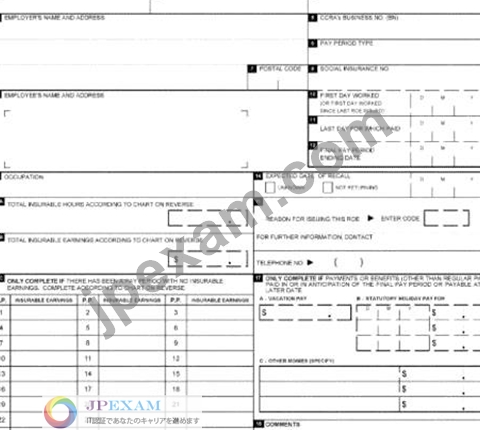
Step 1 - Complete Block 6
Enter the pay period type for Emilie.
Step 2 - Complete Block 8
Enter Emilie's Social Insurance Number.
Step 3 - Complete Block 10
Enter Emilie's first day worked in DDMMYYYY format.
Step 4 - Complete Block 11
Enter Emilie's last day for which paid in DDMMYYYY format.
Step 5 - Complete Block 12
Enter the final pay period ending date in DDMMYYYY format.
Step 6 - Complete Block 15A
Calculate and enter total insurable hours.
Given:
Hours worked per pay period = 80.00
Bi-weekly ROE pay period chart captures 27 pay periods
Step 7 - Complete Block 15B
Calculate and enter total insurable earnings.
Given:
Pay period earnings = $1,884.62
Bi-weekly ROE pay period chart captures 27 pay periods
Step 8 - Complete Block 17A
Calculate and enter vacation pay.
Given:
Vacation pay rate = 6%
Vacationable earnings = $52,050.00
(already includes pay in lieu of notice)
Step 9 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Pay in lieu of notice.
Given:
Pay in lieu of notice = 8 weeks
Use weekly earnings derived from the bi-weekly pay period earnings.
Step 10 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Severance.
Given:
Severance = 10 weeks
Use the same weekly earnings used in Step 9.
正解:
解説:
See the Below Explanation for complete Solution.
Explanation:
Step 1 - Block 6
Bi-weekly
Step 2 - Block 8
435837159
Step 3 - Block 10
September 19, 2007 # 19092007
Step 4 - Block 11
October 28, 2019 # 28102019
Step 5 - Block 12
October 28, 2019 # 28102019
Step 6 - Block 15A (Total insurable hours)
80.00 × 27 = 2160
Block 15A = 2160
Step 7 - Block 15B (Total insurable earnings)
$1,884.62 × 27 = $50,884.74
Block 15B = 50,884.74
Step 8 - Block 17A (Vacation pay)
$52,050.00 × 6% = $3,123.00
Block 17A = 3,123.00
Step 9 - Block 17C (Pay in lieu of notice)
Weekly earnings = $1,884.62 ÷ 2 = $942.31
Pay in lieu = $942.31 × 8 = $7,538.48
Block 17C (Pay in lieu of notice) = 7,538.48
Step 10 - Block 17C (Severance)
Severance = $942.31 × 10 = $9,423.10
Block 17C (Severance) = 9,423.10
質問 # 37
The deduction for living in a prescribed zone can be claimed by residents of which jurisdictions?
正解:B
解説:
The Northern residents deductions (often referred to as the "prescribed zone" deduction on the personal tax return) are not limited to the three territories. While all places in Yukon, Nunavut, and the Northwest Territories are in a prescribed northern zone (Zone A), the rules also designate prescribed northern and intermediate zones in parts of several provinces (for example, parts of British Columbia, Alberta, Saskatchewan, Manitoba, Ontario, and others).
The governing framework is in the Income Tax Regulations, which define prescribed zones using geographic descriptions (latitudes/longitudes) covering areas in multiple provinces, as well as the territories.
From a payroll/HR communications perspective, the key is that this deduction is generally claimed by the individual on their income tax return (it does not change the employer's province-of-employment withholding rules). Employees who believe they qualify should verify their community's zone status using CRA's prescribed zone lists before claiming the deduction.
質問 # 38
Anthony earns $750.00 per week. He has a cash taxable benefit of $25.00 per week. Anthony is exempt from CPP contributions. Calculate the net taxable income for the week.
正解:
解説:
$775.00
Explanation:
"Net taxable income" for payroll withholding purposes is the amount of income on which income tax is calculated for the pay period. It generally starts with the employee's gross taxable earnings for the period (regular wages plus any taxable benefits/allowances that must be included in income), then subtracts only those deductions that are deductible for tax at source (for example, certain registered pension plan contributions, union dues, etc., if applicable). A cash taxable benefit is treated like additional remuneration and is included in taxable income. (canada.ca) Here, Anthony's weekly taxable earnings are:
$750.00 wages + $25.00 cash taxable benefit = $775.00.
Being exempt from CPP contributions affects whether CPP is deducted, but CPP is not a "net taxable income" subtraction in this question (and in any case, no CPP is being deducted). The question also does not mention any other tax-deductible payroll deductions (like RPP contributions), so there is nothing to subtract from taxable earnings.
Therefore, Anthony's net taxable income for the week is $775.00.
質問 # 39
......
自分のIT業界での発展を希望したら、National Payroll InstituteのPF1試験に合格する必要があります。National Payroll InstituteのPF1試験はいくつ難しくても文句を言わないで、我々Jpexamの提供する資料を通して、あなたはNational Payroll InstituteのPF1試験に合格することができます。National Payroll InstituteのPF1試験を準備しているあなたに試験に合格させるために、我々Jpexamは模擬試験ソフトを更新し続けています。
PF1学習指導: https://www.jpexam.com/PF1_exam.html
BONUS!!! Jpexam PF1ダンプの一部を無料でダウンロード:https://drive.google.com/open?id=1Mc_wg4-tbIs91McWco3t1vldYf_bEAPk