P.S. Kostenlose und neue LLQP Prüfungsfragen sind auf Google Drive freigegeben von Fast2test verfügbar: https://drive.google.com/open?id=1TxGLn-60DQNxLiSjtXN6Hi3P9V0A_ZVj
Es ist unrealistisch, beim Lernen der relevanten Bücher diese IFSE Institute LLQP Prüfung zu bestehen. Es ist besser für Sie, einige wertvolle Prüfungsfragen zu machen, statt alle Kenntnisse für die Prüfung ziellos auswendig zu lernen. Die hocheffektive Dumps sind das beste Vorbereitungsgerät. So Kaufen Sie bitte schnell die IFSE Institute LLQP Dumps von Fast2test. Das ist Dumps mit höher Hit-Rate. Und es ist wirksamer als alle andere Lernmethoden. Die sind die Unterlagen, womit Sie einmaligen Erfolg machen können.
| Section | Objectives |
|---|---|
| Ethics and Professional Practice | - Professional conduct
|
| Life Insurance | - Underwriting and risk assessment
|
| Segregated Funds and Annuities | - Segregated fund products
|
| Accident and Sickness Insurance | - Disability insurance
|
>> LLQP Fragen Und Antworten <<
Das Vertrauen von den Kunden zu gewinnen ist uns große Ehre. Die IFSE Institute LLQP Prüfungssoftware ist schon von zahlreichen Kunden anerkannt worden. Mit Hilfe dieser Software haben fast alle Benutzer die IFSE Institute LLQP Prüfung bestanden. Falls Sie sich jetzt auf IFSE Institute LLQP vorbereiten, dann können Sie die Demo unserer Prüfungsunterlagen probieren. Wir hoffen, dass unsere Software auch Ihre Anerkennung erlangen kann.
135. Frage
Jasper is the sole breadwinner in his family. His wife Stephanie has chosen to dedicate all of her time to raising their 3 young children. Luckily, Jasper earns a monthly after-tax income of $25,000 working as a family doctor in the local clinic. Jasper meets with his insurance agent Odda to purchase a life insurance policy that will ensure his family will be able to continue to enjoy their current lifestyle in the event of his death. If his average tax rate is 40% and the investment return is 4%, how much life insurance should Jasper purchase based on the income replacement approach?
Antwort: D
Begründung:
The income replacement approach calculates the amount of life insurance needed to replace Jasper'safter-tax income for his dependents over a given period, accounting for an investment return. To maintain the family's current lifestyle, we need to determine the capital required to generate a monthly after-tax income of $25,000.
* Calculate the Annual Income Needed:Monthly income required: $25,000Annual income required:
$25,000 × 12 = $300,000
* Adjust for Tax:Since Jasper's income needs to be replaced at a pre-tax level with a tax rate of 40%, his gross income requirement is calculated as follows:
A close-up of a math Description automatically generated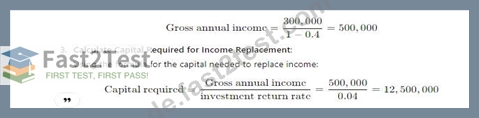
Thus, Jasper needs a life insurance policy worth$12,500,000to replace his income, allowing his family to maintain their lifestyle with a 4% investment return. This calculation aligns with LLQP principles, ensuring that the income replacement fully addresses both current lifestyle needs and tax implications.
136. Frage
Mordecai's life insurance lapsed four years after the policy was issued because he failed to make premium payments. The insurer reinstated the policy several months later when he made the required payments and provided the medical and financial information the insurer required. Twelve months later, Mordecai commits suicide and his beneficiaries ask Larry, his insurance agent, whether the claim will be paid. What should Larry tell the beneficiaries?
Antwort: A
Begründung:
Comprehensive and Detailed in Depth Explanation with Exact Extract from Documents and Guides:
TheIFSE Ethics and Professional Practice Course (Common Law)explains that life insurance policies typically include a suicide clause, which denies the death benefit if the insured commits suicide within a specified period-usually two years-from the policy's issue date or reinstatement date. When a policy lapses and is reinstated, the suicide exclusion period restarts from the reinstatement date, not the original issue date.
In this case, Mordecai's policy lapsed after four years, was reinstated, and he committed suicide 12 months (less than two years) later. The incontestability clause (which prevents insurers from denying claims based on misstatements after two years) does not override the suicide exclusion, making A incorrect. Public order (B) is irrelevant, and there's no evidence of a preexisting condition (D) affecting the suicide clause. Thus, Larry should inform the beneficiaries that the claim will be rejected due to the suicide exclusion restarting upon reinstatement, making C correct.
References:
IFSE Ethics and Professional Practice Course (Common Law), Module 2: Insurance Contracts, Section on
"Suicide Clause" and "Reinstatement."
137. Frage
(Nancy has invested $100,000 in mining company stocks in her local area.
To which of the following risks is Nancy most exposed?)
Antwort: D
Begründung:
By investing heavily in asingle sector(mining), Nancy facesindustry risk. Industry-specific issues such as regulation changes, market conditions, or operational challenges could severely impact her investments.
Exact Extract:
"Industry risk is the risk that factors affecting an entire industry may negatively impact investments within that sector. Concentrating investments in a single industry increases exposure to this type of risk." (Reference:Segfunds-E313-2020-12-7ED, Chapter 1.4.9 Industry Risk)
138. Frage
Kevin owns a construction business and wants to take out accident and sickness insurance to protect his income in the event of disability. On his application form, he indicated that he had competed in motocross races over the past five years. What requirements does Kevin need to comply with before the insurer can issue the policy?
Antwort: A
Begründung:
Comprehensive and Detailed Explanation:
Motocross is high-risk, requiring a detailed questionnaire and frequency disclosure. Insurers may impose an exclusion rider (Chapter 7:Insurance Recommendation, Contract, and Service Needs).
Option A: Incorrect; misses activity risk.
Option B: Incomplete; lacks detail.
Option C: Incomplete; misses exclusion possibility.
Option D: Correct; full process with potential rider.
Reference: LLQP Accident and Sickness Insurance Manual, Chapter 7:Insurance Recommendation, Contract, and Service Needs.
139. Frage
Lydia, a 73-year-old retiree, has a large lump sum of non-registered money she intends to leave to her grandchildren upon her death. She has no need of this money personally, because she already benefits from a generous work pension and owns a sizeable RRIF. She wants to invest that lump sum in such a way that the capital is protected. She hopes it can grow in the long run when the market does well. As the investment grows, Lydia would like to have the opportunity to lock in the gains.
Which of the following investments would be most appropriate for her?
Antwort: A
Begründung:
Under the LLQP Segregated Funds and Annuities curriculum, Lydia's objectives clearly combine capital protection, growth potential, and estate planning considerations. She does not require income from the funds, wishes to preserve capital for her grandchildren, and wants the ability to lock in market gains over time. These criteria align most closely with segregated funds that include a reset feature.
Segregated funds are insurance-based investment products that provide market exposure while offering guarantees at maturity and upon death, typically at 75% or 100% of deposits (less withdrawals). This makes them particularly suitable for investors like Lydia who want to protect capital intended for heirs, even if markets decline before death. The LLQP study guide emphasizes that death benefit guarantees are a key advantage of segregated funds for estate planning, as they ensure a minimum payout regardless of market performance.
The reset feature is especially important in this scenario. A reset allows the contract owner to periodically
"lock in" investment gains by resetting the guaranteed amount to the current market value. If markets perform well, Lydia can reset the guarantee, thereby increasing the protected amount for her beneficiaries. This directly meets her desire to capture long-term growth while safeguarding those gains against future downturns.
The other options do not meet all of Lydia's requirements. A variable income annuity is designed to provide income, which Lydia does not need, and it does not allow access to capital for estate growth purposes. Index- based ETFs offer growth potential but provide no capital protection or guarantees. Market-linked GICs protect principal but typically cap upside growth and do not offer death benefit guarantees or the ability to reset guarantees over time.
The LLQP curriculum highlights segregated funds with reset features as an ideal solution for older investors with estate planning goals who want growth with downside protection. Therefore, the most appropriate investment for Lydia is segregated funds with a reset feature, making Option D the correct and fully verified answer.
140. Frage
......
Der Vorhang der Lebensbühne wird jederzeit geöffnet werden. Die Hauptsache ist, ob Sie spielen wollen oder einfach weglaufen. Diejenigen, die die Chancen ergreifen können, können Erfolg erlangen. Deshalb müssen Sie Fast2test wählen. Sie können jederzeit Ihre Fertigkeiten zeigen. Die Prüfungsmaterialien zur IFSE Institute LLQP Zertifizierungsprüfung von Fast2test ist die effziente Methode, die LLQP Prüfung zu bestehen. Mit LLQP Zertifikat können Sie Ihren Traum verwirklichen und Erfolg erlangen.
LLQP Online Praxisprüfung: https://de.fast2test.com/LLQP-premium-file.html
P.S. Kostenlose und neue LLQP Prüfungsfragen sind auf Google Drive freigegeben von Fast2test verfügbar: https://drive.google.com/open?id=1TxGLn-60DQNxLiSjtXN6Hi3P9V0A_ZVj