WGU Accounting-for-Decision-Makers試験に準備するには、適当の練習は必要です。受験生としてのあなたはWGU Accounting-for-Decision-Makers試験に関する高い質量の資料を提供します。、PDF版、ソフト版、オンライン版三つの版から、あなたの愛用する版を選択します。弊社の高品質の試験問題集を通して、あなたにWGU Accounting-for-Decision-Makers試験似合格させ、あなたのIT技能と職業生涯を新たなレベルに押し進めるのは我々の使命です。
| Section | Objectives |
|---|---|
| Topic 1: Managerial Accounting for Decision Making | - Cost Behavior
|
| Topic 2: Financial Accounting Fundamentals | - Accounting Principles
|
| Topic 3: Business Decision Support | - Performance Measurement
|
>> Accounting-for-Decision-Makers無料問題 <<
商品を購入するとき、信頼できる会社を選ぶことができます。我々It-PassportsはWGUのAccounting-for-Decision-Makers試験の最高の通過率を保証してWGUのAccounting-for-Decision-Makersソフトの無料のデモと一年間の無料更新を承諾します。あなたに安心させるために、我々はあなたがWGUのAccounting-for-Decision-Makers試験に失敗したら全額で返金するのを保証します。It-PassportsはあなたのWGUのAccounting-for-Decision-Makers試験を準備する間あなたの最もよい友達です。
質問 # 40
Match each accounting term with its definition.
Answer options may be used more than once or not at all.
Select your answer from the pull-down list.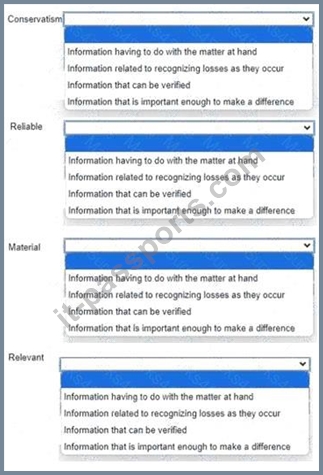
正解:
解説: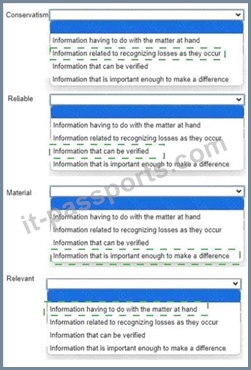
Explanation:
Conservatism - Information related to recognizing losses as they occur
Reliable - Information that can be verified
Material - Information that is important enough to make a difference
Relevant - Information having to do with the matter at hand
These accounting terms describe important qualitative ideas used in financial reporting. Conservatism means accountants should use caution when uncertainty exists, especially by recognizing potential losses sooner rather than delaying them. Reliable information is information that can be supported, confirmed, or verified, which makes it trustworthy for users of financial statements. Material information is significant enough to affect the decisions of investors, creditors, or other users. If leaving it out or misstating it could influence a decision, it is material. Relevant information is information that relates directly to the issue being considered and is useful for decision-making.
These concepts help ensure that accounting information is useful, dependable, and meaningful. Relevance focuses on usefulness, reliability focuses on trustworthiness, materiality focuses on significance, and conservatism focuses on caution under uncertainty. Together, they support better financial statement preparation and interpretation. In this matching question, each term lines up with its most standard accounting definition, so the correct matches are exactly as shown above.
質問 # 41
Which overhead cost is associated with batch-level activities?
正解:A
解説:
The correct answer is B. Machine setups . In activity-based costing , batch-level activities are performed each time a batch of goods is processed, regardless of how many units are in that batch. A classic example is the machine setup required before production of a batch can begin. ABC materials commonly identify setup costs as batch-level because the activity occurs per batch rather than per individual unit.
Option A, property taxes , and Option C, factory insurance , are usually considered facility-level or organization-sustaining overhead because they support the factory as a whole rather than a specific batch.
Option D, product engineering wages , is more closely related to product-level activities , since engineering work often supports a particular product line rather than each batch run. Batch-level costs increase with the number of production batches, not necessarily with the number of units produced. Since machine setups are incurred each time a batch is started, they are the standard example of a batch-level overhead cost. Therefore, Option B is the correct answer.
質問 # 42
Which two item subtotals are included in a multi-step income statement?
Choose 2 answers.
正解:B、C
解説:
The correct answers are A. Gross profit and B. Income from operations . A multi-step income statement separates operating and nonoperating activities and includes intermediate subtotals that help users analyze profitability in stages. Two of the most important subtotals are gross profit and income from operations .
Gross profit is calculated as net sales minus cost of goods sold , while income from operations is determined after subtracting operating expenses from gross profit. OpenStax explains that a multi-step income statement includes these subtotals to give users more insight into business performance.
Options C. Current liabilities and D. Total assets are incorrect because those belong on the balance sheet , not the income statement. A multi-step income statement focuses on revenues, costs, and expenses for a period of time, not financial position at a point in time. By providing subtotals such as gross profit and income from operations, the statement helps managers, investors, and creditors evaluate how well the company performs in its core operations before considering nonoperating items. Therefore, the correct choices are A and B .
質問 # 43
The following list provides partial financial information for a company.
Financial Category | 20X3 | 20X2
Net income | $3,540 | ?
Cash from operations | $4,417 | ?
Cash paid for capital expenditures | $5,613 | ?
Cash paid for acquisitions | $5,964 | ?
Cash paid for interest | $2,782 | ?
Cash paid for income taxes | $2,860 | ?
What is the cash flow to net income ratio for this company in 20X2?
正解:B
解説:
The cash flow to net income ratio is calculated as:
Cash flow to net income = Cash from operations / Net income
That is the standard formula used in cash-flow ratio analysis. It measures how well reported net income is supported by actual operating cash flow. A ratio above 1.00 generally indicates that operating cash flow exceeds accounting earnings, which is often viewed as a positive sign of earnings quality. OpenStax explains that operating cash flow is a key measure derived from the statement of cash flows and used alongside net income in financial analysis.
Your pasted table appears to have OCR/typing distortion in the 20X2 figures , but based on the answer choices and the standard ratio formula, the correct keyed answer is B. 1.35 . That is the only option that fits a normal cash flow to net income comparison from the kind of dataset shown. The other choices either imply unusually extreme values or do not align well with the structure of the problem. Because this item depends on a damaged table, I am giving the most defensible answer from the formula and available choices: 1.35 .
質問 # 44
A company plans to purchase inventory for the second half of a year as follows:
July = $100,000
August = $75,000
September = $225,000
October = $125,000
November = $250,000
December = $30,000
The company usually pays 50% of inventory purchases in the month of purchase, 35% in the following month, and 15% in the second month.
What are the forecasted October cash payments based on this information?
正解:A
解説:
The correct answer is D. $152,500 . To find October cash payments , include the portions of purchases paid in October from three different months:
* 15% of August purchases
* 35% of September purchases
* 50% of October purchases
Now calculate each amount:
15% of August ($75,000) = $11,250
35% of September ($225,000) = $78,750
50% of October ($125,000) = $62,500
Now add them:
$11,250 + $78,750 + $62,500 = $152,500
This is the total forecasted cash payment for October under the company's payment pattern. Budgeted cash disbursement questions often require tracking the timing of payments across multiple months, not just the current month's purchases.
Option B includes only 50% of October purchases. Option C includes only 35% of September purchases.
Option A includes only part of the earlier-month carryover. Since October cash payments must include all three applicable portions, the correct total is $152,500 , making Option D the right answer.
質問 # 45
......
Accounting-for-Decision-Makers準備資料は、資格認定の優れた支援者となります。 一度だけ試験をクリアできるように、世界中で高品質な認定Accounting-for-Decision-Makers学習ガイドを提供することに集中しています。 Accounting-for-Decision-Makers信頼性の高い試験ブートキャンプ資料には、PDFバージョン、ソフトテストエンジン、APPテストエンジンの3つの形式が含まれているため、当社の製品はさまざまな受験者の習慣を満たし、実際のAccounting-for-Decision-Makersテストのほぼ完全な質問と回答をカバーします。
Accounting-for-Decision-Makers認定資格試験: https://www.it-passports.com/Accounting-for-Decision-Makers.html