2026 Latest EduDump AFP-Exam-1 PDF Dumps and AFP-Exam-1 Exam Engine Free Share: https://drive.google.com/open?id=1WGfKlKDXN5niLYCGhRMywmkuFf1A6EJo
That's why EduDump offers actual Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) exam questions to help candidates pass the exam and save their resources. The CSI AFP-Exam-1 Exam Questions provided by EduDump is of the highest quality, and it enables participants to pass the exam on their first try.
| Section | Weight | Objectives |
|---|---|---|
| Professional Conduct and Regulatory Compliance | 10% | - Ethics and Professional Standards - Compliance Responsibilities - Regulatory Requirements |
| Tax Planning | 14% | - Registered Plans - Tax-Efficient Strategies - Income Tax Fundamentals - Tax Deductions and Credits |
| Investment Planning | 17% | - Asset Allocation - Portfolio Construction - Investment Theory - Investment Products |
| Client Relationship and Practice Management | 6% | - Client Discovery - Practice Management - Communication and Advisory Process |
| Asset and Liability Management | 11% | - Budgeting - Personal Balance Sheet Analysis - Cash Flow Management - Debt Management |
| Risk Management and Insurance | 12% | - Risk Assessment - Risk Transfer Strategies - Life Insurance - Disability and Health Insurance |
| Retirement Planning | 17% | - Retirement Income Strategies - Registered Retirement Savings Plans - Retirement Needs Analysis - Pension Plans |
| Estate Planning | 13% | - Estate Transfer Strategies - Wills - Trust and Beneficiary Planning - Powers of Attorney |
>> AFP-Exam-1 Valid Test Pattern <<
AFP-Exam-1 is the authentic study guides with the latest exam material which can help you solve all the difficulties in the actual test. Our AFP-Exam-1 free demo is available for all of you. You will receive an email attached with the AFP-Exam-1 training dumps within 5-10 minutes after completing purchase. Immediately download for the AFP-Exam-1 study pdf is available for study with no time wasted. We have money refund policy to ensure your interest in case the failure of AFP-Exam-1 actual test.
NEW QUESTION # 83
A retiree holds most of her investments in interest-bearing GICs inside a non-registered account while her TFSA is invested in cash. She has unused TFSA room and wants to improve after-tax efficiency without increasing total portfolio risk materially. What should the planner consider?
Answer: B
Explanation:
Interest income is fully taxable in a non-registered account, so sheltering interest-bearing assets in a TFSA can improve after-tax results without changing the underlying risk profile materially. If the retiree already wants conservative holdings, placing some GIC or high-interest savings exposure inside the TFSA may reduce annual taxable income and preserve capital. Option B changes the risk profile and is not responsive to the client's objective. Option C may be an estate or family-support decision, but it does not directly improve asset-location efficiency. Option D introduces leverage and repayment risk, which conflicts with the retiree's conservative profile. The planner should evaluate available TFSA room, maturity dates, liquidity needs, CDIC eligibility where relevant, estate beneficiary designations, and whether non-registered accrued interest will be triggered. The principle is asset location: tax-inefficient income is often better sheltered where possible, provided the recommendation remains suitable. References/topics: asset location, TFSA, interest income taxation, retirement portfolio efficiency.
NEW QUESTION # 84
Richard pays periodic spousal support and child support under a written separation agreement. Which statement is generally correct?
Answer: C
Explanation:
Tax treatment depends on the type of support. Periodic spousal support paid under a qualifying written agreement or court order is generally deductible to the payer and taxable to the recipient. Child support is generally not deductible to the payer and not taxable to the recipient. Option B wrongly treats child support like deductible spousal support. Option C confuses payment frequency with tax character; monthly payment does not make child support taxable. Option D is plainly incorrect because spousal support can materially affect after-tax cash flow for both parties. A financial planner should distinguish periodic support from lump- sum settlements, property transfers, arrears, legal fees, and combined agreements because classification changes projections. The planner should also ensure tax assumptions follow the wording of the agreement and should recommend legal or tax advice where facts are unclear. The planning result is measured on after-tax cash flow, not simply the gross support amount. References/topics: support payments, divorce planning, cash flow, tax deductibility.
NEW QUESTION # 85
Sapphire, age 35, a recent widow, is still in the grieving stage. She has just received a large insurance payout.
She has limited savings, a long-term time horizon, and a high tolerance for risk. What investment strategy should her financial planner recommend until Sapphire is better able to understand her new situation?
Answer: A
Explanation:
Sapphire's technical risk tolerance is not the only planning factor. She is recently widowed, grieving, inexperienced in her new financial position, and has received a large insurance payout. A planner should avoid pushing her into a moderate or high-risk portfolio before she can make stable, informed decisions about goals, income needs, debts, taxes, and estate intentions. A high-interest savings account preserves capital, maintains liquidity, and buys time for the planning process. A ladder of GICs may eventually be suitable, but traditional and index-linked GICs still lock in terms or introduce product features she may not yet understand.
A high-risk portfolio would be especially inappropriate during the immediate transition period. The temporary recommendation is not a long-term asset-allocation decision; it is a prudent holding strategy until discovery and emotional readiness improve. Study Guide focus: major life events, client vulnerability, liquidity, temporary cash management, and suitability. This temporary parking approach is common after bereavement, divorce, inheritance, or business sale proceeds.
NEW QUESTION # 86
Jackson, a wealth advisor, is helping Terry, a self-employed IT professional, determine his net income. The goal is to develop a budget and savings strategy for the year ahead Terry has provided the information below: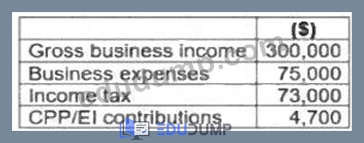
What is Terry's net business income?
Answer: D
Explanation:
Terry's net business income is $225,000. The calculation starts with gross business income of $300,000 and subtracts deductible business expenses of $75,000. Income tax is not deducted in computing net business income for this purpose; it is calculated after taxable income is determined. CPP/EI contributions are also not treated as ordinary business expenses in this basic net business income calculation. Option A and option B incorrectly subtract personal tax and statutory contribution amounts. Option D subtracts the CPP/EI amount from business profit but still incorrectly treats it as part of the business-income calculation. The planner needs the correct net business income figure because it drives budgeting, savings capacity, tax installments, retirement contribution planning, insurance affordability, and debt-service analysis. AFP cash-flow work separates business operating results from personal tax payments and after-tax cash flow. Study Guide focus:
self-employment income, deductible business expenses, net income, tax planning, and budgeting.
NEW QUESTION # 87
Jaycee has created an investment portfolio for his client, Adam, which is designed to achieve his long-term objectives and is consistent with his risk tolerance and constraints. It also has to be reassessed periodically to ensure that the long-term benchmark mix continues to reflect Adam's circumstances. Which asset allocation strategy is Jaycee utilizing?
Answer: B
Explanation:
Jaycee is using strategic asset allocation. The portfolio is built around Adam's long-term objectives, risk tolerance, constraints, and benchmark mix, then reassessed periodically to confirm that the policy allocation still fits his circumstances. Strategic allocation is not an attempt to move aggressively between sectors or asset classes based on near-term forecasts. Tactical allocation would involve short-term deviations from the policy mix to exploit perceived market opportunities. Active management refers to security selection or manager decisions intended to outperform a benchmark. Integrated is not the standard allocation term being tested. The AFP course treatment emphasizes that the long-term asset mix is the primary driver of portfolio risk and return; periodic review and rebalancing keep the portfolio aligned with the plan. Jaycee's process is disciplined, policy-based, and client-specific, which is strategic allocation. Study Guide focus: strategic asset allocation, rebalancing, investment policy, risk tolerance, and long-term benchmark mix. The review does not replace the policy mix; it tests whether the policy mix still remains appropriate.
NEW QUESTION # 88
......
Our company is professional brand. There are a lot of experts and professors in the field in our company. All the experts in our company are devoting all of their time to design the best AFP-Exam-1test question for all people. In order to ensure quality of the products, a lot of experts keep themselves working day and night. We can make sure that you cannot find the more suitable AFP-Exam-1certification guide than our study materials, so hurry to choose the study materials from our company as your study tool, it will be very useful for you to prepare for the AFP-Exam-1 exam.
AFP-Exam-1 Verified Answers: https://www.edudump.com/exams/CSI/AFP-Exam-1/
P.S. Free 2026 CSI AFP-Exam-1 dumps are available on Google Drive shared by EduDump: https://drive.google.com/open?id=1WGfKlKDXN5niLYCGhRMywmkuFf1A6EJo