It is known to us that having a good job has been increasingly important for everyone in the rapidly developing world; it is known to us that getting a PF1 certification is becoming more and more difficult for us. If you are tired of finding a high quality study material, we suggest that you should try our PF1 Exam Prep. Because our materials not only has better quality than any other same learn products, but also can guarantee that you can pass the PF1 exam with ease.
| Section | Objectives |
|---|---|
| Topic 1: Record of Employment | - ROE processing
|
| Topic 2: Payroll Accounting | - Payroll accounting practices
|
| Topic 3: Year-End Processing | - Federal and provincial year-end reporting
|
| Topic 4: Non-Statutory Deductions | - Voluntary deductions
|
| Topic 5: Employment Income – Regular Earnings | - Regular payroll calculations
|
| Topic 6: Federal Remittances | - Government remittance obligations
|
| Topic 7: Employment Income – Allowances, Expenses and Benefits | - Taxable and non-taxable benefits
|
| Topic 8: Provincial Remittances | - Provincial payroll requirements
|
| Topic 9: Termination of Employment | - Termination processing
|
| Topic 10: Non-Regular Payments | - Special payroll payments
|
| Topic 11: New Employee Information | - Employee setup and documentation
|
| Topic 12: Commission Payments | - Commission payroll processing
|
| Topic 13: Workers’ Compensation | - Workers compensation administration
|
Through all these years' experience, our PF1 training materials are becoming more and more prefect. Moreover, we hold considerate after-sales services and sense-and-respond tenet all these years. So if you get any questions of our PF1 learning guide, please get us informed. It means we will deal with your doubts with our PF1 practice materials 24/7 with efficiency and patience.
NEW QUESTION # 67
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)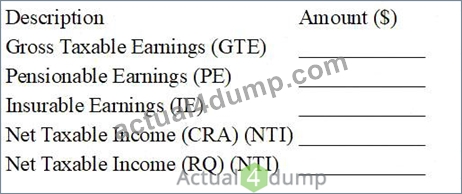
STATUTORY DEDUCTIONS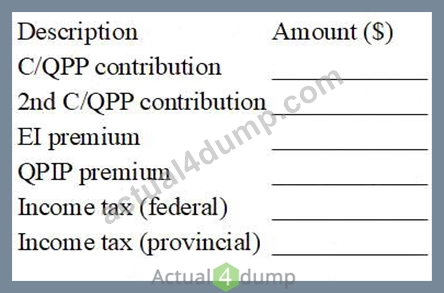
OTHER DEDUCTIONS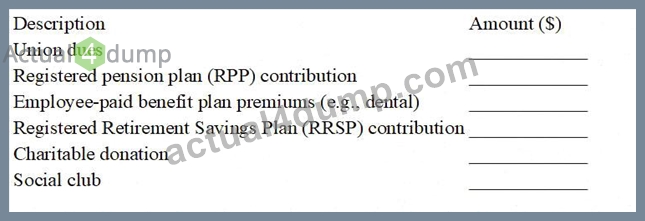
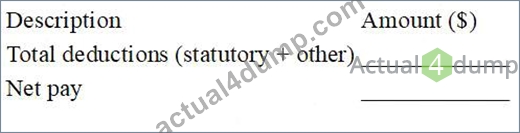
Given Data (Reference)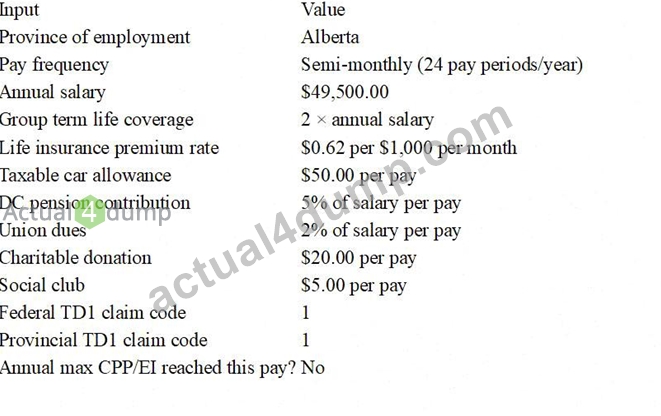
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
NEW QUESTION # 68
Rosa joined Avion Electronics in April 1983. Her employment was terminated on November 30, 2015 and she was paid a $62,500.00 retiring allowance. Rosa joined her company's pension plan in 1986 and was fully vested on termination of employment. Calculate the non-eligible portion of the retiring allowance.
Answer:
Explanation:
$32,000.00 non-eligible portion
Explanation:
CRA requires separating a retiring allowance into an eligible and non-eligible portion. The eligible portion is the maximum that can be transferred to an RRSP/RPP under the special rules (without using regular RRSP room). The formula is: $2,000 for each year (or part-year) of service before 1996, plus an additional $1,500 for each year (or part-year) before 1989 in which the employee had no employer pension/DPSP benefit vested at the time of payment (or previously paid).
Rosa worked from 1983 to 1995 (inclusive) for pre-1996 service: 13 years × $2,000 = $26,000.
For the extra pre-1989 amount: she joined the pension plan in 1986 and was fully vested when paid the retiring allowance in 2015, so 1986-1988 do not qualify for the extra $1,500. However, 1983-1985 were years before 1989 when she had no vested employer pension benefit, so 3 years × $1,500 = $4,500.
Eligible portion = $26,000 + $4,500 = $30,500.
Non-eligible portion = $62,500 # $30,500 = $32,000.
NEW QUESTION # 69
Paul Westin works for an Alberta organization and receives a regular salary of $1,800.00 semi-monthly. He will be receiving a payout of accrued vacation with no time taken of $1,400.00 on a separate cheque. He has federal and provincial TD1s on file with claim code 1. Calculate the income taxes to be withheld on his vacation pay.
Answer:
Explanation:
341.50
Explanation:
CRA's method for bonus/irregular payments paid separately is to calculate income tax on the combined pay (regular pay + the irregular payment) using the regular tax tables, then subtract the tax that would apply to the regular pay alone. The difference is the income tax to withhold from the irregular payment.
Here, the semi-monthly taxable pay is:
Regular pay = $1,800.00
Regular + vacation payout = $3,200.00
Using the 2026 Alberta semi-monthly (24 pay periods) tax tables with claim code 1:
At $1,800, Federal tax = $130.45 and Alberta tax = $58.55 # Total = $189.00.
At $3,200, Federal tax = $356.50 and Alberta tax = $174.00 # Total = $530.50.
Income tax on the vacation payout = $530.50 # $189.00 = $341.50.
CPP (including the enhanced portion) is a separate statutory deduction that must also be calculated on the payout, but this question asked specifically for income tax withholding.
NEW QUESTION # 70
A premium payment for overtime hours worked or a rate per piece of goods produced is an example of:
Answer: A
Explanation:
Overtime premiums and piece-rate pay are forms of earnings because they are amounts paid for work performed. CRA's payroll guidance confirms overtime pay is remuneration from which you must deduct statutory deductions (CPP, EI, and income tax), reflecting that overtime is treated as employment earnings.
Similarly, piecework (piece-rate pay) is a method of paying wages based on units produced rather than time.
It is still compensation for labour and therefore part of gross earnings used to calculate payroll deductions and net pay. This is fundamentally different from:
Expense reimbursements, which repay employee-incurred business costs (not pay for work).
Allowances, which are predetermined amounts to help cover anticipated expenses without receipts.
Benefits, which are the value of goods/services provided by the employer or paid on the employee's behalf.
So a premium paid for overtime hours or a piece-rate per unit produced is classified as earnings (option A).
NEW QUESTION # 71
Charmaine's employment was terminated by her employer on April 13 of the current year. Charmaine had worked for her employer for 3 years and was paid 3 weeks of legislated wages in lieu of notice and two weeks' vacation pay with her final pay. What date should be recorded in Block 11 on Charmaine's Record of Employment?
Answer: D
Explanation:
Block 11 on the ROE is the "Last day for which paid," meaning the last day the employee received insurable earnings. In most terminations, this is the employee's last day of work. Service Canada notes Block 11 only moves beyond the last day worked when the employee continues to receive insurable earnings after the last day of work due to paid leave (such as vacation leave or sick leave) or salary continuance.
In this question, Charmaine's employment ended April 13, and she received a lump-sum final pay that included wages in lieu of notice and vacation pay. These amounts are typically reported as special payments (for example, pay in lieu of notice is reported as such), but they do not automatically change Block 11 unless they are paid as an actual paid-leave period or as salary continuance (where regular pay continues and the ROE is not issued until the continuance ends).
NEW QUESTION # 72
......
PF1 certifications are one of the most popular certifications currently. Earning PF1 certification credentials is easy, in first attempt, with the help of products. Actual4dump is well-reputed brand among the professional. That provides the best preparation materials for PF1 Certification exams. Actual4dump has a team of PF1 subject experts to develop the best products for PF1 certification exam preparation.
Valid Braindumps PF1 Book: https://www.actual4dump.com/National-Payroll-Institute/PF1-actualtests-dumps.html