Our PF1 certification has great effect in this field and may affect your career even future. PF1 real questions files are professional and high passing rate so that users can pass exam at the first attempt. High quality and pass rate make us famous and growing faster and faster. Many candidates compliment that PF1 Study Guide materials are best assistant and useful for qualification exams, and only by practicing our PF1 exam braindumps several times before exam, they can pass PF1 exam in short time easily.
| Section | Objectives |
|---|---|
| New Employee Information | - Employee setup and documentation
|
| Commission Payments | - Commission payroll processing
|
| Provincial Remittances | - Provincial payroll requirements
|
| Year-End Processing | - Federal and provincial year-end reporting
|
| Record of Employment | - ROE processing
|
| Non-Statutory Deductions | - Voluntary deductions
|
| Employment Income – Regular Earnings | - Regular payroll calculations
|
| Termination of Employment | - Termination processing
|
| Federal Remittances | - Government remittance obligations
|
| Non-Regular Payments | - Special payroll payments
|
| Employment Income – Allowances, Expenses and Benefits | - Taxable and non-taxable benefits
|
| Workers’ Compensation | - Workers compensation administration
|
| Payroll Accounting | - Payroll accounting practices
|
When they will be giving their final examination to get National Payroll Institute PF1 certification they don't struggle much and do it easily. The results of the customizable PF1 exam dumps can then be used to identify areas of strength and weakness and to create a personalized study plan that focuses on improving in the areas that need the most work. Taking PF1 Practice Tests regularly could help individuals build their confidence, reduce test anxiety, and improve their overall performance.
NEW QUESTION # 64
By the authority of which Act can the Canada Revenue Agency garnish the wages of an employee who has failed to pay Employment Insurance premiums, Canada Pension Plan contributions, or income tax deductions?
Answer: D
Explanation:
The CRA's wage garnishment tool is commonly issued as a Requirement to Pay (RTP) (and related instruments such as ERTP/DTP), which directs a third party (often the employer) to redirect amounts that would otherwise be paid to the employee, and send them to the government instead. CRA guidance explains that when an employee owes money, the CRA can send the employer a requirement to pay notice, and the employer must remit the amounts as instructed (or the employer can become liable).
The legal authority for the CRA to issue a Requirement to Pay is found in the Income Tax Act, including section 224, which sets out the mechanism and consequences for non-compliance.
In payroll operations, this is a communication-and-compliance issue: payroll must correctly interpret the notice, apply the withholding/remittance as directed, and communicate impacts to internal stakeholders (HR
/finance) and, where appropriate, the affected employee-while ensuring the remittance is made exactly as the CRA notice requires.
NEW QUESTION # 65
National Hardware, an Ontario organization, will be terminating the employment of Emilie St. Germain on October 28, 2019, the last day of the pay period. Emilie started with National Hardware on September 19,
2007. Complete the paper Record of Employment (ROE) for Emilie based on the information provided in the following chart.
Note: Vacationable earnings already include the pay in lieu of notice.
All dates must be entered in the format DDMMYYYY.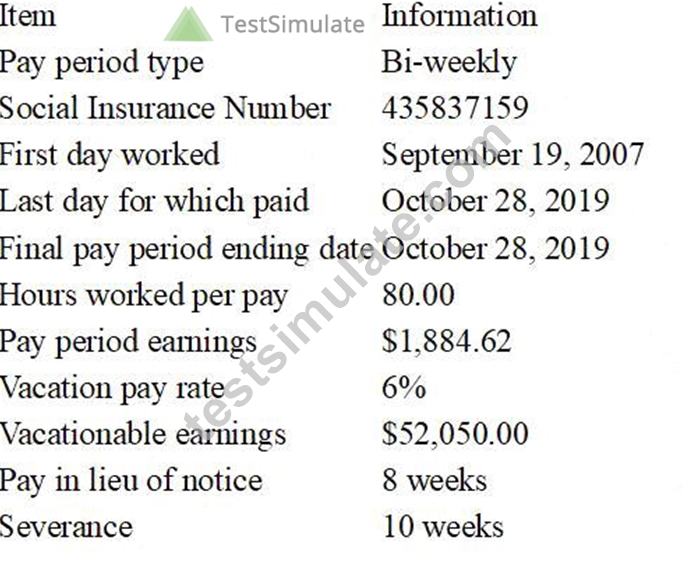
Paper ROE (Form Reference)
Complete the following paper ROE blocks for Emilie:
Block 6 - Pay period type
Block 8 - Social Insurance Number
Block 10 - First day worked
Block 11 - Last day for which paid
Block 12 - Final pay period ending date
Block 15A - Total insurable hours
Block 15B - Total insurable earnings
Block 17A - Vacation pay
Block 17C - Other monies (Pay in lieu of notice)
Block 17C - Other monies (Severance)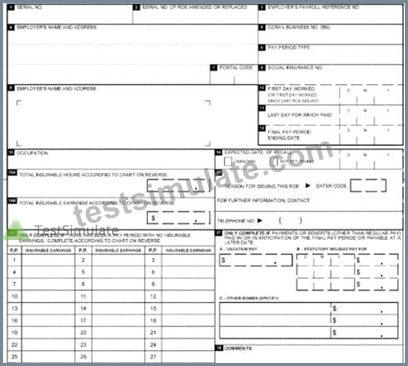
Step 1 - Complete Block 6
Enter the pay period type for Emilie.
Step 2 - Complete Block 8
Enter Emilie's Social Insurance Number.
Step 3 - Complete Block 10
Enter Emilie's first day worked in DDMMYYYY format.
Step 4 - Complete Block 11
Enter Emilie's last day for which paid in DDMMYYYY format.
Step 5 - Complete Block 12
Enter the final pay period ending date in DDMMYYYY format.
Step 6 - Complete Block 15A
Calculate and enter total insurable hours.
Given:
Hours worked per pay period = 80.00
Bi-weekly ROE pay period chart captures 27 pay periods
Step 7 - Complete Block 15B
Calculate and enter total insurable earnings.
Given:
Pay period earnings = $1,884.62
Bi-weekly ROE pay period chart captures 27 pay periods
Step 8 - Complete Block 17A
Calculate and enter vacation pay.
Given:
Vacation pay rate = 6%
Vacationable earnings = $52,050.00
(already includes pay in lieu of notice)
Step 9 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Pay in lieu of notice.
Given:
Pay in lieu of notice = 8 weeks
Use weekly earnings derived from the bi-weekly pay period earnings.
Step 10 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Severance.
Given:
Severance = 10 weeks
Use the same weekly earnings used in Step 9.
Answer:
Explanation:
See the Below Explanation for complete Solution.
Explanation:
Step 1 - Block 6
Bi-weekly
Step 2 - Block 8
435837159
Step 3 - Block 10
September 19, 2007 # 19092007
Step 4 - Block 11
October 28, 2019 # 28102019
Step 5 - Block 12
October 28, 2019 # 28102019
Step 6 - Block 15A (Total insurable hours)
80.00 × 27 = 2160
Block 15A = 2160
Step 7 - Block 15B (Total insurable earnings)
$1,884.62 × 27 = $50,884.74
Block 15B = 50,884.74
Step 8 - Block 17A (Vacation pay)
$52,050.00 × 6% = $3,123.00
Block 17A = 3,123.00
Step 9 - Block 17C (Pay in lieu of notice)
Weekly earnings = $1,884.62 ÷ 2 = $942.31
Pay in lieu = $942.31 × 8 = $7,538.48
Block 17C (Pay in lieu of notice) = 7,538.48
Step 10 - Block 17C (Severance)
Severance = $942.31 × 10 = $9,423.10
Block 17C (Severance) = 9,423.10
NEW QUESTION # 66
Rosa joined Avion Electronics in April 1983. Her employment was terminated on November 30, 2015 and she was paid a $62,500.00 retiring allowance. Rosa joined her company's pension plan in 1986 and was fully vested on termination of employment. Calculate the non-eligible portion of the retiring allowance.
Answer:
Explanation:
$32,000.00 non-eligible portion
Explanation:
CRA requires separating a retiring allowance into an eligible and non-eligible portion. The eligible portion is the maximum that can be transferred to an RRSP/RPP under the special rules (without using regular RRSP room). The formula is: $2,000 for each year (or part-year) of service before 1996, plus an additional $1,500 for each year (or part-year) before 1989 in which the employee had no employer pension/DPSP benefit vested at the time of payment (or previously paid).
Rosa worked from 1983 to 1995 (inclusive) for pre-1996 service: 13 years × $2,000 = $26,000.
For the extra pre-1989 amount: she joined the pension plan in 1986 and was fully vested when paid the retiring allowance in 2015, so 1986-1988 do not qualify for the extra $1,500. However, 1983-1985 were years before 1989 when she had no vested employer pension benefit, so 3 years × $1,500 = $4,500.
Eligible portion = $26,000 + $4,500 = $30,500.
Non-eligible portion = $62,500 # $30,500 = $32,000.
NEW QUESTION # 67
Benefits are:
Answer: D
Explanation:
In Canadian payroll, a benefit generally means the employer has provided something of value to the employee (or paid for something on the employee's behalf), rather than paying cash for work performed. The CRA's Employers' Guide - Taxable Benefits and Allowances (T4130)explains that a benefit/allowance may be provided in cash (for example, an allowance) or in a manner other than cash (for example, a parking space or gift), and that employers may have to include the value of that benefit/allowance in the employee's income depending on the circumstances.
Option C best captures this "value of something provided or paid for" concept. Option B describes wages
/salary (earnings for work). Option A aligns more with reimbursements/expense coverage. Option D aligns with allowances for business use of personal property (often treated separately and may be taxable or non- taxable depending on CRA rules and documentation). Payroll's role is to determine whether the benefit is taxable, value it correctly, and apply the right statutory withholdings and reporting.
NEW QUESTION # 68
What is piecework?
Answer: B
Explanation:
Piecework (also called piece-rate pay) is a pay method where an employee's earnings are determined by output-they are paid a set amount per unit produced or completed, rather than by hours worked or a fixed salary. This aligns directly with option C. A time-based hourly/daily wage (option A) is a different earnings method, and a fixed pay-per-period arrangement (option B) describes salary. Therefore, "all of the above" is incorrect because these are three distinct compensation structures.
In payroll calculations, piecework earnings are typically calculated as: piece rate × number of units produced in the pay period. Employers still have to ensure compliance with employment standards, such as minimum wage and overtime rules, even where piecework is used. A Canadian payroll educational reference defines piecework as payment for each unit produced "regardless of the amount of time taken."
NEW QUESTION # 69
......
As we know, our products can be recognized as the most helpful and the greatest PF1 study engine across the globe. Even though you are happy to hear this good news, you may think our price is higher than others. We can guarantee that we will keep the most appropriate price because we want to expand our reputation of PF1 Preparation dumps in this line and create a global brand. What’s more, we will often offer abundant discounts of PF1 study guide to express our gratitude to our customers.
PF1 Study Reference: https://www.testsimulate.com/PF1-study-materials.html