ExamPassdump에는 전문적인 업계인사들이CSI AFP-Exam-1시험문제와 답에 대하여 연구하여, 시험준비중인 여러분들한테 유용하고 필요한 시험가이드를 제공합니다. 만약ExamPassdump의 제품을 구매하려면, 우리ExamPassdump에서는 아주 디테일 한 설명과 최신버전 최고품질의자료를 즉적중율이 높은 문제와 답을제공합니다.CSI AFP-Exam-1자료는 충분한 시험대비자료가 될 것입니다. 안심하시고 ExamPassdump가 제공하는 상품을 사용하시고, 100%통과 율을 확신합니다.
| Section | Weight | Objectives |
|---|---|---|
| Enabling Competencies | 16% | - Professional Conduct and Regulatory Compliance - Client Relationship and Practice Management |
| Technical Competencies | 84% | - Investment Planning - Risk Management and Insurance - Asset and Liability Management - Tax Planning - Estate Planning - Retirement Planning |
성공으로 향하는 길에는 많은 방법과 방식이 있습니다. CSI인증 AFP-Exam-1시험을 패스하는 길에는ExamPassdump의CSI인증 AFP-Exam-1덤프가 있습니다. ExamPassdump의CSI인증 AFP-Exam-1덤프는 실제시험 출제방향에 초점을 두어 연구제작한 시험준비공부자료로서 높은 시험적중율과 시험패스율을 자랑합니다.국제적으로 승인해주는 IT자격증을 취득하시면 취직 혹은 승진이 쉬워집니다.
질문 # 58
Jenny and Herman are looking for tax strategies that will help them better manage their marginal annual tax rates. Jenny is currently the primary income earner in the household. She has a large non-registered portfolio that holds only plain vanilla S & P 500 index funds. Jenny and Herman have a 14-year-old daughter, and they would also like to know what income-splitting opportunities exist. They've presented several ideas to their tax planner, Isaac, for review. Which of the following will likely result in tax attribution to Jenny?
정답:C
설명:
Jenny's gift to her minor daughter is the transaction most likely to trigger attribution back to Jenny. When a high-income parent transfers income-producing property to a minor child, income such as interest and dividends generally attributes back to the parent. The rule prevents simple income splitting by gift. A spousal RRSP converted to a RRIF can avoid attribution on required minimum RRIF withdrawals, subject to detailed timing rules. A sale of securities to Herman at fair market value can avoid attribution if proper consideration is paid and the transaction is documented. A prescribed-rate loan to Herman can also avoid attribution if interest is charged at the prescribed rate and paid by the required deadline. The key AFP issue is distinguishing prohibited income splitting from properly structured transfers or loans. The minor-child gift in option A is the clearly attributive arrangement. Study Guide focus: attribution rules, minor children, spousal transfers, prescribed-rate loans, and family tax planning.
질문 # 59
Jonathan owns a medium size consulting firm and earns an average annual income of $150,000. He is reviewing his retirement plan with his financial planner. Jonathan asked his planner about retirement compensation arrangement and how this may benefit him. What should his financial planner tell him?
정답:A
설명:
A retirement compensation arrangement can benefit an executive because it does not use RRSP contribution room and is not subject to the ordinary registered pension and RRSP contribution limits. It is an employer- sponsored supplemental retirement arrangement often used where standard registered plan limits are insufficient for high-income employees or owner-managers. Withdrawals are not tax-exempt; benefits are generally taxable when received, so option A and option C misstate the tax treatment. Option D incorrectly says it reduces RRSP room. RCAs are also subject to refundable tax mechanics and require careful administration, so the planner should not present them as simple savings accounts. Jonathan's planner should explain that the value is supplemental retirement funding above regular limits, balanced against cost, complexity, cash-flow needs, and tax timing. Study Guide focus: retirement compensation arrangements, executive benefits, RRSP contribution room, supplemental pensions, and tax deferral. The planner should also explain that RCAs are complex and usually suited only where the employer can fund the arrangement.
질문 # 60
A household has gross monthly income of $9,500. Their monthly mortgage payment is $2,100, property taxes are $425, heating costs are $175, car payments are $600, and minimum credit card payments are $250. What is their total debt service ratio?
정답:D
설명:
Total debt service ratio includes housing debt costs plus other recurring debt obligations. The monthly obligations are: mortgage $2,100, property taxes $425, heating $175, car payments $600, and credit card minimums $250. Total monthly debt service is $3,550. Dividing $3,550 by gross monthly income of $9,500 gives 0.3737, or approximately 37.4%. Option A is close to a housing-only calculation that omits non- mortgage debt. Option B still understates the total obligation. Option D is too high based on the numbers provided. Debt service ratios help assess borrowing capacity, but they are not the entire planning answer. A planner should also test stability of employment, emergency reserves, renewal risk, variable-rate exposure, childcare costs, and discretionary spending. In this question, however, the calculation itself is decisive: all stated recurring debt obligations must be included for the total debt service ratio. References/topics: TDS ratio, mortgage affordability, liability analysis, cash flow planning.
질문 # 61
Consider the following information for a client's portfolio: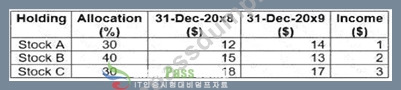
What is the annual rate of return for this portfolio?
정답:A
설명:
The portfolio return must combine price change and income for each holding, then weight each holding by its allocation. Stock A rises from $12 to $14 and pays $1 of income, producing a return of ($14 + $1 - $12) / $12
= 25%. Stock B falls from $15 to $13 but pays $2, producing a 0% total return. Stock C falls from $18 to $17 and pays $3, producing ($17 + $3 - $18) / $18 = 11.11%. Applying the allocation weights gives 30% × 25%, plus 40% × 0%, plus 30% × 11.11%, which is approximately 10.8%. The answer is not based only on market value movement and not on a simple average of the three returns. AFP investment calculations require total return and allocation weighting. Study Guide focus: portfolio return, income return, capital return, weighted averages, and performance measurement. This is why the answer is a weighted total-return figure, not a yield figure or a price-only performance measure.
질문 # 62
A retiree holds most of her investments in interest-bearing GICs inside a non-registered account while her TFSA is invested in cash. She has unused TFSA room and wants to improve after-tax efficiency without increasing total portfolio risk materially. What should the planner consider?
정답:C
설명:
Interest income is fully taxable in a non-registered account, so sheltering interest-bearing assets in a TFSA can improve after-tax results without changing the underlying risk profile materially. If the retiree already wants conservative holdings, placing some GIC or high-interest savings exposure inside the TFSA may reduce annual taxable income and preserve capital. Option B changes the risk profile and is not responsive to the client's objective. Option C may be an estate or family-support decision, but it does not directly improve asset-location efficiency. Option D introduces leverage and repayment risk, which conflicts with the retiree's conservative profile. The planner should evaluate available TFSA room, maturity dates, liquidity needs, CDIC eligibility where relevant, estate beneficiary designations, and whether non-registered accrued interest will be triggered. The principle is asset location: tax-inefficient income is often better sheltered where possible, provided the recommendation remains suitable. References/topics: asset location, TFSA, interest income taxation, retirement portfolio efficiency.
질문 # 63
......
CSI AFP-Exam-1덤프를 구매하시기전에 사이트에서 해당 덤프의 무료샘플을 다운받아 덤프품질을 체크해보실수 있습니다. AFP-Exam-1덤프를 구매하시면 구매일로부터 1년내에 덤프가 업데이트될때마다 업데이트된 버전을 무료로 제공해드립니다.CSI AFP-Exam-1덤프 업데이트 서비스는 덤프비용을 환불받을시 자동으로 종료됩니다.
AFP-Exam-1적중율 높은 시험대비덤프: https://www.exampassdump.com/AFP-Exam-1_valid-braindumps.html