DOWNLOAD the newest ExamCost PF1 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1gDRvV60QGn61OEL1Da3Ccp3CC93d9pbB
Today, the IT industry is facing fierce competition, you will feel powerless, this is inevitable. All you have to do is to escort your career. Of course, you have many choices. I recommend that you use the ExamCost National Payroll Institute PF1 Exam Questions And Answers, it is a good helper to help your success of IT certification. So what you still waiting for, go to get new ExamCost National Payroll Institute PF1 exam training materials early.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Individual Pay Calculations | 40% | - Non-regular earnings
|
| Topic 2: Termination and Special Payments | 30% | - Leaves and absences
|
| Topic 3: Communication and Compliance | 10% | - Stakeholder communication
|
| Topic 4: Record of Employment (ROE) | 20% | - Submission and deadlines
|
As a worldwide leader in offering the best PF1 test torrent, we are committed to providing comprehensive service to the majority of consumers and strive for constructing an integrated service. What’s more, we have achieved breakthroughs in PF1 certification training application as well as interactive sharing and after-sales service. A good deal of researches has been made to figure out how to help different kinds of candidates to get Payroll Fundamentals 1Exam certification. We revise and update the Payroll Fundamentals 1Exam guide torrent according to the changes of the syllabus and the latest developments in theory and practice. We base the PF1 Certification Training on the test of recent years and the industry trends through rigorous analysis.
NEW QUESTION # 10
In which province or territory is the employer-paid premium for private health insurance coverage that includes dental and prescription coverage considered to be a non-cash taxable benefit?
Answer: B
Explanation:
In Quebec, employer-paid premiums (contributions) to a group insurance plan, including a private health services plan (which commonly covers items like dental and prescription drugs), are treated as a taxable benefit for the employee for Quebec purposes. Revenu Quebec explicitly states that contributions (premiums) an employer pays under a group insurance plan for coverage received by an employee constitute a taxable benefit.
Because the employer is paying the premium directly to the insurer (the employee receives coverage rather than cash), this is treated as a non-cash taxable benefit in payroll classification terms. The payroll impact is that this taxable benefit must be included in the employee's Quebec taxable income and reported on the RL-1 (and handled according to Quebec source deduction rules).
Outside Quebec, employer-paid health/dental plan premiums are generally not treated the same way for provincial taxable benefit purposes, which is why the correct answer among the options is Quebec.
NEW QUESTION # 11
Which of the following types of payments made by a private organization would not be subject to all statutory deductions?
Answer: A
Explanation:
The payment type most clearly not subject to all statutory deductions is directors' fees. CRA guidance on directors' fees shows they are treated as a special payment with distinct deduction rules, and (depending on the situation) they may not have CPP, EI, and income tax all apply in the same way as normal employment earnings.
By contrast, retroactive adjustments and performance bonuses are treated as taxable remuneration where CRA' s tools (like PDOC) calculate CPP contributions, EI premiums, and income tax on those payments (up to annual maximums).
"Vacation pay when no time was taken" is also treated as a non-periodic payment and is included in CRA payroll deduction formulas as a type of amount on which statutory deductions are calculated (again, subject to annual maximums for CPP/EI).
So, among the options listed, directors' fees are the one that would not necessarily be subject to all statutory deductions in the standard way.
NEW QUESTION # 12
National Hardware, an Ontario organization, will be terminating the employment of Emilie St. Germain on October 28, 2019, the last day of the pay period. Emilie started with National Hardware on September 19,
2007. Complete the paper Record of Employment (ROE) for Emilie based on the information provided in the following chart.
Note: Vacationable earnings already include the pay in lieu of notice.
All dates must be entered in the format DDMMYYYY.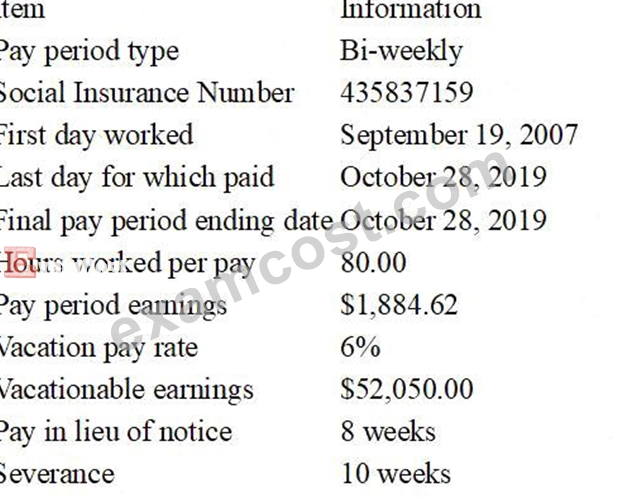
Paper ROE (Form Reference)
Complete the following paper ROE blocks for Emilie:
Block 6 - Pay period type
Block 8 - Social Insurance Number
Block 10 - First day worked
Block 11 - Last day for which paid
Block 12 - Final pay period ending date
Block 15A - Total insurable hours
Block 15B - Total insurable earnings
Block 17A - Vacation pay
Block 17C - Other monies (Pay in lieu of notice)
Block 17C - Other monies (Severance)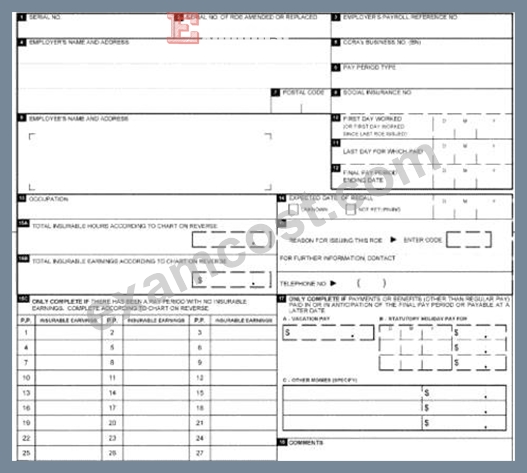
Step 1 - Complete Block 6
Enter the pay period type for Emilie.
Step 2 - Complete Block 8
Enter Emilie's Social Insurance Number.
Step 3 - Complete Block 10
Enter Emilie's first day worked in DDMMYYYY format.
Step 4 - Complete Block 11
Enter Emilie's last day for which paid in DDMMYYYY format.
Step 5 - Complete Block 12
Enter the final pay period ending date in DDMMYYYY format.
Step 6 - Complete Block 15A
Calculate and enter total insurable hours.
Given:
Hours worked per pay period = 80.00
Bi-weekly ROE pay period chart captures 27 pay periods
Step 7 - Complete Block 15B
Calculate and enter total insurable earnings.
Given:
Pay period earnings = $1,884.62
Bi-weekly ROE pay period chart captures 27 pay periods
Step 8 - Complete Block 17A
Calculate and enter vacation pay.
Given:
Vacation pay rate = 6%
Vacationable earnings = $52,050.00
(already includes pay in lieu of notice)
Step 9 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Pay in lieu of notice.
Given:
Pay in lieu of notice = 8 weeks
Use weekly earnings derived from the bi-weekly pay period earnings.
Step 10 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Severance.
Given:
Severance = 10 weeks
Use the same weekly earnings used in Step 9.
Answer:
Explanation:
See the Below Explanation for complete Solution.
Explanation:
Step 1 - Block 6
Bi-weekly
Step 2 - Block 8
435837159
Step 3 - Block 10
September 19, 2007 # 19092007
Step 4 - Block 11
October 28, 2019 # 28102019
Step 5 - Block 12
October 28, 2019 # 28102019
Step 6 - Block 15A (Total insurable hours)
80.00 × 27 = 2160
Block 15A = 2160
Step 7 - Block 15B (Total insurable earnings)
$1,884.62 × 27 = $50,884.74
Block 15B = 50,884.74
Step 8 - Block 17A (Vacation pay)
$52,050.00 × 6% = $3,123.00
Block 17A = 3,123.00
Step 9 - Block 17C (Pay in lieu of notice)
Weekly earnings = $1,884.62 ÷ 2 = $942.31
Pay in lieu = $942.31 × 8 = $7,538.48
Block 17C (Pay in lieu of notice) = 7,538.48
Step 10 - Block 17C (Severance)
Severance = $942.31 × 10 = $9,423.10
Block 17C (Severance) = 9,423.10
NEW QUESTION # 13
A Third Party Demand is issued by the Canada Revenue Agency for:
Answer: C
Explanation:
A "Third Party Demand" in payroll collections commonly refers to the CRA's Demand on a Third Party (DTP)-a legal garnishment tool used to collect a person's debt to the government by requiring a third party (such as an employer or financial institution) to redirect funds that would otherwise be paid to the debtor.
CRA guidance explains that garnishments may be issued as a Requirement to Pay (RTP), Enhanced Requirement to Pay (ERTP), or Demand on a Third Party (DTP), and that these documents apply when money normally payable to someone who owes a debt to the government must instead be paid to the CRA (or other listed federal bodies).
This aligns with option B: unpaid income tax or unpaid statutory deductions (such as payroll source deductions) can lead to CRA collection action using these legal instruments.
Child support is generally enforced under provincial/territorial family support programs, not via CRA DTP as described here. Overpaid EI benefits are typically handled through EI/Service Canada recovery processes, and
"third-party creditor debt" is not a CRA-administered debt.
NEW QUESTION # 14
Which statutory deductions is salary continuance subject to?
Answer: D
NEW QUESTION # 15
......
If you are determined to purchase our PF1 valid exam collection materials for your companies, if you pursue long-term cooperation with site, we will have some relate policy. Firstly we provide one-year service warranty for every buyer who purchased PF1 valid exam collection materials. Every buyer can share one year free updates and preparation assist. Secondly if you want to get the free updates not just for one year, you want to still get the new version of National Payroll Institute PF1 valid exam collection materials after one year, you share 50% discount for the second year.
PF1 Exam Collection: https://www.examcost.com/PF1-practice-exam.html
P.S. Free 2026 National Payroll Institute PF1 dumps are available on Google Drive shared by ExamCost: https://drive.google.com/open?id=1gDRvV60QGn61OEL1Da3Ccp3CC93d9pbB