P.S. Free & New PF1 dumps are available on Google Drive shared by Itcertmaster: https://drive.google.com/open?id=1kDshc2W3XGlskq7v0DvJ9lzdoYfKU1Es
Our company will promptly update our PF1 exam materials based on the changes of the times and then send it to you timely. 99% of people who use our learning materials have passed the exam and successfully passed their certificates, which undoubtedly show that the passing rate of our PF1 Test Torrent is 99%. If you fail the exam, we promise to give you a full refund in the shortest possible time. So our product is a good choice for you. Choosing our PF1 study tool can help you learn better. You will gain a lot and lay a solid foundation for success.
| Section | Objectives |
|---|---|
| Topic 1: Payroll Fundamentals and Compliance Framework | - Payroll legislation and regulatory bodies
|
| Topic 2: Payroll Records and Compliance Reporting | - Government reporting
|
| Topic 3: Earnings, Deductions, and Taxation | - Types of earnings
|
>> National Payroll Institute PF1 Valid Test Cram <<
As you know, many exam and tests depend on the skills rather than knowledge solely. Our PF1 exam materials are time-tested materials for your information. There are free demos of our PF1 training guide for your reference with brief catalogue and outlines in them. For a PF1 study engine develop to full maturity, it is rewarding and hard. And we have engaged for more than ten years and successfully make every detail of our PF1 practice braindumps to be perfect.
NEW QUESTION # 11
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
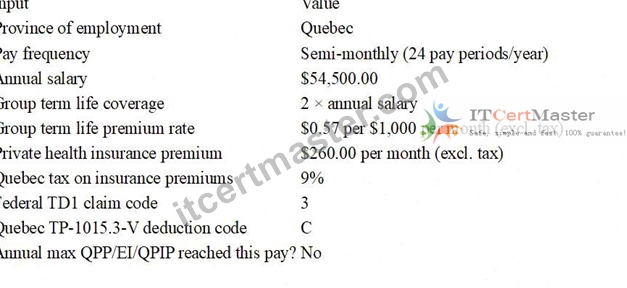
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases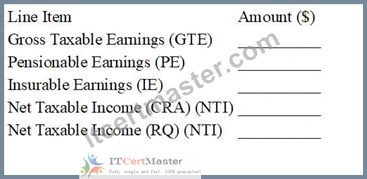
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
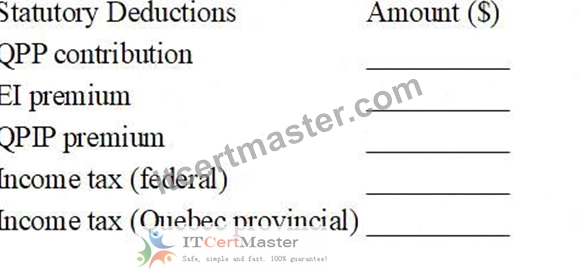
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
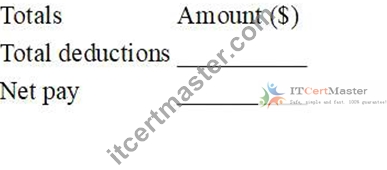
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
NEW QUESTION # 12
Paul Westin works for an Alberta organization and receives a regular salary of $1,800.00 semi-monthly. He will be receiving a payout of accrued vacation with no time taken of $1,400.00 on a separate cheque. He has federal and provincial TD1s on file with claim code 1. Calculate the income taxes to be withheld on his vacation pay.
Answer:
Explanation:
341.50
Explanation:
CRA's method for bonus/irregular payments paid separately is to calculate income tax on the combined pay (regular pay + the irregular payment) using the regular tax tables, then subtract the tax that would apply to the regular pay alone. The difference is the income tax to withhold from the irregular payment.
Here, the semi-monthly taxable pay is:
Regular pay = $1,800.00
Regular + vacation payout = $3,200.00
Using the 2026 Alberta semi-monthly (24 pay periods) tax tables with claim code 1:
At $1,800, Federal tax = $130.45 and Alberta tax = $58.55 # Total = $189.00.
At $3,200, Federal tax = $356.50 and Alberta tax = $174.00 # Total = $530.50.
Income tax on the vacation payout = $530.50 # $189.00 = $341.50.
CPP (including the enhanced portion) is a separate statutory deduction that must also be calculated on the payout, but this question asked specifically for income tax withholding.
NEW QUESTION # 13
Which of the following types of payments made by a private organization would not be subject to all statutory deductions?
Answer: D
Explanation:
The payment type most clearly not subject to all statutory deductions is directors' fees. CRA guidance on directors' fees shows they are treated as a special payment with distinct deduction rules, and (depending on the situation) they may not have CPP, EI, and income tax all apply in the same way as normal employment earnings.
By contrast, retroactive adjustments and performance bonuses are treated as taxable remuneration where CRA' s tools (like PDOC) calculate CPP contributions, EI premiums, and income tax on those payments (up to annual maximums).
"Vacation pay when no time was taken" is also treated as a non-periodic payment and is included in CRA payroll deduction formulas as a type of amount on which statutory deductions are calculated (again, subject to annual maximums for CPP/EI).
So, among the options listed, directors' fees are the one that would not necessarily be subject to all statutory deductions in the standard way.
NEW QUESTION # 14
An employee in Ontario was paid a $25,000.00 retiring allowance. The eligible portion was $15,000.00 and was transferred to the employee's Registered Retirement Savings Plan (RRSP) by the employer. Calculate the income tax on the non-eligible portion.
Answer: D
Explanation:
A retiring allowance is treated as a lump-sum payment for payroll withholding purposes. When part of a retiring allowance is transferred directly to an RRSP/RPP, CRA guidance indicates you do not withhold income tax on the transferred amount (up to the employee's available limit), because it is not paid to the employee in cash.
Step 1: Determine the portion paid directly to the employee (non-eligible portion):
$25,000 # $15,000 transferred to RRSP = $10,000 paid/remaining.
Step 2: Apply CRA lump-sum withholding rates (outside Quebec):
For total lump-sum payments $5,001 to $15,000, the withholding rate is 20%.
Step 3: Calculate tax to withhold on $10,000:
$10,000 × 20% = $2,000.00.
So the correct option is B ($2,000.00).
NEW QUESTION # 15
The Canada Revenue Agency form that is completed to allow a commissioned employee to claim non- reimbursed expenses at source is a:
Answer: B
Explanation:
The CRA form used to adjust payroll income tax withholdings at source for employees who earn commission income and have commission expenses is Form TD1X - Statement of Commission Income and Expenses for Payroll Tax Deductions. The CRA explains that an employee completes TD1X if they receive commission income (or salary plus commission) and want the employer to adjust tax deductions to take commission expenses into account.
This is different from:
TD1, which is the Personal Tax Credits Return used to claim basic/personal credits and determine standard withholding (not commission-expense adjustments).
T777, which is used to claim employment expenses on the employee's personal tax return (not to reduce payroll withholding at source).
TP-1015.R.13.1-V, which is a Quebec form used to request a reduction of Quebec income tax withholding in specific situations (not the CRA commission-expense at-source form).
Operationally, payroll should keep the TD1X on file and apply it to income tax withholding calculations until the employee updates or replaces it.
NEW QUESTION # 16
......
Our Payroll Fundamentals 1Exam study questions have a high quality, that mainly reflected in the passing rate. More than 99% students who use our PF1 exam material passed the exam and successfully obtained the relating certificate. This undoubtedly means that if you purchased PF1 exam guide and followed the information we provided you, you will have a 99% chance of successfully passing the exam. With PF1 Exam Guide, there will not be a situation like other students that you need to re-purchase guidance materials once the syllabus has changed. PF1 exam material not only helps you to save a lot of money, but also let you know the new exam trends earlier than others.
PF1 PDF: https://www.itcertmaster.com/PF1.html
P.S. Free & New PF1 dumps are available on Google Drive shared by Itcertmaster: https://drive.google.com/open?id=1kDshc2W3XGlskq7v0DvJ9lzdoYfKU1Es