BONUS!!! Download part of Dumpexams CIMAPRA19-F03-1 dumps for free: https://drive.google.com/open?id=1grAwwI1idc3ieqNptFqHjAFLci3ozhhG
If you are unfamiliar with our CIMAPRA19-F03-1 practice materials, please download the free demos for your reference, and to some unlearned exam candidates, you can master necessities by our CIMAPRA19-F03-1 training prep quickly. Our passing rate of the CIMAPRA19-F03-1 Study Guide has reached up to 98 to 100 percent up to now, so you cannot miss this opportunity. And you will feel grateful if you choose our CIMAPRA19-F03-1 exam questions.
| Section | Weight | Objectives |
|---|---|---|
| Business Valuation | 20% | - Valuation concepts and purposes
|
| Financial Policy Decisions | 15% | - Dividend and distribution policy
|
| Financial Risk Management | 15% | - Risk measurement and assessment
|
| Sources of Long-Term Finance | 25% | - Optimal capital structure
|
| Investment Appraisal and Decisions | 25% | - Advanced investment appraisal techniques
|
>> CIMAPRA19-F03-1 Exam Tutorial <<
We have chosen a large number of professionals to make CIMAPRA19-F03-1 learning question more professional, while allowing our study materials to keep up with the times. Of course, we do it all for you to get the information you want, and you can make faster progress. You can also get help from CIMAPRA19-F03-1 exam training professionals at any time when you encounter any problems. We can be sure that with the professional help of our CIMAPRA19-F03-1 Test Guide you will surely get a very good experience. Good materials and methods can help you to do more with less. Choose CIMAPRA19-F03-1 test guide to get you closer to success.
NEW QUESTION # 291
Providers of debt finance often insist on covenants being entered into when providing debt finance for companies.
Agreement and adherence to the specific covenants is often a condition of the loan provided by the lender.
Which THREE of the following statements are true in respect of covenants?
Answer: B,C,D
Explanation:
Discursive_F0
NEW QUESTION # 292
Company A operates in country A with the AS as its functional currency. Company A expects to receive BS500.000 in 6 months' time from a customer in Country B which uses the B$.
Company A intends to hedge the currency risk using a money market hedge
The following information is relevant: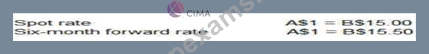
What is the AS value of the BS expected receipt in 6 months' time under a money market hedge?
Answer: D
NEW QUESTION # 293
A company has borrowings of S5 million on which it pays interest at 8%. It has an operating profit margin of
20%.
The company plans to increase borrowings by S2 million Interest on additional borrowings would be 10% and the operating profit margin would remain unchanged A debt covenant attached to the new borrowings requires interest cover to be at least 4 times throughout the period of the borrowing Interest cover is defined in the loan documentation as being based on operating profit What is the minimum sales value required each year to avoid a breach of the interest cover covenant'
Answer: B
Explanation:
Current debt interest:
Existing: 5m×8%=0.40m5\text{m} \times 8\% = 0.40\text{m}5m×8%=0.40m
New: 2m×10%=0.20m2\text{m} \times 10\% = 0.20\text{m}2m×10%=0.20m
Total interest = 0.60m
Let annual sales = SSS.
Operating profit margin = 20% # OP = 0.20 S.
Interest cover covenant:
0.20S0.60#4#0.20S#2.4#S#2.40.20=12.0 million\frac{0.20 S}{0.60} \ge 4 \Rightarrow 0.20 S \ge 2.4
\Rightarrow S \ge \frac{2.4}{0.20} = 12.0\ \text{million}0.600.20S#4#0.20S#2.4#S#0.202.4=12.0 million Correct answer: A. $12.00 million
NEW QUESTION # 294
Company GDD plans to acquire Company HGG, an unlisted company which has been in business for 3 years.
Company HGG has incurred losses in its first 3 years but is expected to become highly profitable in the near future There are no listed companies in the country operating in the same business field as Company HGG The future success of Company HGG's business and hence the future growth rate in earnings and dividends is difficult to determine Company GDD is assessing the validity of using the dividend growth method to value Company HGG Which THREE of the following are weaknesses of using the dividend growth model to value an unlisted company such as Company HGG?
Answer: A,C,D
Explanation:
Company HGG is young, unlisted, loss-making so far, and has uncertain growth.
Weaknesses of using the dividend growth model here:
A). Future growth rate in earnings/dividends is hard to estimate - very true for an early-stage, high-uncertainty business.
C). It has been unprofitable and has no established dividend pattern, so the basic inputs to the model (D# and g) are unreliable.
E). Cost of capital is difficult to estimate for an unlisted company (no directly observable beta or market data).
B is just a description of the model, not a specific weakness here, and D is incorrect because the dividend growth model does discount future dividends (it fully incorporates time value of money).
# Answer Q121: A, C, E
NEW QUESTION # 295
Company A is planning to acquire Company B.
Company A's managers think they can improve the performance of Company B to the extent that its own P/E ratio should be applied to Company B's earnings.
Relevant Data: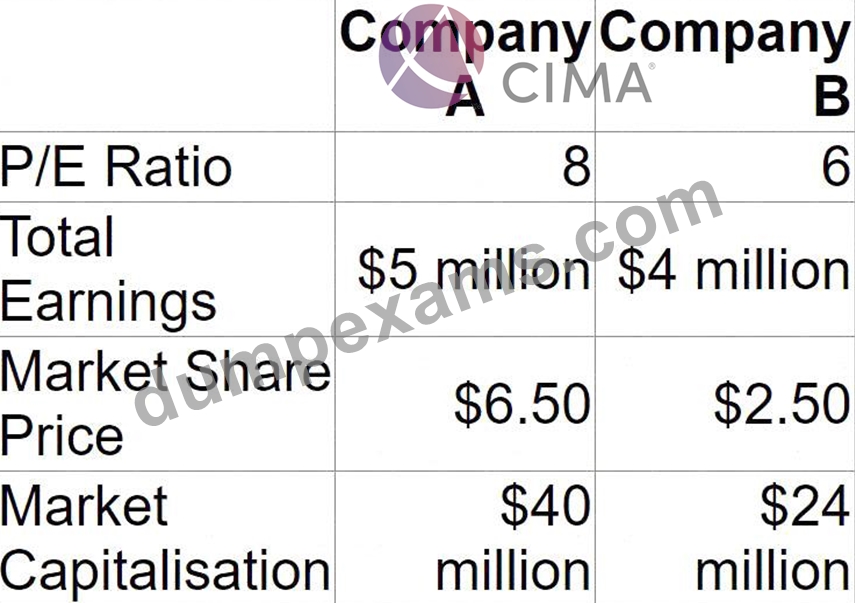
What is the expected synergy if the acquisition goes ahead?
Give your answer to the nearest $ million.
Answer:
Explanation:
$ ? million
8, 8000000
Comprehensive and Detailed Step-by-Step
Explanation:
(Based on CIMA F3: Financial Strategy Principles):In CIMA F3, the valuation of acquisition synergies is based on the principle that synergy equals the increase in combined firm value that arises because the acquiring company can improve the target firm's performance or efficiency. One of the core valuation tools taught in the syllabus is the Price/Earnings (P/E) multiple method, where the value of a company is determined by multiplying its earnings by the appropriate industry or company-specific P/E ratio.The scenario states that Company A believes it can improve Company B's performance sufficiently so that B's earnings should attract Company A's higher P/E ratio rather than its own lower ratio. This is a classic example of an "earnings uplift synergy," discussed frequently in F3 under the section covering mergers, acquisitions, and revaluation synergies.Step 1 - Revalue Company B using Company A's P/E ratioCompany B's current earnings:-Exhibit (a073f387-824e-4a5b-a1c6-4d72404346a7)- Company A's P/E ratio (to be applied):Expected post-acquisition value of Company B:Step 2 - Compare with current market value of Company BCurrent market capitalisation of Company B:-Exhibit (bee41617-
72c3-4f61-b9c2-dc66ad2e046d)-Step 3 - Calculate synergySynergy represents the additional value created above B's current standalone value:-Exhibit (ddc25633-cc16-4412-9577-0f5b4421b393)-This aligns with CIMA F3's framework: synergy is calculated as the difference between the post-acquisition value (based on improved performance and higher multiples) and the pre-acquisition market value.
NEW QUESTION # 296
......
If you don't pass the Selling F3 Financial Strategy (CIMAPRA19-F03-1) exam, Dumpexams will refund the money. Some terms and conditions related to the refund are given on the guarantee page. You will not find such excellent offers anywhere else. Therefore, don't miss this golden opportunity and F3 Financial Strategy (CIMAPRA19-F03-1) practice test material today!
VCE CIMAPRA19-F03-1 Exam Simulator: https://www.dumpexams.com/CIMAPRA19-F03-1-real-answers.html
BTW, DOWNLOAD part of Dumpexams CIMAPRA19-F03-1 dumps from Cloud Storage: https://drive.google.com/open?id=1grAwwI1idc3ieqNptFqHjAFLci3ozhhG