P.S. Free & New PF1 dumps are available on Google Drive shared by ITPassLeader: https://drive.google.com/open?id=1lgO-fC4N92xOptkLH2pu3weurizg5ocX
PF1 test questions have so many advantages that basically meet all the requirements of the user. If you have good comments or suggestions during the trial period, you can also give us feedback in a timely manner. Our study materials will give you a benefit as Thanks, we do it all for the benefits of the user. PF1 Study Materials look forward to your joining in.
| Section | Objectives |
|---|---|
| Topic 1: Payroll Fundamentals and Compliance Framework | - Payroll legislation and regulatory bodies
|
| Topic 2: Payroll Records and Compliance Reporting | - Government reporting
|
| Topic 3: Earnings, Deductions, and Taxation | - Types of earnings
|
Our PF1 exam guide question is recognized as the standard and authorized study materials and is widely commended at home and abroad. Our PF1 study materials boost superior advantages and the service of our products is perfect. We choose the most useful and typical questions and answers which contain the key points of the test and we try our best to use the least amount of questions and answers to showcase the most significant information. Our PF1 learning guide provides a variety of functions to help the clients improve their learning. For example, the function to stimulate the exam helps the clients test their learning results of the PF1 learning dump in an environment which is highly similar to the real exam.
NEW QUESTION # 53
Feraz Dalia is due $12,523.00 in legislated wages in lieu of notice that will be added to his last weekly pay of
$1,080.00. Calculate Feraz's Employment Insurance (EI) premium, if his employer is situated in Saskatchewan and the yearly maximum contribution will not be exceeded.
Answer:
Explanation:
$221.73 (employee EI premium)
Explanation:
In Saskatchewan (outside Quebec), EI premiums are deducted at the 2026 employee EI premium rate of $1.63 per $100 of insurable earnings (1.63%).
CRA guidance confirms that wages in lieu of termination notice are subject to EI premiums, and to determine statutory deductions you include the wages in lieu with the regular income (if any) for the pay period.
Step 1: Determine total insurable earnings in the final pay (assuming both amounts are insurable and the annual maximum won't be exceeded):
$12,523.00 + $1,080.00 = $13,603.00.
Step 2: Calculate EI premium:
$13,603.00 × 1.63% = $13,603.00 × 0.0163 = $221.7289, which rounds to $221.73.
So, the EI premium to deduct from Feraz's pay for this combined payment is $221.73.
NEW QUESTION # 54
The capital cost of an employer-owned vehicle includes:
Answer: D
Explanation:
For CRA automobile benefit purposes (standby charge on an employer-owned automobile), the "cost" used is the capital cost, which includes more than just the sticker price. CRA guidance states the cost includes the trade-in amount (if applicable), additions, and GST/HST and PST as part of the cost base used in the standby charge calculation.
Option D is the best match because it includes vehicle options/accessories, sales taxes, and additions that add to depreciation value. Importantly, CRA also notes that certain specialized equipment added to meet the requirements of a disabled person or employment (examples include heavy-duty suspension and power winches) is not considered part of the automobile's cost for standby charge purposes. This directly rules out options A and C, since they treat specialized equipment as part of capital cost. Option B is incorrect because CRA includes sales taxes (GST/HST and PST) in the cost base.
NEW QUESTION # 55
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
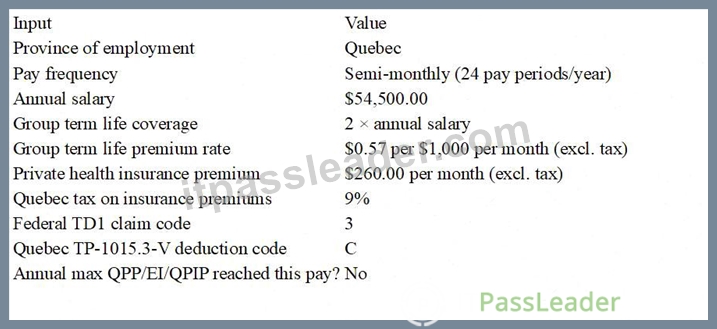
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases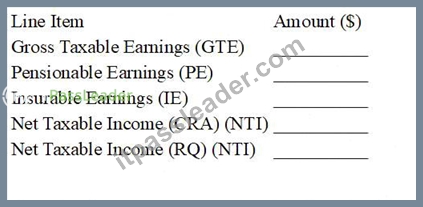
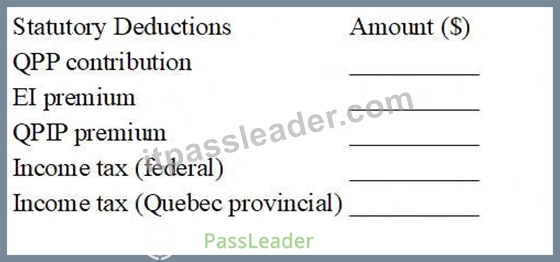
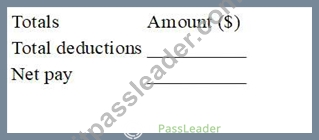
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
NEW QUESTION # 56
How many pay periods will be used to calculate insurable earnings inBlock 15Bon the Record of Employment if the employee is paidweekly?
Answer: D
Explanation:
For apaper ROE, Service Canada's ROE guidance uses a set number ofmost recent consecutive pay periods to support the reporting of insurable earnings. InBlock 15C(insurable earnings by pay period), the paper ROE provides27 fields, which allows reporting up to27 weekly pay periods(or fewer if the employee worked fewer periods).
Block15Bis thetotal insurable earningsfor the applicable number of consecutive pay periods, and for a weekly payroll this aligns with the same maximum count used on the paper ROE earnings grid-27periods.
Practically, this means payroll totals the employee's insurable earnings for thelast 27 consecutive weekly pay periodsleading up to the interruption of earnings (or the full period of employment if shorter). Using the correct number of pay periods ensures Service Canada has the right earnings history to adjudicate EI benefits accurately and reduces ROE processing issues.
NEW QUESTION # 57
Which of the following is not correct?
Answer: A
Explanation:
Option A is not correct. Service Canada's ROE guidance for paper ROEs explains that if you need to complete Block 15C, you do that first, and then you still enter the total insurable earnings in Block 15B. It also reminds employers to include any insurable separation payments entered in Block 17 in both Block 15C (Pay Period 1) and Block 15B totals.
Option C is correct because retiring allowances (often treated as severance-type amounts) are not insurable, so even if they appear in Block 17C, they are not added to Blocks 15B/15C.
Option D is correct because vacation pay paid on separation is reported in Block 17A, and when it is insurable, it must be included in the insurable earnings totals in Block 15B (and Block 15C P.P.1 where applicable).
NEW QUESTION # 58
......
Elaborately designed and developed PF1 test guide as well as good learning support services are the key to assisting our customers to realize their dreams. Our PF1 study braindumps have a variety of self-learning and self-assessment functions to detect learners’ study outcomes, and the statistical reporting function of our PF1 Test Guide is designed for students to figure out their weaknesses and tackle the causes, thus seeking out specific methods dealing with them. Our PF1 exam guide have also set a series of explanation about the complicated parts certificated.
PF1 Latest Dumps Ppt: https://www.itpassleader.com/National-Payroll-Institute/PF1-dumps-pass-exam.html
P.S. Free 2026 National Payroll Institute PF1 dumps are available on Google Drive shared by ITPassLeader: https://drive.google.com/open?id=1lgO-fC4N92xOptkLH2pu3weurizg5ocX