P.S. Free 2026 National Payroll Institute PF1 dumps are available on Google Drive shared by Itcertmaster: https://drive.google.com/open?id=1kDshc2W3XGlskq7v0DvJ9lzdoYfKU1Es
We can provide you with efficient online services during the whole day, no matter what kind of problems or consultants about our PF1 quiz torrent; we will spare no effort to help you overcome them sooner or later. First of all, we have professional staff with dedication to check and update out PF1 exam torrent materials on a daily basis, so that you can get the latest information from our PF1 Exam Torrent at any time. Besides our after-sales service engineers will be always online to give remote guidance and assistance for you if necessary. If you make a payment for our PF1 test prep, you will get our study materials in 5-10 minutes and enjoy the pleasure of your materials.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Individual Pay Calculations | 40% | - Regular earnings
|
| Topic 2: Record of Employment (ROE) | 20% | - ROE completion requirements
|
| Topic 3: Termination and Special Payments | 30% | - Termination payments
|
| Topic 4: Communication and Compliance | 10% | - Accuracy and documentation
|
Obtaining the PF1 certificate will make your colleagues and supervisors stand out for you, because it represents your professional skills. At the same time, it will also give you more opportunities for promotion and job-hopping. The PF1 latest exam dumps have different classifications for different qualification examinations, which can enable students to choose their own learning mode for themselves according to the actual needs of users. On buses or subways, you can use fractional time to test your learning outcomes with PF1 Test Torrent, which will greatly increase your pro forma efficiency.
NEW QUESTION # 66
Evangeline earns $1,075.00 weekly plus $154.00 in overtime. Calculate Evangeline's Quebec Parental Insurance Plan (QPIP) premium.
Answer:
Explanation:
$5.28 (employee QPIP premium for the week)
Explanation:
QPIP premiums are calculated on an employee's insurable earnings in Quebec (up to the annual maximum insurable earnings). For 2026, Revenu Quebec shows the employee QPIP premium rate is 0.430% (0.00430) and the maximum insurable earnings are $103,000.
Step 1: Determine Evangeline's weekly insurable earnings (assuming all earnings are QPIP-insurable and the annual maximum will not be exceeded, as the question implies):
Regular earnings $1,075.00 + overtime $154.00 = $1,229.00.
Step 2: Apply the employee QPIP rate:
$1,229.00 × 0.430% = $1,229.00 × 0.00430 = $5.2847.
Step 3: Round to cents (standard payroll practice): $5.28.
Payroll would deduct $5.28 from Evangeline's pay for QPIP for that week and remit it along with other source deductions as required. The deduction continues until the employee reaches the annual QPIP maximum premium (based on the annual insurable earnings limit).
NEW QUESTION # 67
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
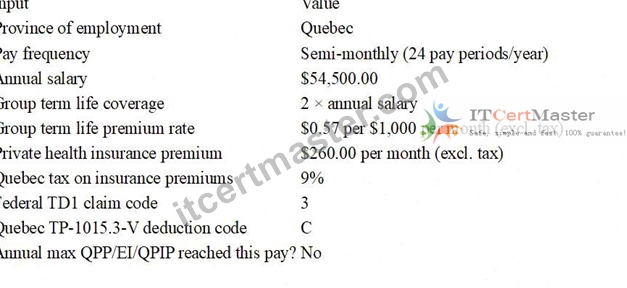
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases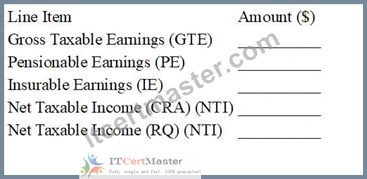
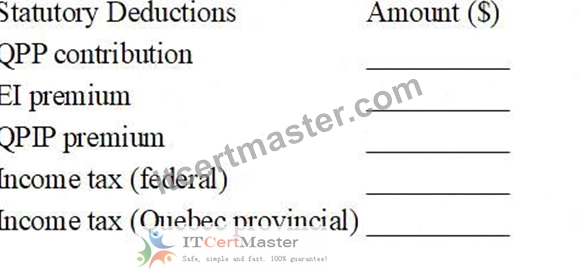
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
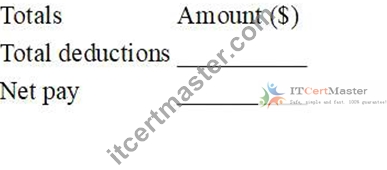
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
NEW QUESTION # 68
Vacation pay on termination would be recorded in which Block(s) on the Record of Employment?
Answer: C
Explanation:
Service Canada's ROE Guide is clear that vacation pay paid because of separation (termination/layoff) must be reported in Block 17A - Vacation pay.
But it doesn't stop there. Vacation pay is generally insurable earnings, so when you enter insurable earnings in Block 17A, you must also add those amounts into Block 15B (Total insurable earnings) and into Block
15C, Pay Period 1 (P.P. 1) as applicable. The ROE Guide explicitly states: when you enter insurable earnings in Blocks 17A/17B/17C, you must also add them to the totals in Blocks 15B and 15C (P.P. 1 field)-and it gives the example that vacation pay paid on separation must be added to 15B and 15C because it is insurable.
Therefore, vacation pay on termination is recorded in Blocks 15B, 15C P.P. 1, and 17A (option C).
NEW QUESTION # 69
The Canada Revenue Agency form that is completed to allow a commissioned employee to claim non- reimbursed expenses at source is a:
Answer: B
Explanation:
The CRA form used to adjust payroll income tax withholdings at source for employees who earn commission income and have commission expenses is Form TD1X - Statement of Commission Income and Expenses for Payroll Tax Deductions. The CRA explains that an employee completes TD1X if they receive commission income (or salary plus commission) and want the employer to adjust tax deductions to take commission expenses into account.
This is different from:
TD1, which is the Personal Tax Credits Return used to claim basic/personal credits and determine standard withholding (not commission-expense adjustments).
T777, which is used to claim employment expenses on the employee's personal tax return (not to reduce payroll withholding at source).
TP-1015.R.13.1-V, which is a Quebec form used to request a reduction of Quebec income tax withholding in specific situations (not the CRA commission-expense at-source form).
Operationally, payroll should keep the TD1X on file and apply it to income tax withholding calculations until the employee updates or replaces it.
NEW QUESTION # 70
Steve is physically disabled and his employer pays for his parking spot. This is considered:
Answer: A
Explanation:
Employer-provided parking is often a taxable benefit, generally valued at the fair market value of the parking spot. However, the CRA provides a specific exception for employees with disabilities. CRA guidance on employer-provided parking states that if your employee has a disability, the parking benefit is generally not taxable, including situations involving a severe and prolonged mobility impairment or blindness.
In Steve's case, the fact pattern explicitly says he is physically disabled and the employer pays for his parking.
Under CRA's general rule for disability-related parking, this would generally not be included in income as a taxable benefit, meaning it is not a taxable allowance and not a taxable benefit (cash or non-cash) for payroll purposes.
Payroll should still document why the parking is being treated as non-taxable (for example, disability-related need) and ensure the treatment aligns with CRA guidance if questioned. If the facts were different (non- disability parking or preferential parking provided to employees generally), the taxable benefit rules would usually apply.
NEW QUESTION # 71
......
Our PF1 study materials boost three versions and they include the PDF version, PC version and the APP online version. The clients can use any electronic equipment on it. If only the users’ equipment can link with the internet they can use their equipment to learn our PF1 study materials. They can use their cellphones, laptops and tablet computers to learn our PF1 study materials. The great advantage of the APP online version is if only the clients use our PF1 Study Materials in the environment with the internet for the first time on any electronic equipment they can use our PF1 study materials offline later. So the clients can carry about their electronic equipment available on their hands and when they want to use them to learn our PF1 study materials they can take them out at any time and learn offline.
PF1 Latest Training: https://www.itcertmaster.com/PF1.html
BONUS!!! Download part of Itcertmaster PF1 dumps for free: https://drive.google.com/open?id=1kDshc2W3XGlskq7v0DvJ9lzdoYfKU1Es