What's more, part of that Actualtests4sure Accounting-for-Decision-Makers dumps now are free: https://drive.google.com/open?id=1l3sQJqDqeHj0jBbgdcfBo-JKMGPmvH8Z
WGU Accounting-for-Decision-Makers exam dumps are important because they show you where you stand. After learning everything related to the WGU Accounting for Decision Makers C213 VAC2 (Accounting-for-Decision-Makers) certification, it is the right time to take a self-test and check whether you can clear the Accounting-for-Decision-Makers certification exam or not. People who score well on the Accounting-for-Decision-Makers Practice Questions are ready to give the final WGU Accounting for Decision Makers C213 VAC2 (Accounting-for-Decision-Makers) exam. On the other hand, those who do not score well can again try reading all the Accounting-for-Decision-Makers dumps questions and then give the Accounting-for-Decision-Makers exam.
| Section | Objectives |
|---|---|
| Business Decision Support | - Performance Measurement
|
| Managerial Accounting for Decision Making | - Cost Behavior
|
| Financial Accounting Fundamentals | - Financial Statements
|
>> Accounting-for-Decision-Makers Dumps Questions <<
We are amenable to offer help by introducing our Accounting-for-Decision-Makers real exam materials and they can help you pass the WGU Accounting for Decision Makers C213 VAC2 practice exam efficiently. All knowledge is based on the real exam by the help of experts. By compiling the most important points of questions into our Accounting-for-Decision-Makers guide prep our experts also amplify some difficult and important points. There is no doubt they are clear-cut and easy to understand to fulfill your any confusion about the exam. Our WGU Accounting for Decision Makers C213 VAC2 exam question is applicable to all kinds of exam candidates who eager to pass the exam. Last but not the least, they help our company develop brand image as well as help a great deal of exam candidates pass the exam with passing rate over 98 percent of our Accounting-for-Decision-Makers Real Exam materials.
NEW QUESTION # 56
Which internal control is intended to ensure that a company does not mistakenly pay a supplier for an invoice that includes more items than were actually received?
Answer: A
Explanation:
The correct answer is D . The control designed to prevent payment for goods not actually received is the receiving function's preparation of a receiving report , which is then sent to accounts payable and matched against the supplier invoice and purchase order. This is the essence of a three-way match : purchase order, receiving report, and vendor invoice. AccountingTools explains that payables staff should match the supplier invoice to the related purchase order and proof of receipt before authorizing payment.
Option A is helpful for controlling check completeness and sequence, but it does not verify quantities received. Option B adds authorization control over disbursements, but it also does not confirm whether the shipment matched the invoice. Option C helps ensure purchases are approved before ordering, but it still does not prove what was actually delivered. The receiving department's counting and inspection of goods, followed by forwarding the receiving documentation to accounts payable, directly addresses the risk that a supplier invoice includes more items than were received. Therefore, the best internal control is Option D .
NEW QUESTION # 57
Match each accounting term with its definition.
Answer options may be used more than once or not at all.
Select your answer from the pull-down list.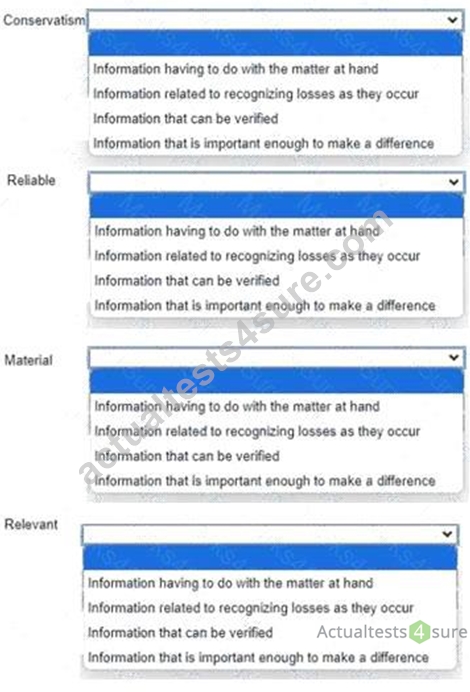
Answer:
Explanation:
Explanation:
Conservatism - Information related to recognizing losses as they occur
Reliable - Information that can be verified
Material - Information that is important enough to make a difference
Relevant - Information having to do with the matter at hand
These accounting terms describe important qualitative ideas used in financial reporting. Conservatism means accountants should use caution when uncertainty exists, especially by recognizing potential losses sooner rather than delaying them. Reliable information is information that can be supported, confirmed, or verified, which makes it trustworthy for users of financial statements. Material information is significant enough to affect the decisions of investors, creditors, or other users. If leaving it out or misstating it could influence a decision, it is material. Relevant information is information that relates directly to the issue being considered and is useful for decision-making.
These concepts help ensure that accounting information is useful, dependable, and meaningful. Relevance focuses on usefulness, reliability focuses on trustworthiness, materiality focuses on significance, and conservatism focuses on caution under uncertainty. Together, they support better financial statement preparation and interpretation. In this matching question, each term lines up with its most standard accounting definition, so the correct matches are exactly as shown above.
NEW QUESTION # 58
Which information does a balance sheet provide about a company?
Answer: D
Explanation:
A balance sheet shows the company's financial position at a specific point in time , so Option C is correct.
It reports what the business owns (assets), what it owes (liabilities), and usually owners' or stockholders' equity as of a particular date. This is why the balance sheet is often described as a snapshot rather than a report covering a span of time. Authoritative accounting learning materials describe the balance sheet as presenting assets, liabilities, and equity "as of" a date or at a specific moment.
Option A is incorrect because revenues and expenses for a period of time belong to the income statement , not the balance sheet. Option D is incorrect because cash collections and cash expenditures for a period of time are presented in the statement of cash flows . Option B is also incorrect because cash inflows and outflows are not reported only at a single point in time; they are summarized over a period. Therefore, the best answer is the one identifying the balance sheet as a statement of assets and liabilities at a specific point in time .
NEW QUESTION # 59
Which user group of financial statements evaluates the ability to repay loans?
Answer: A
Explanation:
The correct answer is C. Lenders because lenders use financial statements primarily to assess whether a company can repay borrowed money and meet interest and principal obligations. They focus heavily on liquidity, solvency, debt levels, and cash-generating ability before deciding whether to extend credit or approve loans. Accounting learning materials note that lenders often study ratios and financial statement relationships to determine whether a company can cover short-term and long-term obligations.
Management does use financial statements, but mainly for planning, controlling, and decision-making inside the business. Investors are more focused on profitability, growth, dividends, and return on investment.
Suppliers may review financial information when offering trade credit, but the group most directly concerned with the company's ability to repay loans is lenders. In practical terms, lenders analyze items such as current assets, current liabilities, total liabilities, operating cash flow, and interest coverage to judge repayment capacity. That makes them the user group most closely linked to evaluating loan repayment ability. Therefore, among the four options given, Lenders is the most accurate and best-supported answer from accounting theory and financial statement analysis.
NEW QUESTION # 60
A company manufactures and sells widgets. The following information is available:
* Total fixed costs per month are $300,000
* The variable cost per widget is $50
* Each widget sells for $100
How many widgets does the company need to sell each month to break even?
Answer: B
Explanation:
The correct answer is D. 6,000 . This is a standard cost-volume-profit (CVP) and break-even question. The break-even point in units is calculated by dividing total fixed costs by the contribution margin per unit .
First, compute contribution margin per widget:
Contribution margin per unit = Selling price - Variable cost
= $100 - $50 = $50
Now apply the break-even formula:
Break-even units = Fixed costs / Contribution margin per unit
= $300,000 / $50 = 6,000 widgets
This means the company must sell 6,000 widgets each month to generate enough contribution margin to cover all fixed costs. At that point, profit is zero, which is exactly what break-even means. If it sells more than
6,000 units, it earns a profit. If it sells fewer than 6,000, it incurs a loss.
The other choices are incorrect because they do not fully cover the fixed-cost amount using the $50 contribution margin per unit. Therefore, the correct break-even sales volume is 6,000 widgets , which makes Option D correct.
NEW QUESTION # 61
......
WGU Accounting for Decision Makers C213 VAC2 Accounting-for-Decision-Makers study guide are high quality, since we have a professional team to collect the information for the exam, and we can ensure you that Accounting-for-Decision-Makers study guide you receive are the latest information we have. In order to strengthen your confidence for WGU Accounting-for-Decision-Makers Exam Dumps, we are pass guarantee and money back guarantee.
Latest Accounting-for-Decision-Makers Exam Online: https://www.actualtests4sure.com/Accounting-for-Decision-Makers-test-questions.html
BONUS!!! Download part of Actualtests4sure Accounting-for-Decision-Makers dumps for free: https://drive.google.com/open?id=1l3sQJqDqeHj0jBbgdcfBo-JKMGPmvH8Z