What's more, part of that Fast2test PF1 dumps now are free: https://drive.google.com/open?id=1LNCfkaUR_Gx1CHP3QU54aXFlJbC_a6kC
Once you have any questions about our PF1 actual exam, you can contact our staff online or send us an email. We have a dedicated all-day online service to help you solve problems. Before purchasing, you may be confused about what kind of PF1 guide questions you need. You can consult our staff online. After the consultation, your doubts will be solved and you will choose the PF1 Learning Materials that suit you. Our online staff is professionally trained and they have great knowledge on the PF1 exam questions to help you pass the PF1 exam.
| Section | Objectives |
|---|---|
| Payroll Records and Compliance Reporting | - Government reporting
|
| Payroll Fundamentals and Compliance Framework | - Payroll legislation and regulatory bodies
|
| Earnings, Deductions, and Taxation | - Types of earnings
|
PF1 materials trends are not always easy to forecast, but they have predictable pattern for them by ten-year experience who often accurately predict points of knowledge occurring in next PF1 preparation materials. Our professional experts can give you the latest and the most accurate PF1 Training Material for that they have beening in this filed for so many years and know every aspect of the change of PF1 practice questions. You can trust in our PF1 learning braindump for sure.
NEW QUESTION # 66
What is piecework?
Answer: C
Explanation:
Piecework (also called piece-rate pay) is a pay method where an employee's earnings are determined by output-they are paid a set amount per unit produced or completed, rather than by hours worked or a fixed salary. This aligns directly with option C. A time-based hourly/daily wage (option A) is a different earnings method, and a fixed pay-per-period arrangement (option B) describes salary. Therefore, "all of the above" is incorrect because these are three distinct compensation structures.
In payroll calculations, piecework earnings are typically calculated as: piece rate × number of units produced in the pay period. Employers still have to ensure compliance with employment standards, such as minimum wage and overtime rules, even where piecework is used. A Canadian payroll educational reference defines piecework as payment for each unit produced "regardless of the amount of time taken."
NEW QUESTION # 67
A retiring allowance includes:
Answer: E
Explanation:
The CRA defines a retiring allowance (also called severance pay) as an amount paid when or after an employee retires or loses their job, in recognition of long service or for the loss of employment.
However, the CRA is also explicit about what a retiring allowance does not include. It does not include
"salary, wages, bonuses, [or] overtime," which rules out bonus/incentive pay and accumulated overtime in the options. It also does not include "payments for accumulated vacation leave not taken," which rules out vacation pay as a retiring allowance. Finally, it does not include wages in lieu of termination notice, which rules out wages in lieu (including legislated notice pay) as a retiring allowance.
Because every listed item is specifically excluded by CRA guidance, the correct answer is None of the above (E).
NEW QUESTION # 68
An employee who lives in Ontario and reports to work at a permanent establishment of the employer in Quebec will have income tax deducted based on which province?
Answer: C
Explanation:
For payroll deductions, the key concept is the employee's province of employment (POE)-not where they live. The CRA states that the POE is determined primarily by the employer's establishment where the employee "reports for work." If an employee reports for work at an employer's establishment located in Quebec, then the POE is Quebec, even if the employee's province of residence is Ontario.
This matters because Quebec has distinct payroll requirements. The CRA notes that when the POE is Quebec, employers must apply Quebec-based payroll rules, including deducting Quebec Pension Plan (QPP) contributions instead of CPP, and deducting Quebec parental insurance plan (QPIP) premiums, along with Quebec provincial income tax withholding.
In practice, payroll must set up the employee using Quebec as the POE and ensure stakeholders (HR, finance, the employee) understand why deductions may differ from Ontario residents working in Ontario. Any over
/under-withholding due to POE vs. residence is typically reconciled when the employee files their personal tax return.
NEW QUESTION # 69
Michael is an employee in Alberta who is paid bi-weekly and earns $1,600.00 per pay period. He has a taxable meal allowance of $30.00 per pay period. His federal and provincial TD1s on file show a claim code
2. Michael already reached the annual maximum first and second Canada Pension Plan (CPP) contributions before this pay. Calculate his total federal and provincial income taxes.
Answer:
Explanation:
(total federal + Alberta tax): $173.48
Explanation:
Taxable gross for the period = $1,600.00 + $30.00 = $1,630.00 (a taxable allowance is included in income for tax withholding).
Using CRA T4032-AB (Biweekly, 26 pay periods) with claim code 2:
Federal tax at pay $1,630 falls in the $1,619-$1,635 range # CC2 = $107.35.
Alberta provincial tax at pay $1,630 falls in the $1,628-$1,644 range # CC2 = $46.55.
Subtotal tax from the tables = $107.35 + $46.55 = $153.90.
CRA notes these tax tables build in the tax credits for CPP/EI, so when CPP is not deducted (because annual max already reached), you must increase tax withholding accordingly.
CPP that would have been deducted this pay (using CRA rates/YBE):
Pensionable = $1,630 # ($3,500/26 = $134.62) = $1,495.38; CPP (4.95% + 1.00% = 5.95%) = $88.98.
Add back missing credits: Federal 14% × 88.98 = $12.46; Alberta 8% × 88.98 = $7.12 # total $19.58.
Final total tax = $153.90 + $19.58 = $173.48.
NEW QUESTION # 70
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)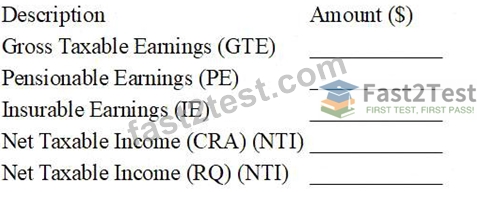
STATUTORY DEDUCTIONS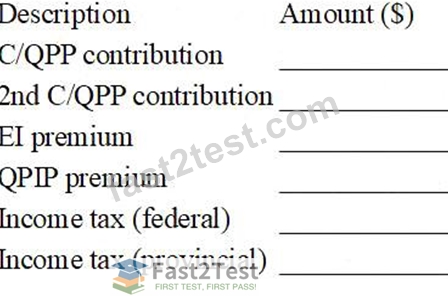
OTHER DEDUCTIONS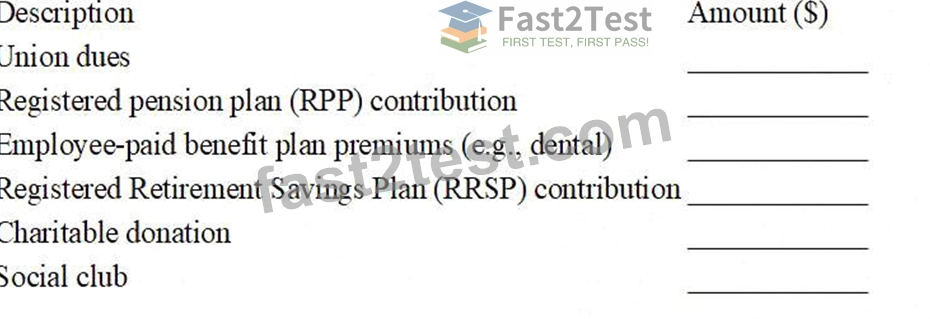
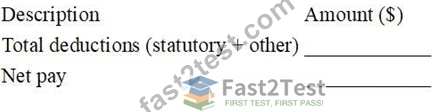
Given Data (Reference)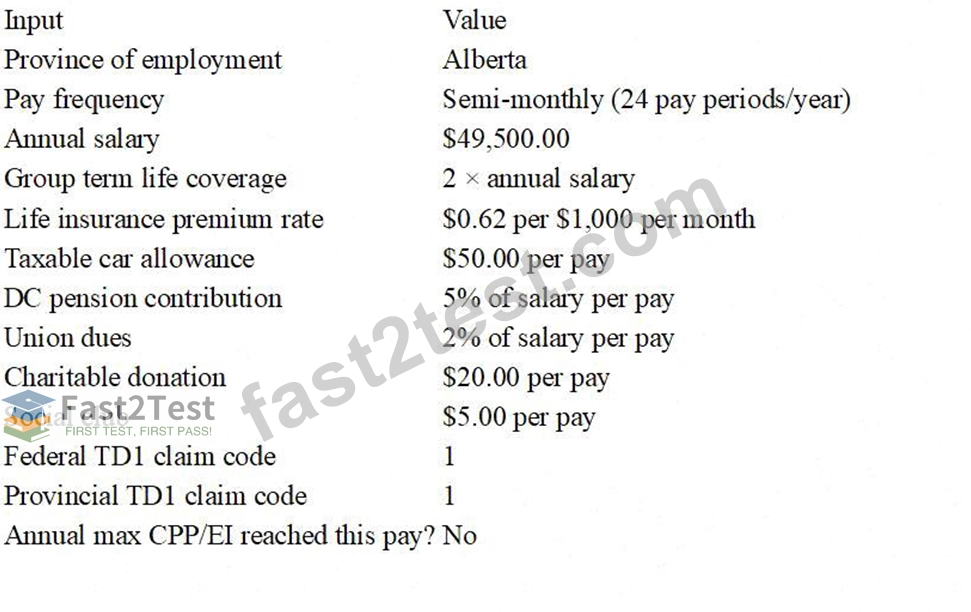
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
NEW QUESTION # 71
......
The web-based PF1 practice exam can be taken via the internet from any browser like Firefox, Safari, Opera, MS Edge, Internet Explorer, and Chrome. You don’t need to install any excessive plugins and software to take this National Payroll Institute PF1 Practice Test. Windows, Mac, iOS, Android, and Linux support this Payroll Fundamentals 1Exam (PF1) practice exam.
Reliable PF1 Test Pattern: https://www.fast2test.com/PF1-premium-file.html
BONUS!!! Download part of Fast2test PF1 dumps for free: https://drive.google.com/open?id=1LNCfkaUR_Gx1CHP3QU54aXFlJbC_a6kC