DOWNLOAD the newest PrepAwayTest Financial-Management PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1CliWvwYUUr0rg6hp0aSiLcIFqBTrI9XJ
No matter in China or other company, WGU has great influence for both enterprise and personal. If you can go through examination with Financial-Management latest exam study guide and obtain a certification, there may be many jobs with better salary and benefits waiting for you. Most large companies think a lot of IT professional certification. Financial-Management Latest Exam study guide makes your test get twice the result with half the effort and little cost.
| Section | Objectives |
|---|---|
| Topic 1: Capital Budgeting | - Decision Criteria
|
| Topic 2: Cost of Capital and Capital Structure | - Cost of Capital
|
| Topic 3: Working Capital Management | - Current Liabilities Management
|
| Topic 4: Time Value of Money | - Bond and Stock Valuation
|
| Topic 5: Financial Statement Analysis | - Ratio Analysis
|
| Topic 6: Financial Management Concepts | - Financial Environment
|
>> Financial-Management Valid Test Test <<
If you buy our Financial-Management study materials you will pass the Financial-Management test smoothly and easily. We boost professional expert team to organize and compile the Financial-Management training materials diligently and provide the great service which include the service before and after the sale, the 24-hours online customer service and refund service. Our Financial-Management real quiz boosts 3 versions and varied functions to make you learn comprehensively and efficiently. The learning of our study materials costs you little time and energy and we update them frequently. questions: WGU Financial Management VBC1 in detail please look at the introduction of our product as follow.
NEW QUESTION # 66
What is a primary goal of managing accounts receivable through credit policies?
Answer: D
Explanation:
The primary objective of accounts receivable management is to strike an optimal balance between increasing sales and maintaining healthy cash flows. Extending credit can stimulate demand and improve competitiveness, but excessive or poorly managed credit policies can lead to delayed cash inflows, higher bad debt losses, and increased financing costs. Financial management theory emphasizes evaluating credit standards, credit terms, and collection policies to ensure that the marginal benefit from additional sales exceeds the marginal cost of carrying receivables. These costs include opportunity costs of tied-up capital, administrative expenses, and default risk. Effective receivables management supports liquidity while preserving customer relationships. Option D accurately reflects this balanced objective, whereas the other options ignore either revenue growth or cash flow discipline.
NEW QUESTION # 67
Why might a firm's net income not equal its cash flows from operations for a period?
Answer: B
Explanation:
Net income and cash flow from operations are not the same because net income is prepared using accrual accounting, while cash flow from operations focuses on actual cash movement. Under accrual accounting, revenue may be recorded when earned rather than when cash is received, and expenses may be recorded when incurred rather than when cash is paid. In addition, net income includes noncash expenses such as depreciation and amortization, which reduce accounting profit without reducing current-period cash. Changes in working capital accounts, such as accounts receivable, inventory, and accounts payable, also create differences between net income and operating cash flow. For example, a company may report strong sales and net income, but if many customers have not yet paid, cash flow from operations may still be low. Financial statement analysis places strong emphasis on understanding these differences because cash flow is essential for liquidity, debt repayment, and ongoing operations. Choice A is correct because it directly captures the main reasons net income and cash flow from operations differ. The other choices incorrectly describe the purpose or nature of net income and cash flow reporting.
========
NEW QUESTION # 68
Which ratio indicates the ratio of a company's current assets relative to its current liabilities?
Answer: C
Explanation:
The current ratio measures a company's short-term liquidity by comparing current assets to current liabilities.
It is calculated as Current Assets ÷ Current Liabilities. This ratio indicates whether the firm has enough short- term resources, such as cash, accounts receivable, and inventory, to meet obligations due within one year. A current ratio above 1.0 generally suggests that current assets exceed current liabilities, although the ideal level depends on the industry and the nature of the business. Financial managers and analysts use the current ratio to evaluate liquidity risk, operating flexibility, and working capital strength. Choice B is correct because it directly matches the definition in the question. Choice A is incorrect because fixed asset turnover measures how efficiently fixed assets generate sales. Choice C is incorrect because working capital turnover focuses on sales relative to net working capital rather than simply comparing current assets and current liabilities. Choice D is incorrect because inventory turnover measures how efficiently inventory is sold and replaced. Therefore, B is the correct answer because the current ratio is the standard liquidity ratio used to compare current assets with current liabilities.
========
NEW QUESTION # 69
What are opportunity costs in the context of inventory management?
Answer: B
Explanation:
Opportunity cost represents the return a firm forgoes by investing resources in one use instead of the next best alternative. In inventory management, capital tied up in inventory cannot be used for other value-generating activities such as investing in new projects, paying down debt, or returning cash to shareholders. Financial management emphasizes opportunity cost as a key component of inventory carrying costs, along with storage, insurance, and obsolescence. Ignoring opportunity costs can lead to excessive inventory levels and reduced firm value. Option B correctly identifies this fundamental concept.
NEW QUESTION # 70
Ratios for Freedom Rock Bicycles are shown below, along with industry average ratios.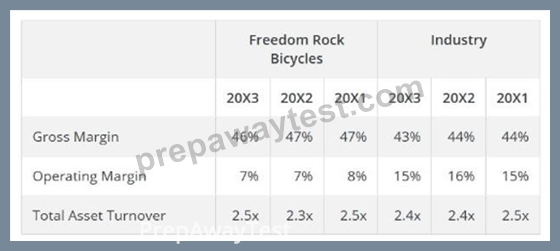
What are appropriate recommendations for Freedom Rock Bicycles based on this analysis?
Answer: B
Explanation:
The data show that Freedom Rock Bicycles has gross margins comparable to or slightly above the industry but significantly lower operating margins. This indicates that the problem is not production efficiency or cost of goods sold, but rather operating expenses such as selling, general, and administrative costs or fixed overhead. Additionally, asset turnover is roughly in line with industry averages, suggesting that asset utilization is not the primary issue. From a financial management perspective, when gross margin is healthy but operating margin lags, the logical focus is on controlling non-production costs and evaluating fixed cost structures. Reducing unnecessary overhead, improving operating efficiency, or restructuring fixed expenses can directly improve operating margin and overall profitability. Option C best reflects this targeted, ratio-driven recommendation. The other options either misdiagnose the problem or focus on areas already performing adequately relative to peers.
NEW QUESTION # 71
......
If you are really not sure which version you like best, you can also apply for multiple trial versions of our Financial-Management exam questions. We want our customers to make sensible decisions and stick to them. Financial-Management study engine can be developed to today, and the principle of customer first is a very important factor. Financial-Management Training Materials really hope to stand with you, learn together and grow together.
Financial-Management PDF: https://www.prepawaytest.com/WGU/Financial-Management-practice-exam-dumps.html
DOWNLOAD the newest PrepAwayTest Financial-Management PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1CliWvwYUUr0rg6hp0aSiLcIFqBTrI9XJ